China compliance calendar

8 recurring 增值税 (VAT), 消费税 (consumption tax), 增值税、消费税 (import VAT and consumption tax, collected by customs) and All taxes, VAT included (税务登记) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new China rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Return filing Law change takes effect

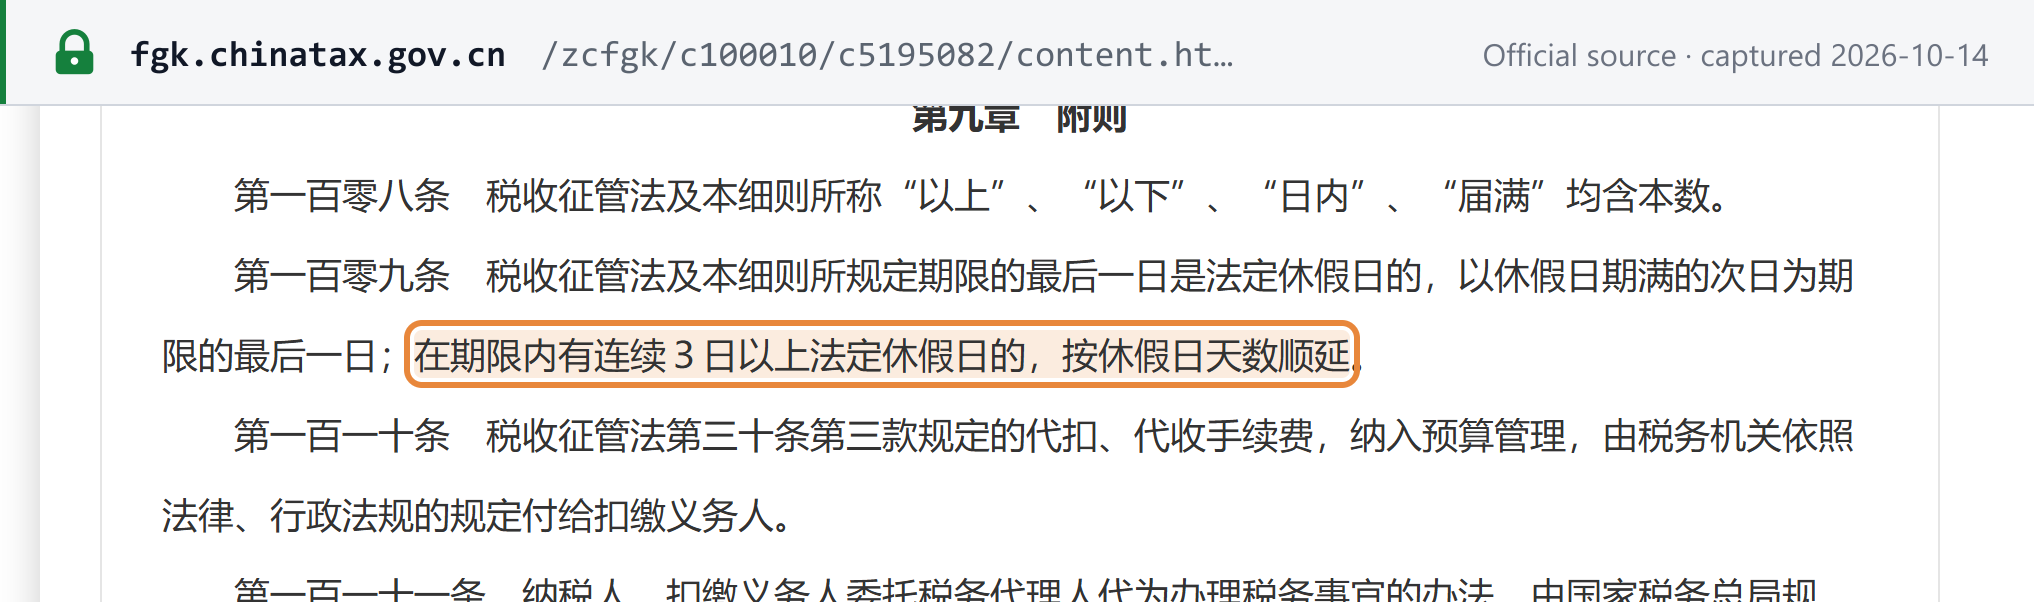
No obligation here shifts for a weekend or public holiday. Where that is China's own rule the date stands as shown; where a shift exists but is not modelled, the obligation's notes say so. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

增值税申报 — monthly VAT return and payment

增值税 (VAT) · Monthly · return filing

12 published dates, 20 Jan 2026 to 15 Dec 2026 Verified 2026-10-21
Who files
General taxpayers (一般纳税人) — businesses with annual taxable sales above RMB 5 million or registered as general taxpayers — and any other taxpayer the tax office assigns a one-month period
Notes
The return and the payment are one step, and each date covers the month before it: the October date, for example, settles September. By law the deadline is 15 days after the month ends, but a weekend or a public holiday pushes it later, and the National Day week moved October 2026's to the 26th; January, April and May were likewise extended by their holidays. The 2027 dates are not yet published: the tax office sets them each December, once the State Council has fixed the year's public holidays. City maintenance and construction tax and the education surcharges are paid on the same return. File even for a month with nothing to declare; tax paid late costs 0.05% of the unpaid amount for every day it is overdue.
Source
国家税务总局办公厅关于明确2026年度申报纳税期限的通知(税总办征科函〔2025〕64号)— STA notice fixing the 2026 filing and payment deadlines State Taxation Administration (国家税务总局政策法规库)
See the source text
“八、10月1日至7日放假7天,申报纳税期限顺延至10月26日。”
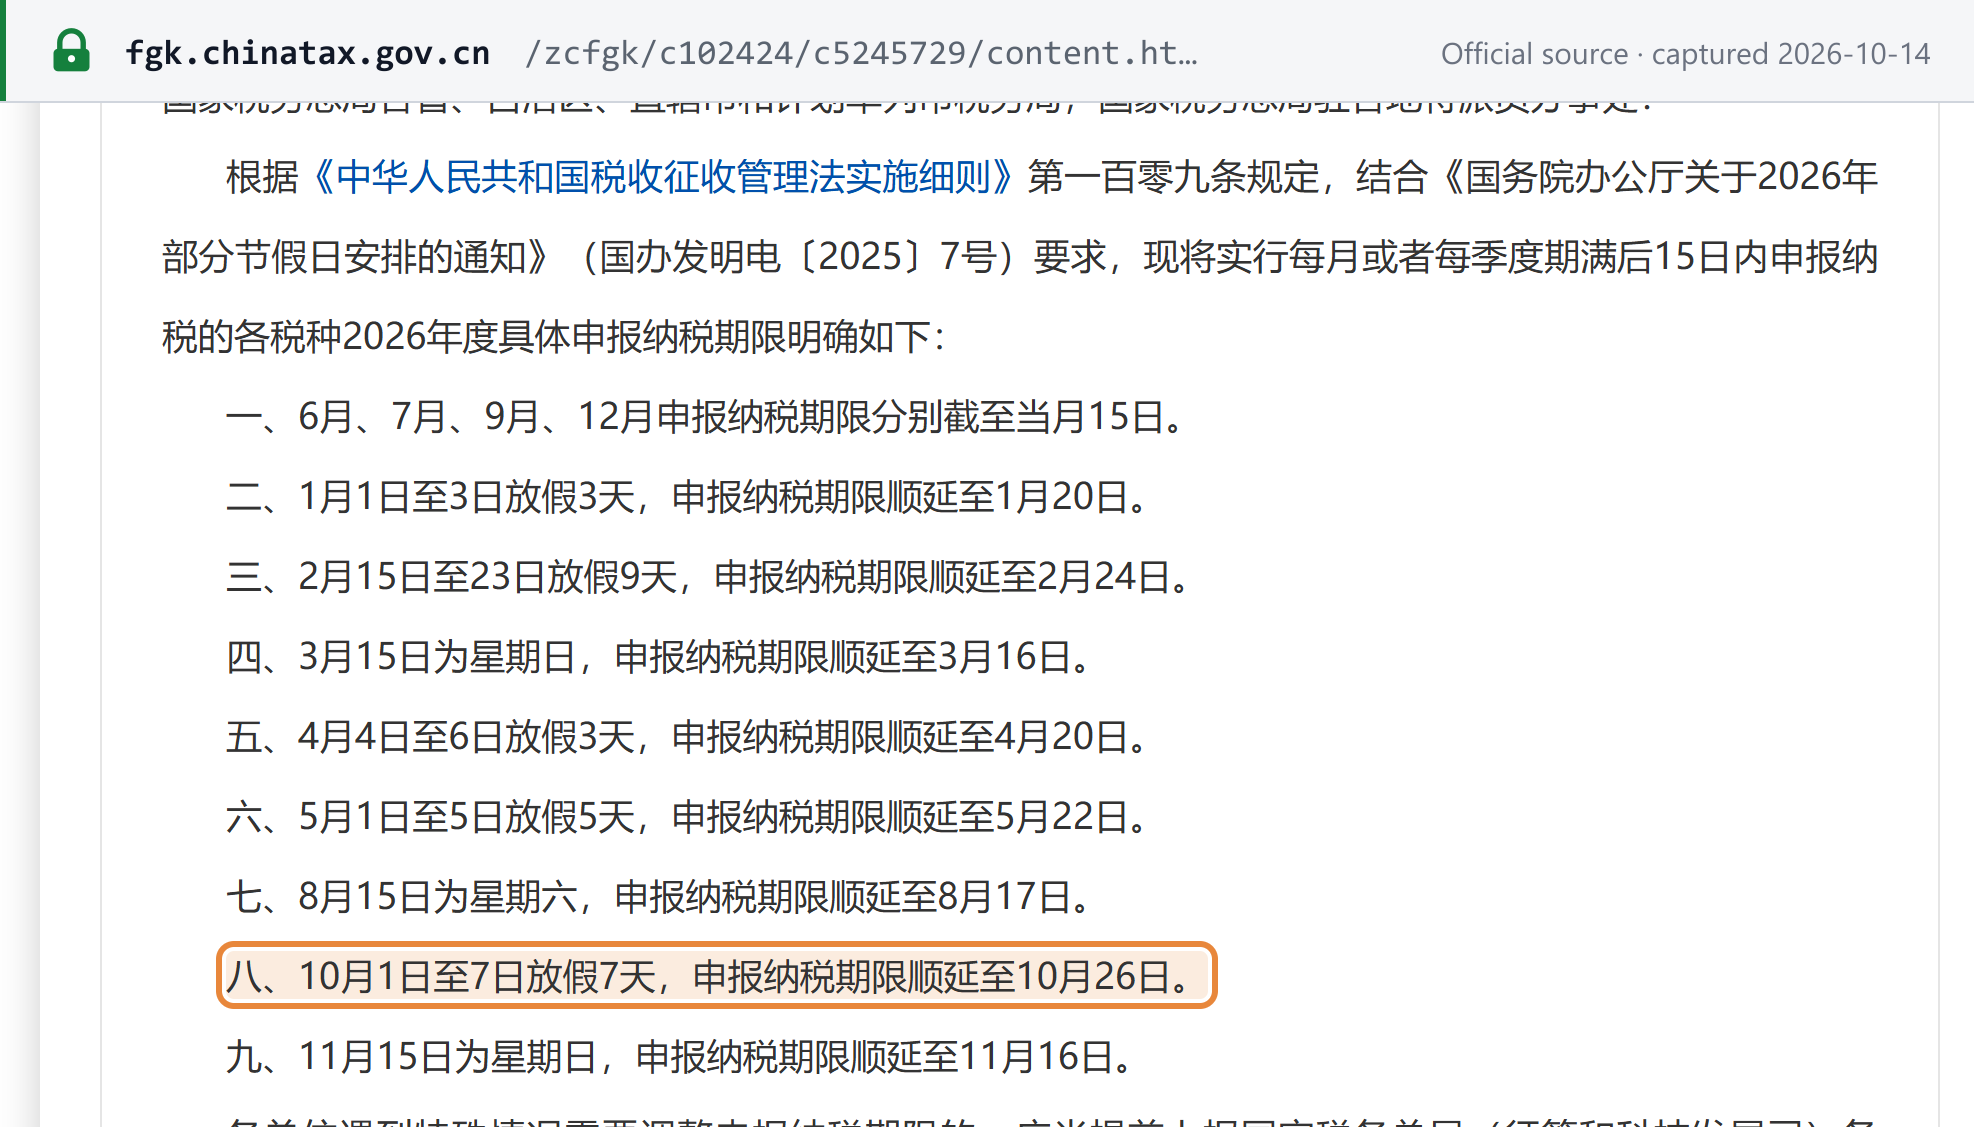
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 增值税申报 — monthly VAT return and payment deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14
增值税申报 — quarterly VAT return and payment

增值税 (VAT) · Quarterly · return filing

5 published dates, 20 Jan 2026 to 15 Jan 2027 Verified 2026-10-21
Who files
Small-scale taxpayers (小规模纳税人, annual taxable sales not over RMB 5 million) and, among general taxpayers, banks, finance companies, trust companies and credit cooperatives, and any other taxpayers the STA and the Ministry of Finance designate — where the tax office assigns them a one-quarter period
Notes
Quarterly filing is permitted rather than automatic: the tax office decides each taxpayer's period. Each date is for the quarter just ended, so the October date settles July to September; in 2026 it fell on 26 October, eleven days after the usual 15th, because of the National Day holiday. The return for October to December is due in January 2027. The tax office has not yet published that date (it normally does so in December), so the calendar shows 15 January 2027, the deadline set by law: holidays can only push the real date later, never earlier. A small-scale taxpayer with no VAT to pay for the quarter still files.
Source
国家税务总局办公厅关于明确2026年度申报纳税期限的通知(税总办征科函〔2025〕64号)— STA notice fixing the 2026 filing and payment deadlines State Taxation Administration (国家税务总局政策法规库)
See the source text
“五、4月4日至6日放假3天,申报纳税期限顺延至4月20日。”
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 增值税申报 — quarterly VAT return and payment deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14
消费税申报 — consumption tax return and payment

消费税 (consumption tax) · Monthly · return filing

12 published dates, 20 Jan 2026 to 15 Dec 2026 Verified 2026-10-21
Who files
Producers and contract processors of goods subject to consumption tax (tobacco, alcohol, high-end cosmetics, jewellery, fireworks, refined oil, motor vehicles and the other listed items), and the businesses taxed at a later stage — retailers of gold, silver and platinum jewellery and diamonds, retailers of super-luxury cars and wholesalers of cigarettes — on a monthly period; quarterly filers, where the tax office sets one, use the January, April, July and October dates
Notes
Consumption tax runs on the same published calendar as VAT: the 16 November 2026 date settles October's sales, and the extended dates apply to it just as they do to VAT. Many producers owe both and settle them together, with the city maintenance tax and education surcharges calculated on the two combined. Consumption tax on imported goods is paid to customs at the border, not on this return.
Source
国家税务总局办公厅关于明确2026年度申报纳税期限的通知(税总办征科函〔2025〕64号)— STA notice fixing the 2026 filing and payment deadlines State Taxation Administration (国家税务总局政策法规库)
See the source text
“现将实行每月或者每季度期满后15日内申报纳税的各税种2026年度具体申报纳税期限明确如下:”
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 消费税申报 — consumption tax return and payment deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14
代扣代缴自然人增值税 — monthly withholding return for payments to individuals

增值税 (VAT) — withholding on resident individuals · Monthly · return filing

15 Dec 2026 Verified 2026-10-21
Who files
Businesses and other units in China that pay resident individuals for R&D, software, design, consulting, radio, film and TV production, cultural or education services, from 1 November 2026; individuals handled under the platform-economy reporting rules are excluded
Notes
New from 1 November 2026 under MOF/STA Announcement 2026 No. 28: when a business pays a resident individual for these services it withholds the VAT and surcharges at the time of payment, then files a withholding return and pays over the month's total within 15 days from the start of the next month. The first one, for November payments, is due Tuesday 15 December 2026. A return is still owed for an individual from whom nothing was withheld — because the payment was under the per-transaction threshold, exempt, or already paid by the individual.
Source
境内单位代扣代缴自然人增值税管理办法 — 第五条 (Measures attached to MOF/STA Announcement 2026 No. 28) Ministry of Finance / State Taxation Administration (via the Hainan Provincial Tax Service)
See the source text
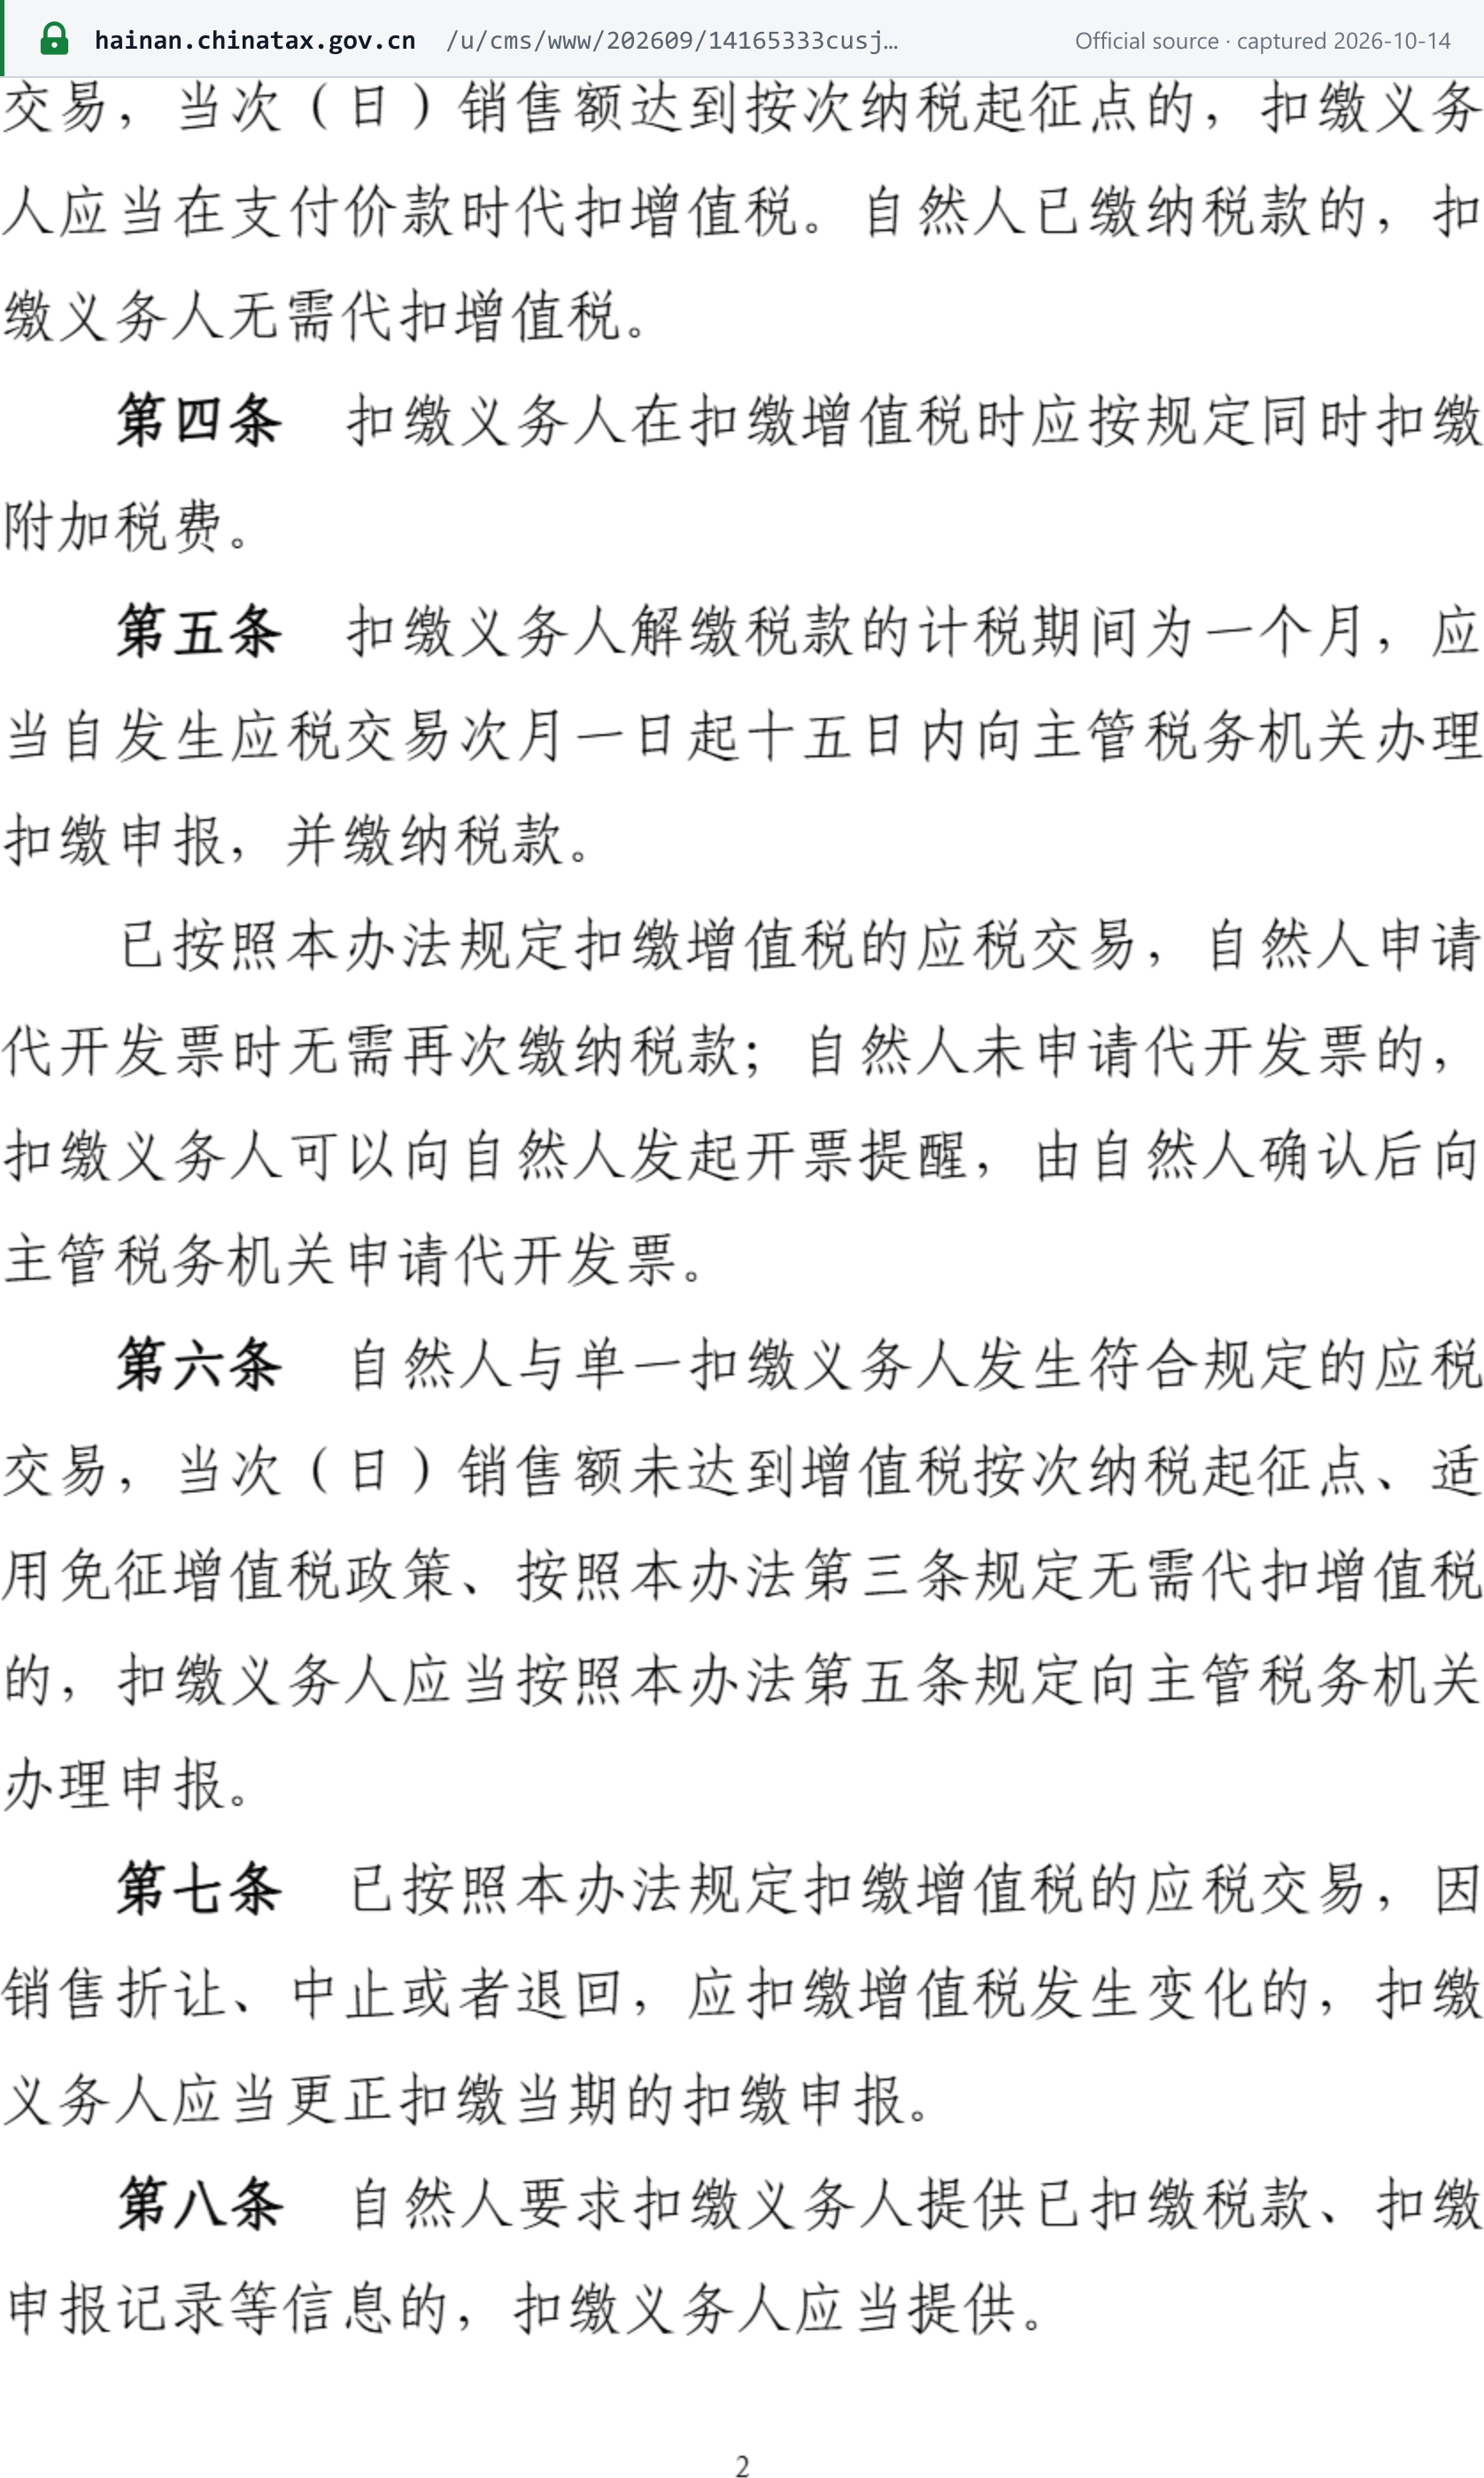
“扣缴义务人解缴税款的计税期间为一个月,应当自发生应税交易次月一日起十五日内向主管税务机关办理扣缴申报,并缴纳税款。”
Screenshot of Ministry of Finance / State Taxation Administration (via the Hainan Provincial Tax Service) showing the 代扣代缴自然人增值税 — monthly withholding return for payments to individuals deadline Open full size Captured from Ministry of Finance / State Taxation Administration (via the Hainan Provincial Tax Service) on 2026-10-14

代扣代缴增值税 — buyer's withholding of VAT on payments to foreign suppliers

增值税 (VAT) — withholding by the purchaser · Monthly · return filing

12 published dates, 20 Jan 2026 to 15 Dec 2026 Verified 2026-10-21
Who files
Buyers in China — businesses and other purchasers — paying a foreign unit or individual for a taxable transaction in China, unless the foreign seller has appointed a domestic agent to file and pay; buyers on a quarterly period use the January, April, July and October dates
Notes
When a foreign business with no domestic agent sells into China, the Chinese buyer is responsible for the VAT: it withholds the tax from the payment and reports and pays it over on its own filing deadline, on the same published dates as its VAT return. The duty to withhold arises on the same day as the seller's VAT liability, and that day decides which month's return the tax belongs to: tax withheld in September 2026 was due by 26 October 2026. Dates for 2027 are not yet published.
Source
中华人民共和国增值税法 — 第三十条第三款 (VAT Law, Art. 30 para 3; purchaser as withholding agent: Art. 15) State Taxation Administration (国家税务总局政策法规库)
See the source text
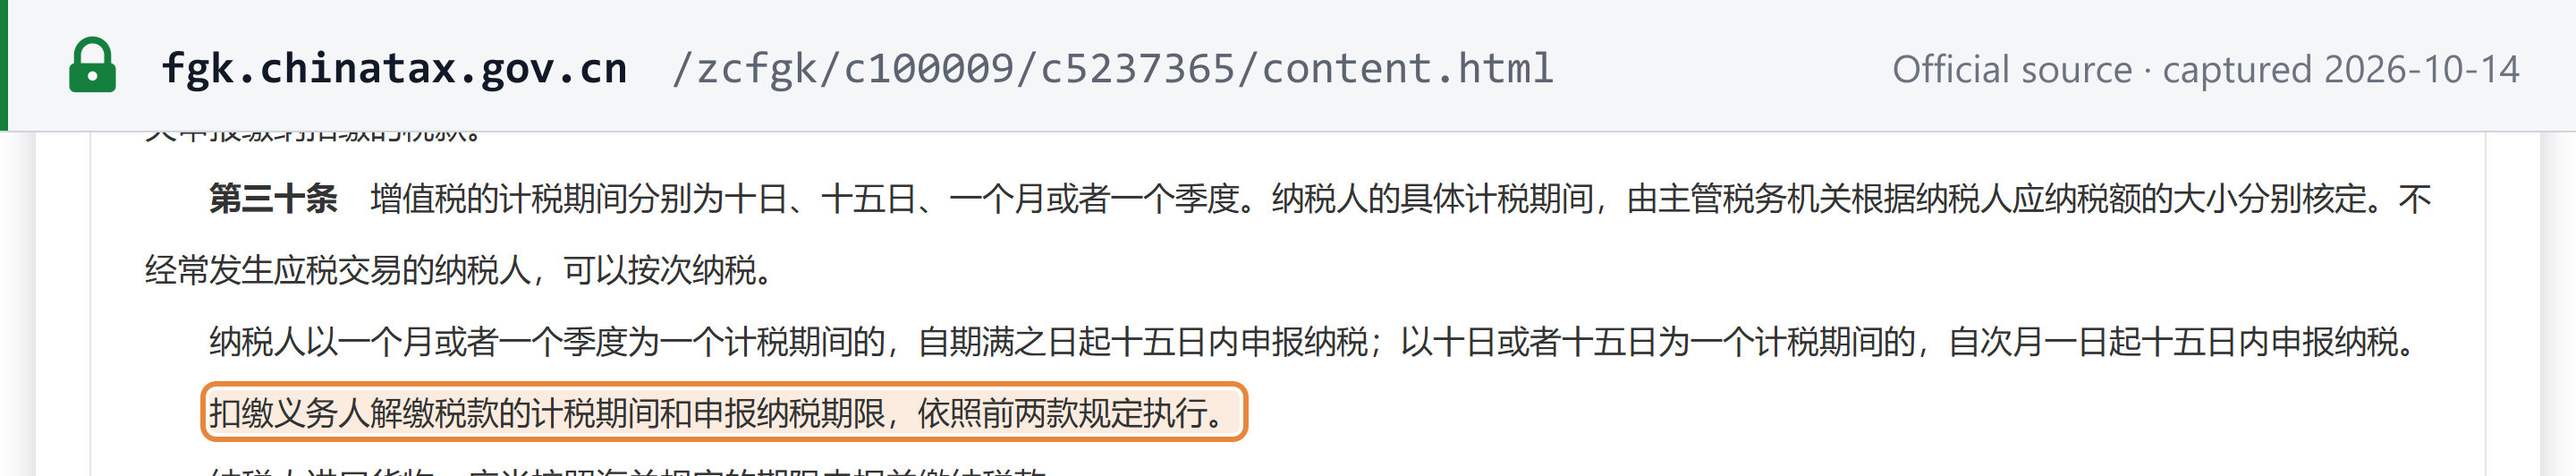
“扣缴义务人解缴税款的计税期间和申报纳税期限,依照前两款规定执行。”
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 代扣代缴增值税 — buyer's withholding of VAT on payments to foreign suppliers deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14
进口环节增值税 — import VAT and consumption tax payment to customs

增值税、消费税 (import VAT and consumption tax, collected by customs) · One-off · payment

within 15 days of completion of the customs import declaration Verified 2026-10-14
Who files
Importers of goods into mainland China, paying the import VAT (and any consumption tax) that customs collects on each declaration
Notes
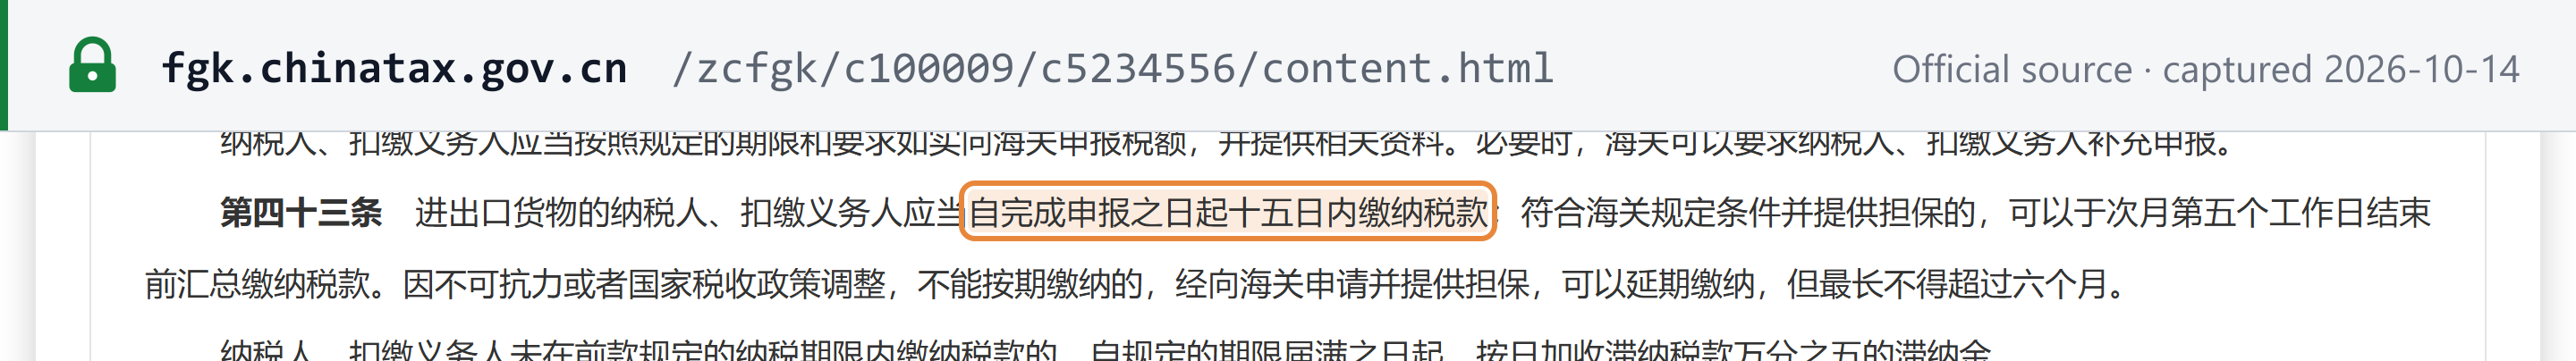
Customs, not the tax office, collects VAT and consumption tax on imports, and the money is due within 15 days of the day the import declaration is completed. Importers that meet customs' conditions and lodge a guarantee can instead pay a whole month's import taxes together, by the end of the fifth working day of the following month.
Source
中华人民共和国关税法 — 第四十三条 (Customs Tariff Law, Art. 43; applied to import-stage taxes by Art. 70) State Taxation Administration (国家税务总局政策法规库)
See the source text
“进出口货物的纳税人、扣缴义务人应当自完成申报之日起十五日内缴纳税款;符合海关规定条件并提供担保的,可以于次月第五个工作日结束前汇总缴纳税款。”
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 进口环节增值税 — import VAT and consumption tax payment to customs deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14
税务登记 — tax registration after receiving the business licence

All taxes, VAT included (税务登记) · One-off · registration

within 30 days of receipt of the business licence Verified 2026-10-14
Who files
Enterprises, branches and places of business set up in another locality, individual businesses (个体工商户) and public institutions engaged in business; there is no VAT registration threshold
Notes
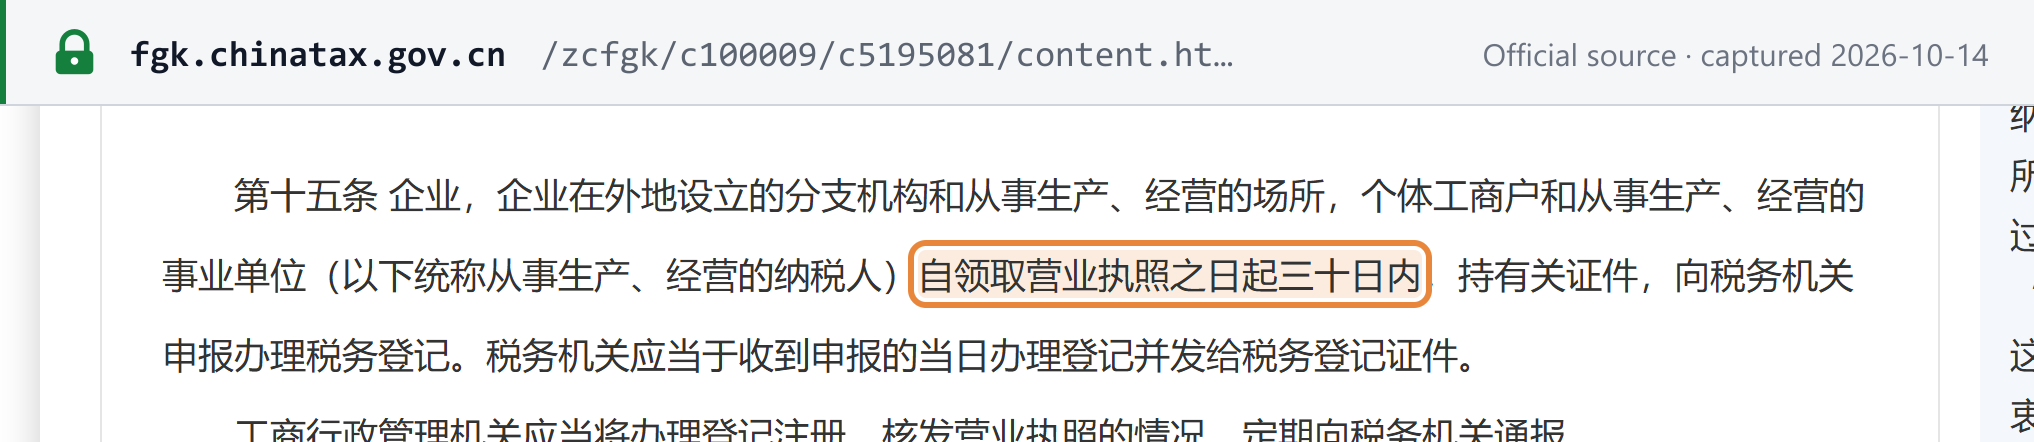
A new business must apply for tax registration within 30 days of receiving its business licence. Because the licence now carries the unified social credit code and doubles as the tax registration certificate, in practice this means confirming your registration details with the tax office within that window. Every business is a VAT taxpayer from the start; the RMB 5 million line decides only whether it is a small-scale or a general taxpayer.
Source
中华人民共和国税收征收管理法 — 第十五条 (Tax Collection and Administration Law, Art. 15) State Taxation Administration (国家税务总局政策法规库)
See the source text
“自领取营业执照之日起三十日内,持有关证件,向税务机关申报办理税务登记。”
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 税务登记 — tax registration after receiving the business licence deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14
一般纳税人登记 — general-taxpayer registration after sales pass RMB 5 million

增值税 (VAT) · One-off · registration

within 15 days of the end of the month in which annual taxable sales first exceed RMB 5 million Verified 2026-10-14
Who files
Small-scale taxpayers whose taxable sales over any run of up to 12 consecutive months or four quarters exceed RMB 5 million, other than individuals and non-business units that may elect to stay small-scale
Notes
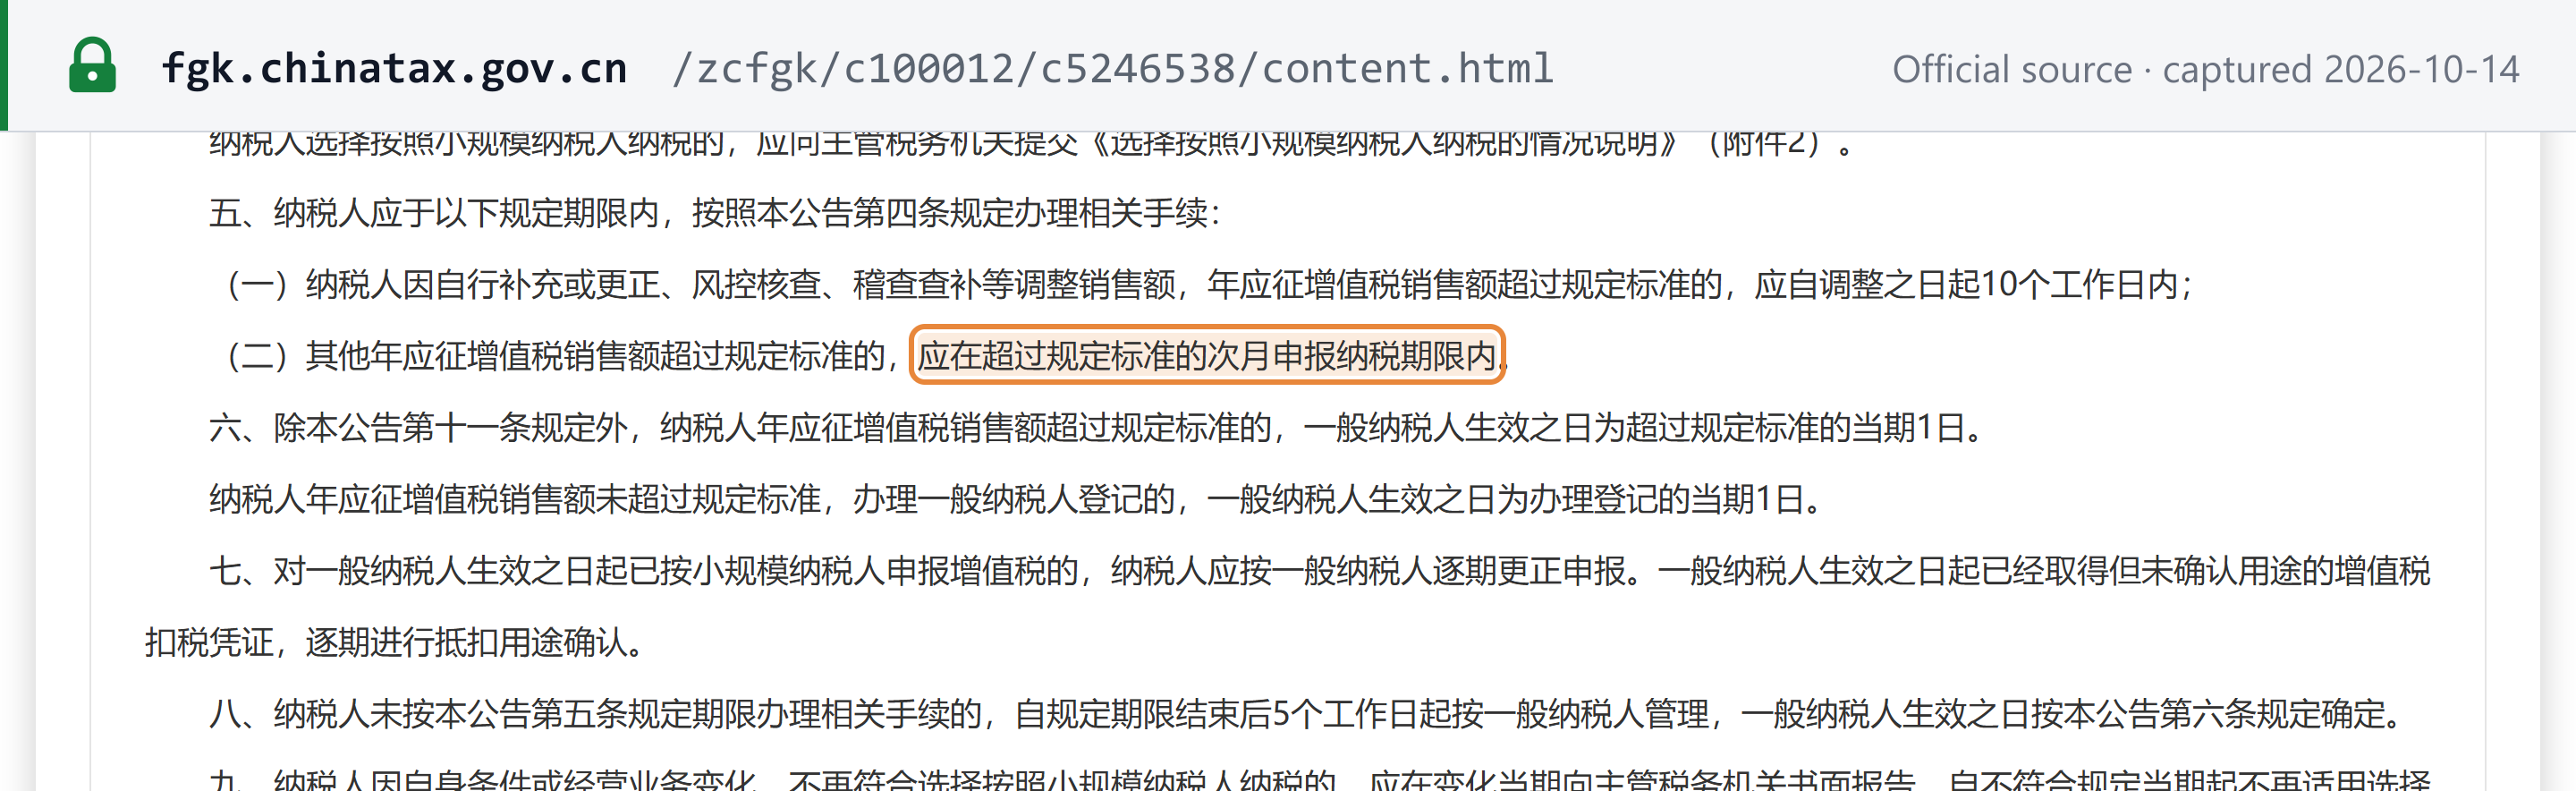
Register as a general taxpayer by the filing deadline of the month after you cross RMB 5 million — usually the 15th, later in holiday months. Cross the line in November 2026, for example, and you register by the December filing deadline. If the line is crossed only because sales were corrected, picked up in a risk review or added by an audit, you have 10 working days from that adjustment. Status runs from the start of the period in which the line was crossed, so returns already filed as small-scale must be corrected, and a business that misses the deadline is treated as a general taxpayer anyway from five working days after it.
Source
国家税务总局关于增值税一般纳税人登记管理有关事项的公告 (STA Announcement 2026 No. 2) — 第五条 State Taxation Administration (国家税务总局政策法规库)
See the source text
“(二)其他年应征增值税销售额超过规定标准的,应在超过规定标准的次月申报纳税期限内。”
Screenshot of State Taxation Administration (国家税务总局政策法规库) showing the 一般纳税人登记 — general-taxpayer registration after sales pass RMB 5 million deadline Open full size Captured from State Taxation Administration (国家税务总局政策法规库) on 2026-10-14

Mainland China only; Hong Kong, Macau and Taiwan run separate systems. VAT, consumption tax and the surcharges that ride on them are filed and paid together, in one step, within 15 days of the end of each month or quarter. The legal deadline is the 15th, but it moves later when the 15th is a weekend or holiday, or when a public holiday of three days or more falls in the first half of the month, and the tax office publishes each year's actual dates every December. The 2026 dates below are those published dates. The 2027 dates are not out yet; they normally appear in December, after the State Council announces the year's public holidays. When a foreign business sells into China, the Chinese buyer withholds the VAT and pays it on its own return dates, unless the foreign seller appoints a domestic agent to file and pay for it. Corporate income tax, individual income tax, stamp duty and social insurance are outside this calendar.

“税收征管法及本细则所规定期限的最后一日是法定休假日的,以休假日期满的次日为期限的最后一日;在期限内有连续3日以上法定休假日的,按休假日天数顺延。”
Screenshot of the official source stating the rule that governs China's deadlines
中华人民共和国税收征收管理法实施细则 — 第一百零九条 (Implementing Rules of the Tax Collection and Administration Law, Art. 109) — State Taxation Administration (国家税务总局政策法规库), captured 2026-10-14

What this calendar does not list

  • Not applicable Annual or reconciliation return — China has no annual VAT return or year-end reconciliation: each monthly or quarterly return is final for its period. The VAT Law and its Implementing Regulations (both in force 1 January 2026, checked 2026-10-14) provide none; the only year-based date, for individuals paying per transaction (Regulations Art. 44), is a catch-up filing for occasional sales, not a business return.
  • Not applicable Recapitulative listing — There is no recapitulative statement, sales listing or SAF-T-style file in China. The VAT Law and its Implementing Regulations (checked 2026-10-14) provide none; invoice data reaches the tax authority through the national e-fapiao platform as invoices are issued.
  • Not applicable E-invoicing / e-reporting cycle — Fully digitalised e-fapiao are issued on the STA's national electronic fapiao platform and their data flows to the tax authority automatically at issue (STA Announcement 2024 No. 11, nationwide from 1 December 2024, checked 2026-10-14), so there is no separate transmission or reporting deadline.

About this calendar

Which China tax deadlines does this calendar cover?

8 recurring indirect-tax obligations — 增值税 (VAT), 消费税 (consumption tax), 增值税、消费税 (import VAT and consumption tax, collected by customs) and All taxes, VAT included (税务登记) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-21). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.