Mexico compliance calendar

12 recurring Impuesto al Valor Agregado (IVA), Impuesto Especial sobre Producción y Servicios (IEPS) and Registro Federal de Contribuyentes (all federal taxes, including IVA) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Mexico rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Report / listing Return filing Payment

Dates already include the weekend and public-holiday shift where Mexico applies one — 9 of 12 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

Declaración de pago definitivo mensual de IVA — monthly IVA return and payment

Impuesto al Valor Agregado (IVA) · Monthly · return filing

17th of the month after the month ends Verified 2026-10-14
Who files
Every IVA taxpayer, companies and individuals alike (RESICO included) — there is no registration threshold; one return covers all of a taxpayer's establishments
Notes
File and pay each month's IVA by the 17th of the next month; the monthly payment is final, with no year-end top-up. IVA you withheld from suppliers — for example on professional services or rent paid to individuals — is paid over on this same return, and IVA withheld from you reduces it. The December 2026 return is due Monday 18 January 2027 because the 17th is a Sunday. Depending on the sixth digit of your RFC you may have one to five extra working days, but large taxpayers and anyone filing an audited tax report do not, so plan around the 17th.
Source
Ley del Impuesto al Valor Agregado — artículo 5o.-D, segundo párrafo Cámara de Diputados del H. Congreso de la Unión
See the source text
“Los contribuyentes efectuarán el pago del impuesto mediante declaración que presentarán ante las oficinas autorizadas a más tardar el día 17 del mes siguiente al que corresponda el pago.”
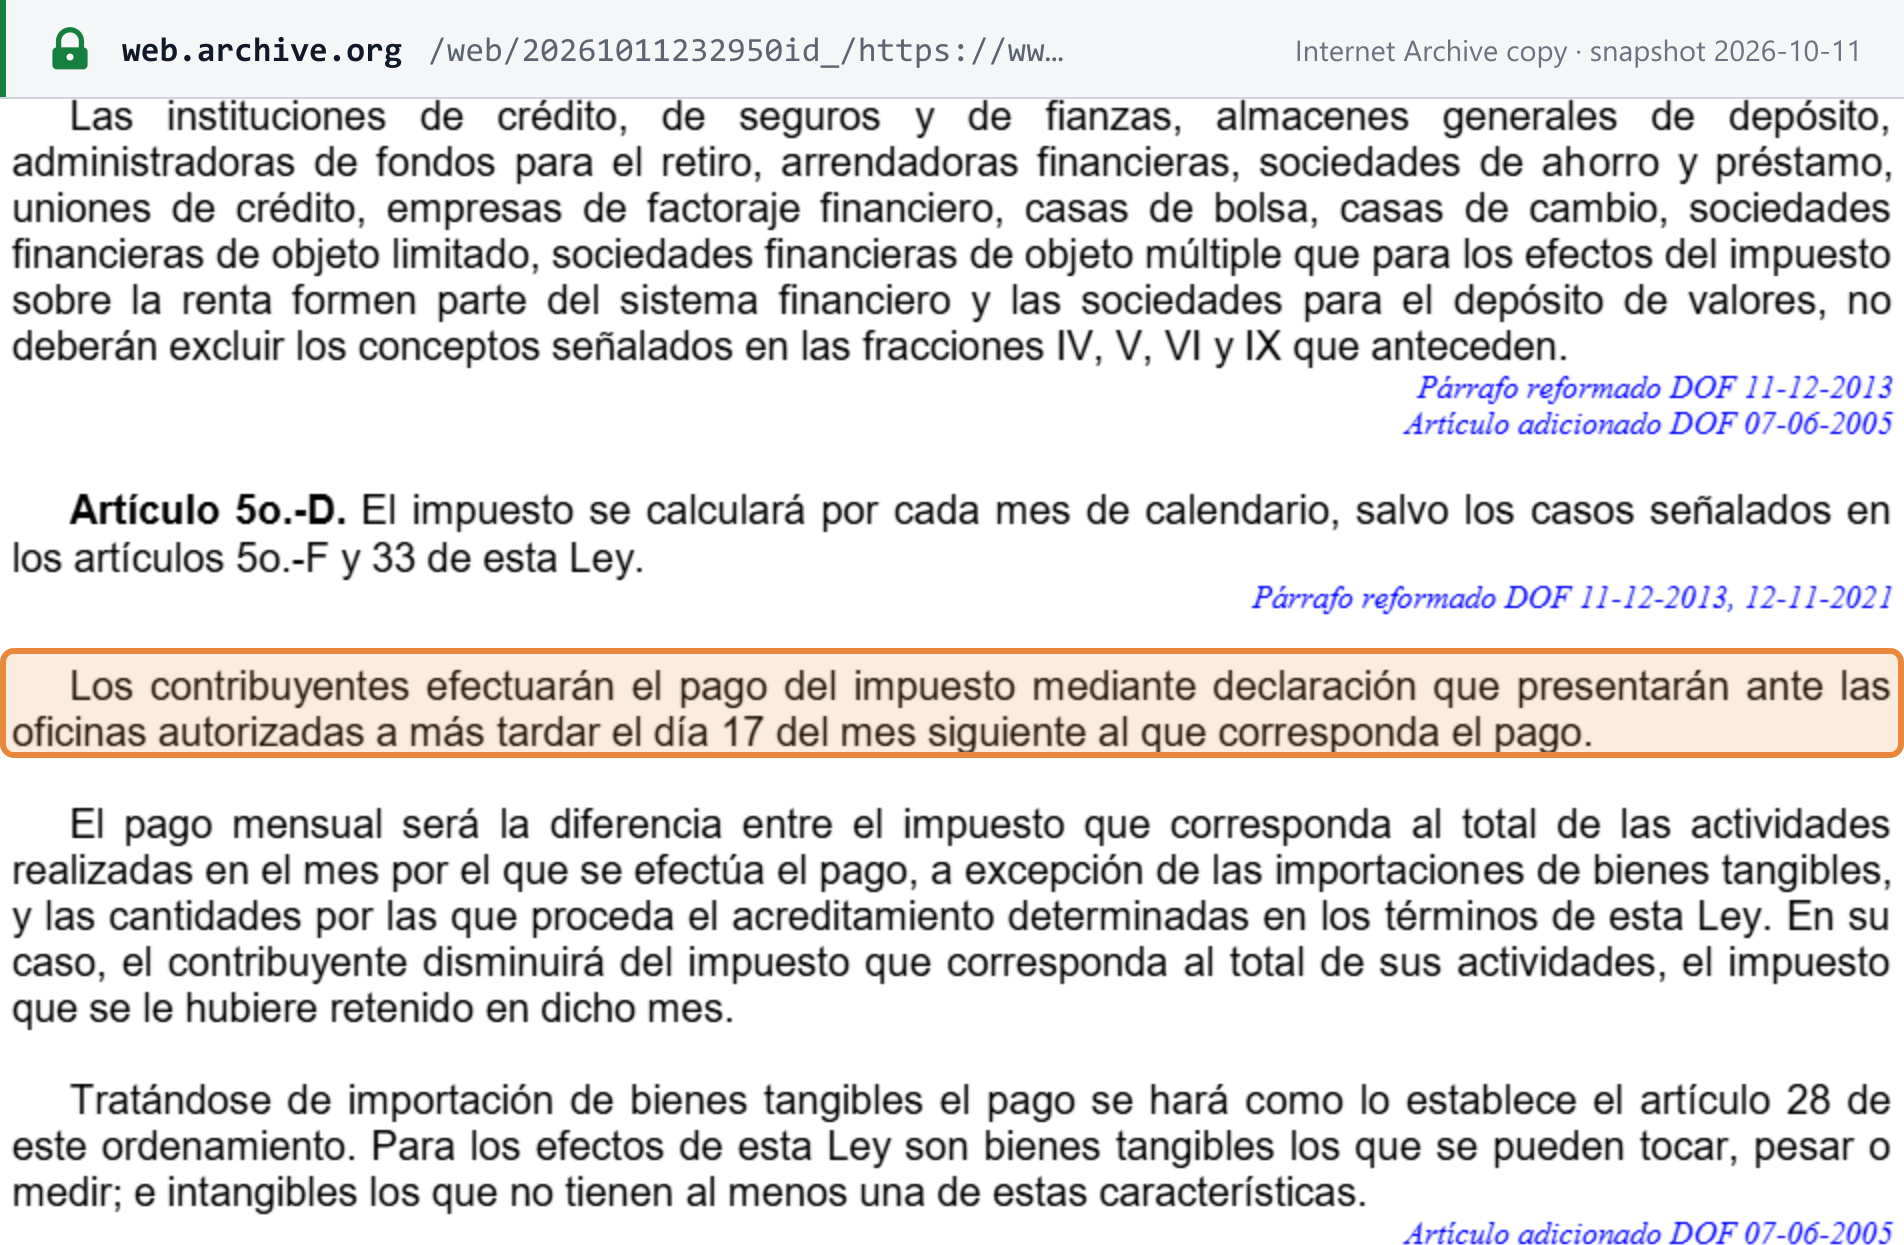
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Declaración de pago definitivo mensual de IVA — monthly IVA return and payment deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Declaración trimestral de IVA — quarterly IVA for small residential landlords (art. 5o.-F)

Impuesto al Valor Agregado (IVA) · Quarterly · return filing

17th of the month after the quarter ends Verified 2026-10-14
Who files
Individuals whose only income is from letting property, below the statutory monthly ceiling, who have opted to make quarterly income-tax payments under LISR art. 116
Notes
A small landlord who pays income tax quarterly also accounts for IVA quarterly instead of monthly — for January–March, April–June, July–September and October–December — and those quarterly payments are final. Each is due on the 17th of the month after the quarter: the third-quarter 2027 return falls on Sunday 17 October and so is due Monday 18 October.
Source
Ley del Impuesto al Valor Agregado — artículo 5o.-F Cámara de Diputados del H. Congreso de la Unión
See the source text
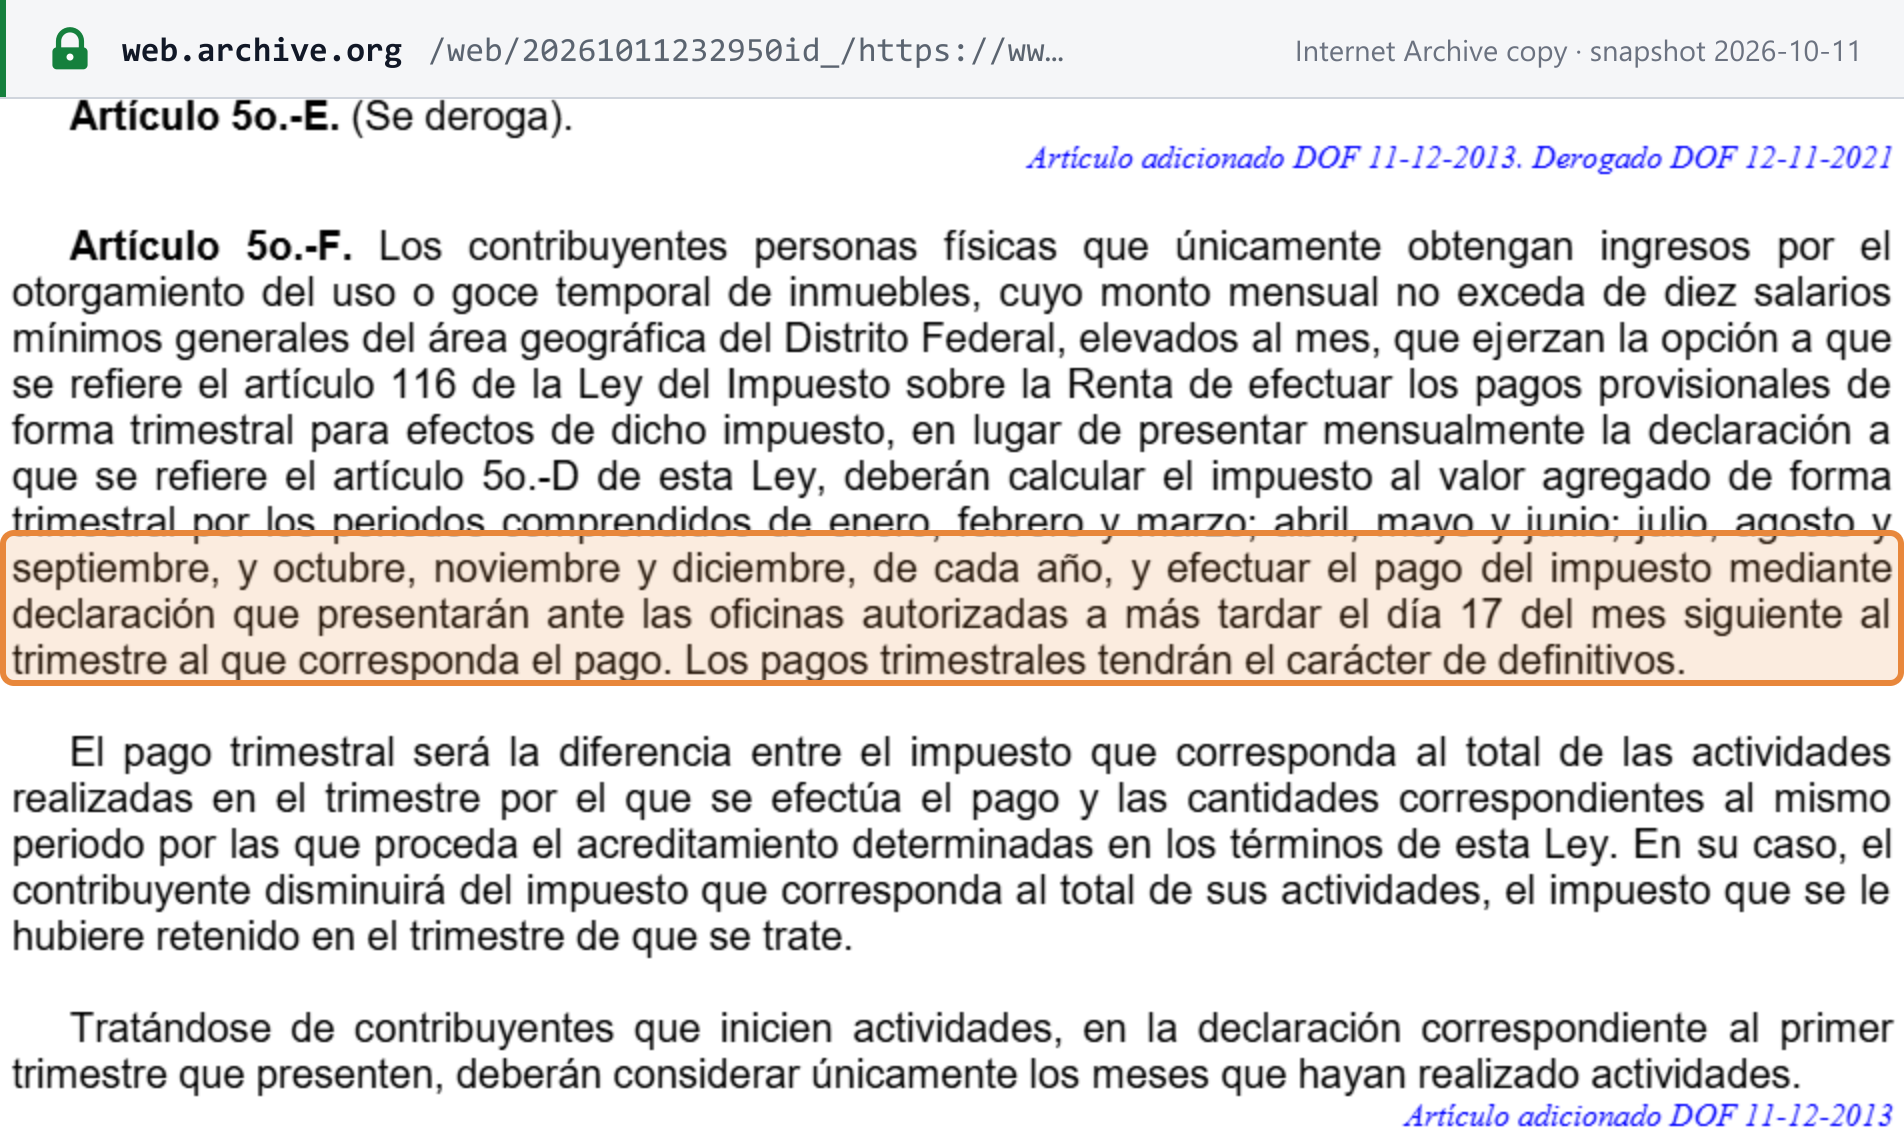
“efectuar el pago del impuesto mediante declaración que presentarán ante las oficinas autorizadas a más tardar el día 17 del mes siguiente al trimestre al que corresponda el pago.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Declaración trimestral de IVA — quarterly IVA for small residential landlords (art. 5o.-F) deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
DIOT — Declaración Informativa de Operaciones con Terceros

Impuesto al Valor Agregado (IVA) · Monthly · report / listing

last day of the month after the month ends Verified 2026-10-14
Who files
IVA taxpayers, companies and individuals, except RESICO taxpayers and individuals in the business and professional, digital-platform or letting regimes whose income for the previous year did not exceed MXN 4,000,000 (or who start trading expecting to stay under it), who are relieved of it
Notes
Each month you report your transactions with suppliers — the IVA paid, withheld, credited and charged, broken down by rate — through the SAT portal. The Ley del IVA still says the 17th, and many calendars repeat it, but the SAT's annual tax rules allow the whole of the following month. RESICO taxpayers, and individuals in business, professional, platform or letting activities with under MXN 4,000,000 of income the year before, do not file it. The extra working days by RFC digit do not apply here. December 2026's report is due Tuesday 2 February 2027: 31 January is a Sunday and Monday 1 February is a public holiday.
Source
Resolución Miscelánea Fiscal para 2026 (DOF 28-12-2025) — regla 4.5.1 Servicio de Administración Tributaria / Diario Oficial de la Federación
See the source text
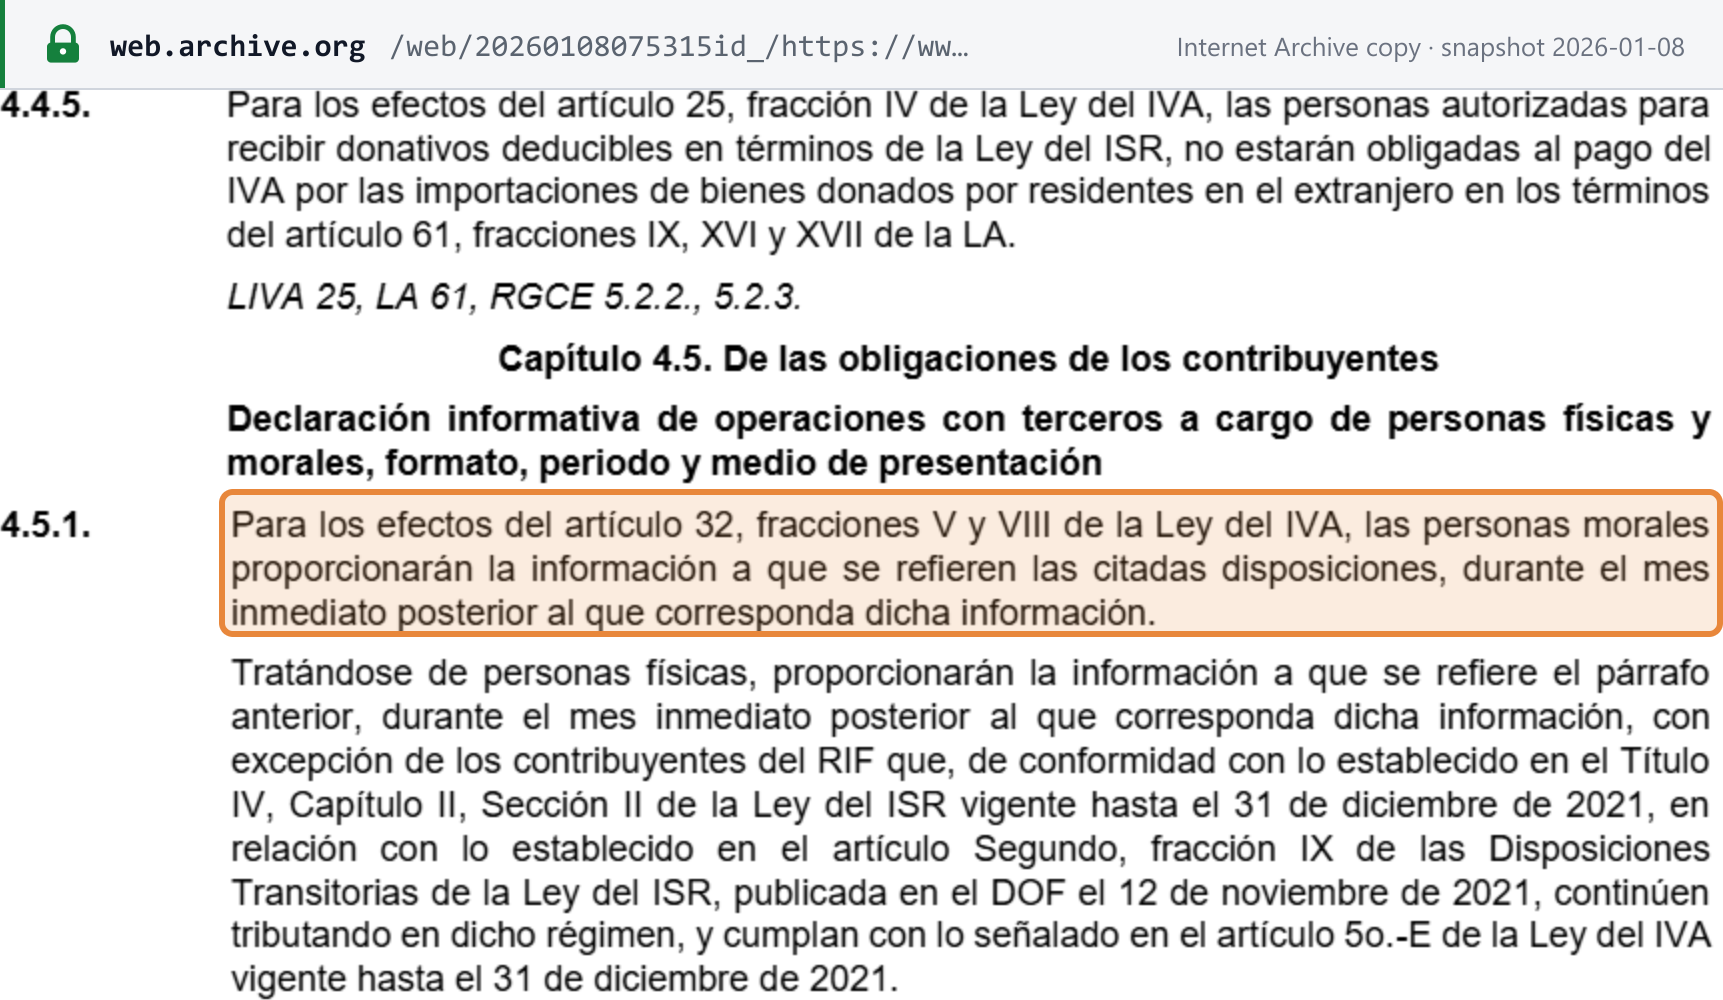
“Para los efectos del artículo 32, fracciones V y VIII de la Ley del IVA, las personas morales proporcionarán la información a que se refieren las citadas disposiciones, durante el mes inmediato posterior al que corresponda dicha información.”
Screenshot of Servicio de Administración Tributaria / Diario Oficial de la Federación showing the DIOT — Declaración Informativa de Operaciones con Terceros deadline Open full size Captured from Servicio de Administración Tributaria / Diario Oficial de la Federación on 2026-10-15

Declaración de pago del IVA por la prestación de servicios digitales — non-resident digital services

Impuesto al Valor Agregado (IVA) — servicios digitales (non-residents) · Monthly · return filing

17th of the month after the month ends Verified 2026-10-14
Who files
Non-residents without a Mexican establishment supplying digital services (downloads and streaming, intermediation platforms, online clubs and dating, distance learning) to recipients in Mexico
Notes
A foreign digital-service supplier charges 16% IVA on what it actually collects from Mexican customers each month and pays it by the 17th of the following month. The monthly count of services, prices and recipients is due the same day and is reported inside the same payment return, so it is one filing. A supplier whose sales all go through a platform that withholds the full IVA does not file. Whether the RFC-digit extension reaches non-residents is not stated anywhere, so treat the 17th as the deadline.
Source
Ley del Impuesto al Valor Agregado — artículo 18-D, fracciones III y IV Cámara de Diputados del H. Congreso de la Unión
See the source text
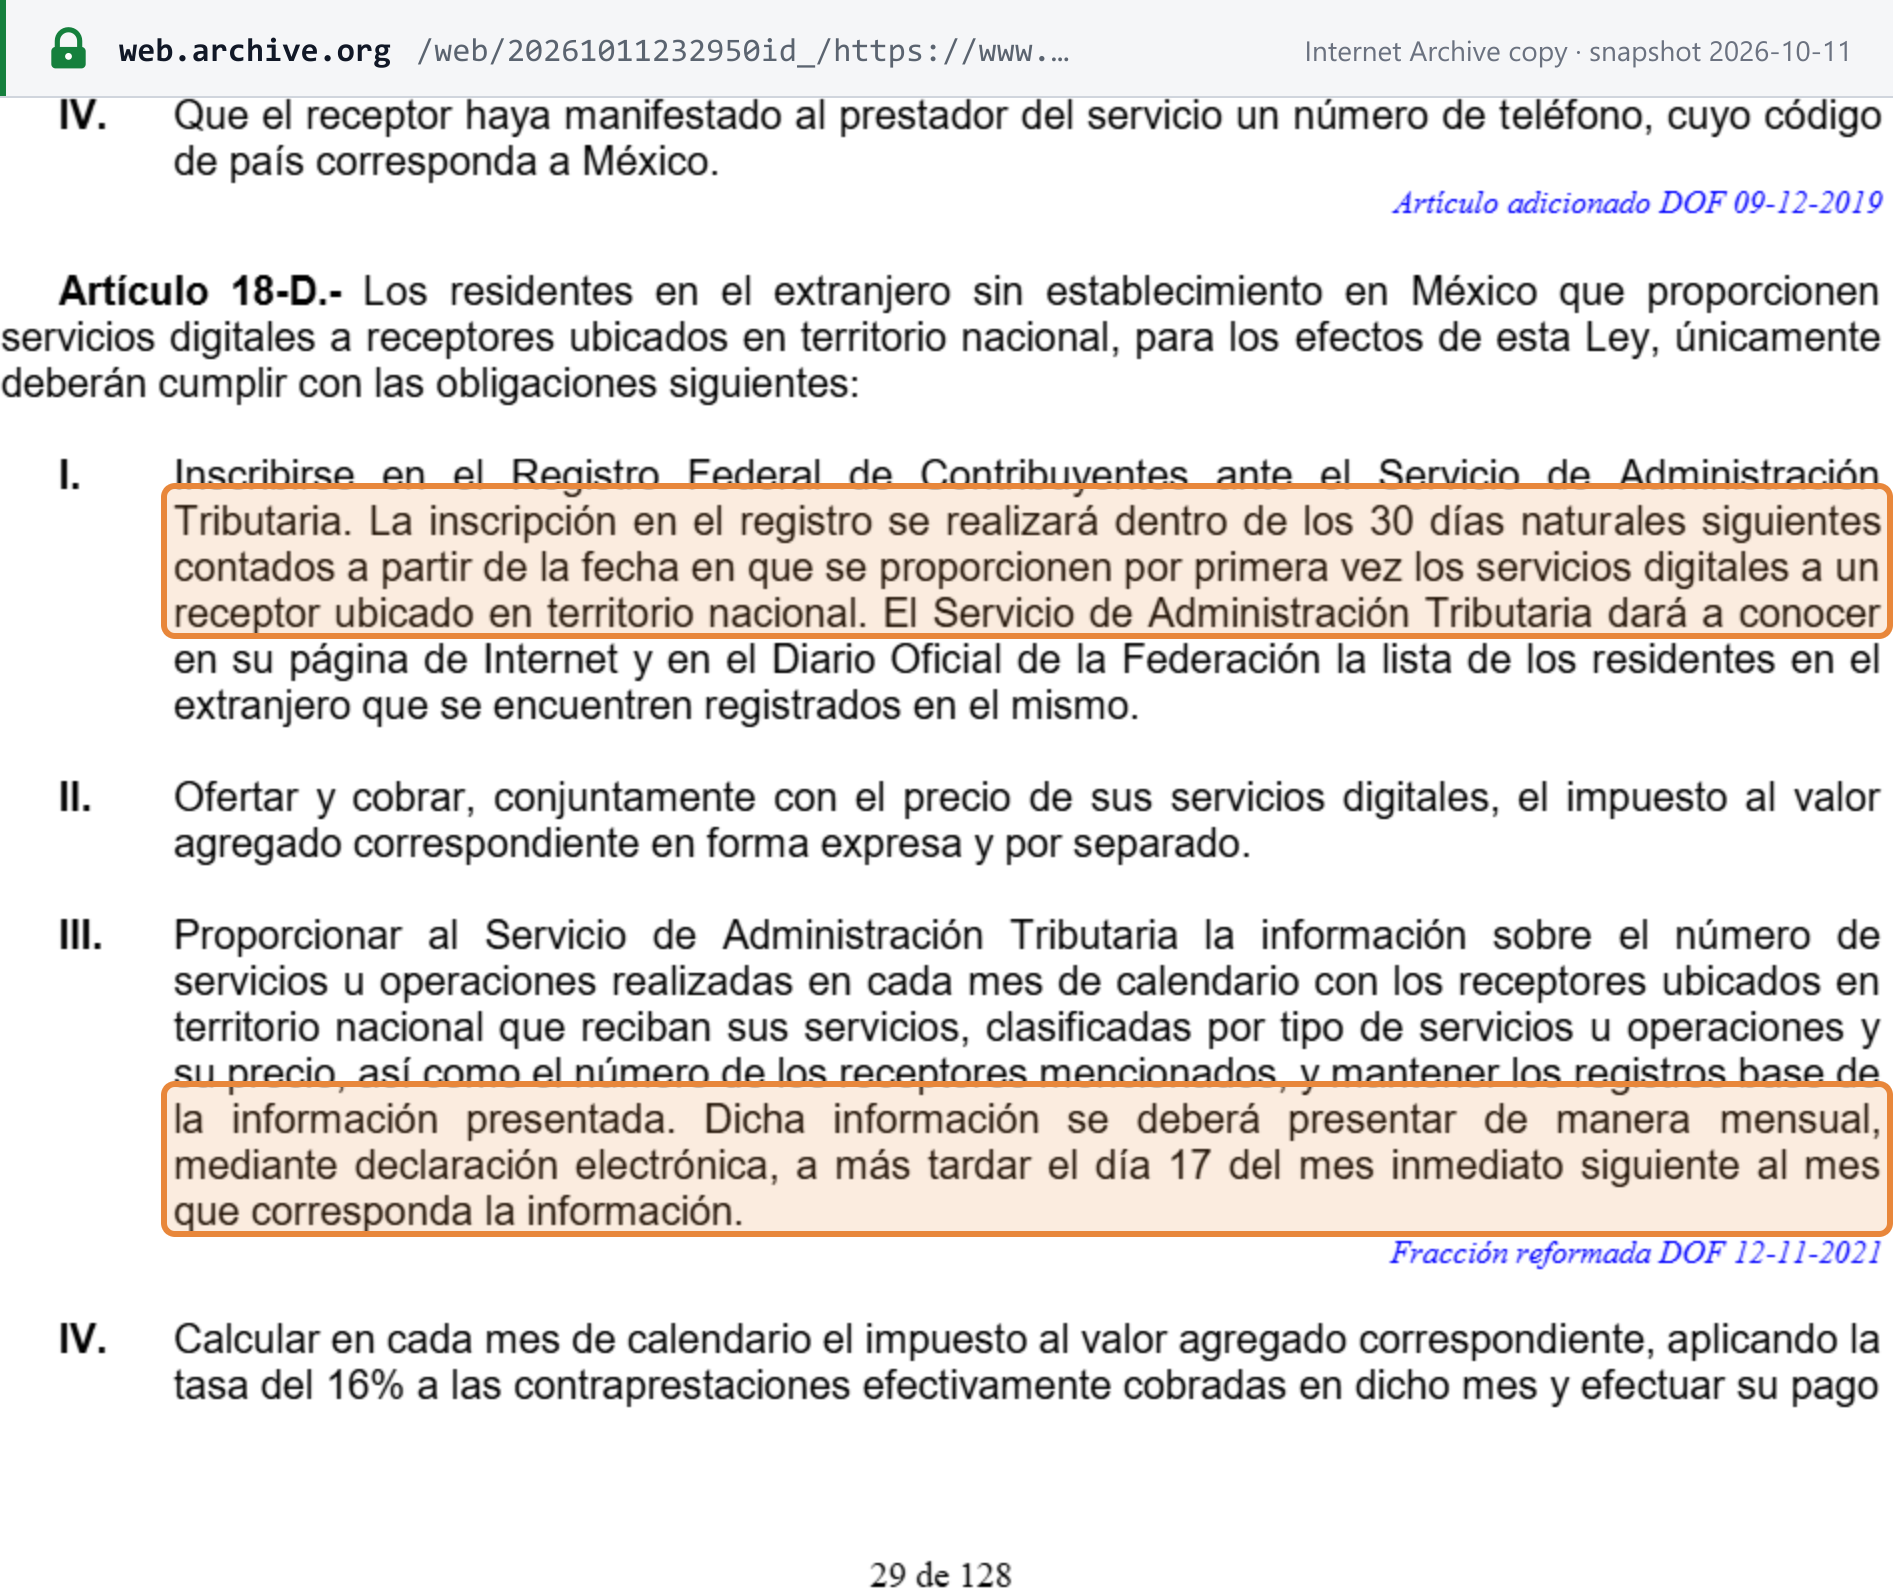
“Dicha información se deberá presentar de manera mensual, mediante declaración electrónica, a más tardar el día 17 del mes inmediato siguiente al mes que corresponda la información.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Declaración de pago del IVA por la prestación de servicios digitales — non-resident digital services deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Entero de retenciones de IVA por plataformas digitales — platform IVA withholding remittance

Impuesto al Valor Agregado (IVA) — retención por plataformas · Monthly · payment

17th of the month after the month ends Verified 2026-10-14
Who files
Digital intermediation platforms, foreign (art. 18-J) and Mexican-resident (art. 1o.-A BIS), that collect the price on behalf of sellers and so must withhold IVA from them
Notes
A platform that collects payment for sellers withholds IVA from them — half the IVA from individuals, all of it where the seller gives no RFC or is a foreign digital supplier — and pays it over by the 17th of the month after withholding. Within five working days after each month it must also issue every individual it withheld from an electronic withholding receipt (CFDI de Retenciones). From 2026 the same timetable applies to IEPS the platform withholds on violent video-game sales.
Source
Ley del Impuesto al Valor Agregado — artículo 18-J, fracción II, inciso b) Cámara de Diputados del H. Congreso de la Unión
See the source text
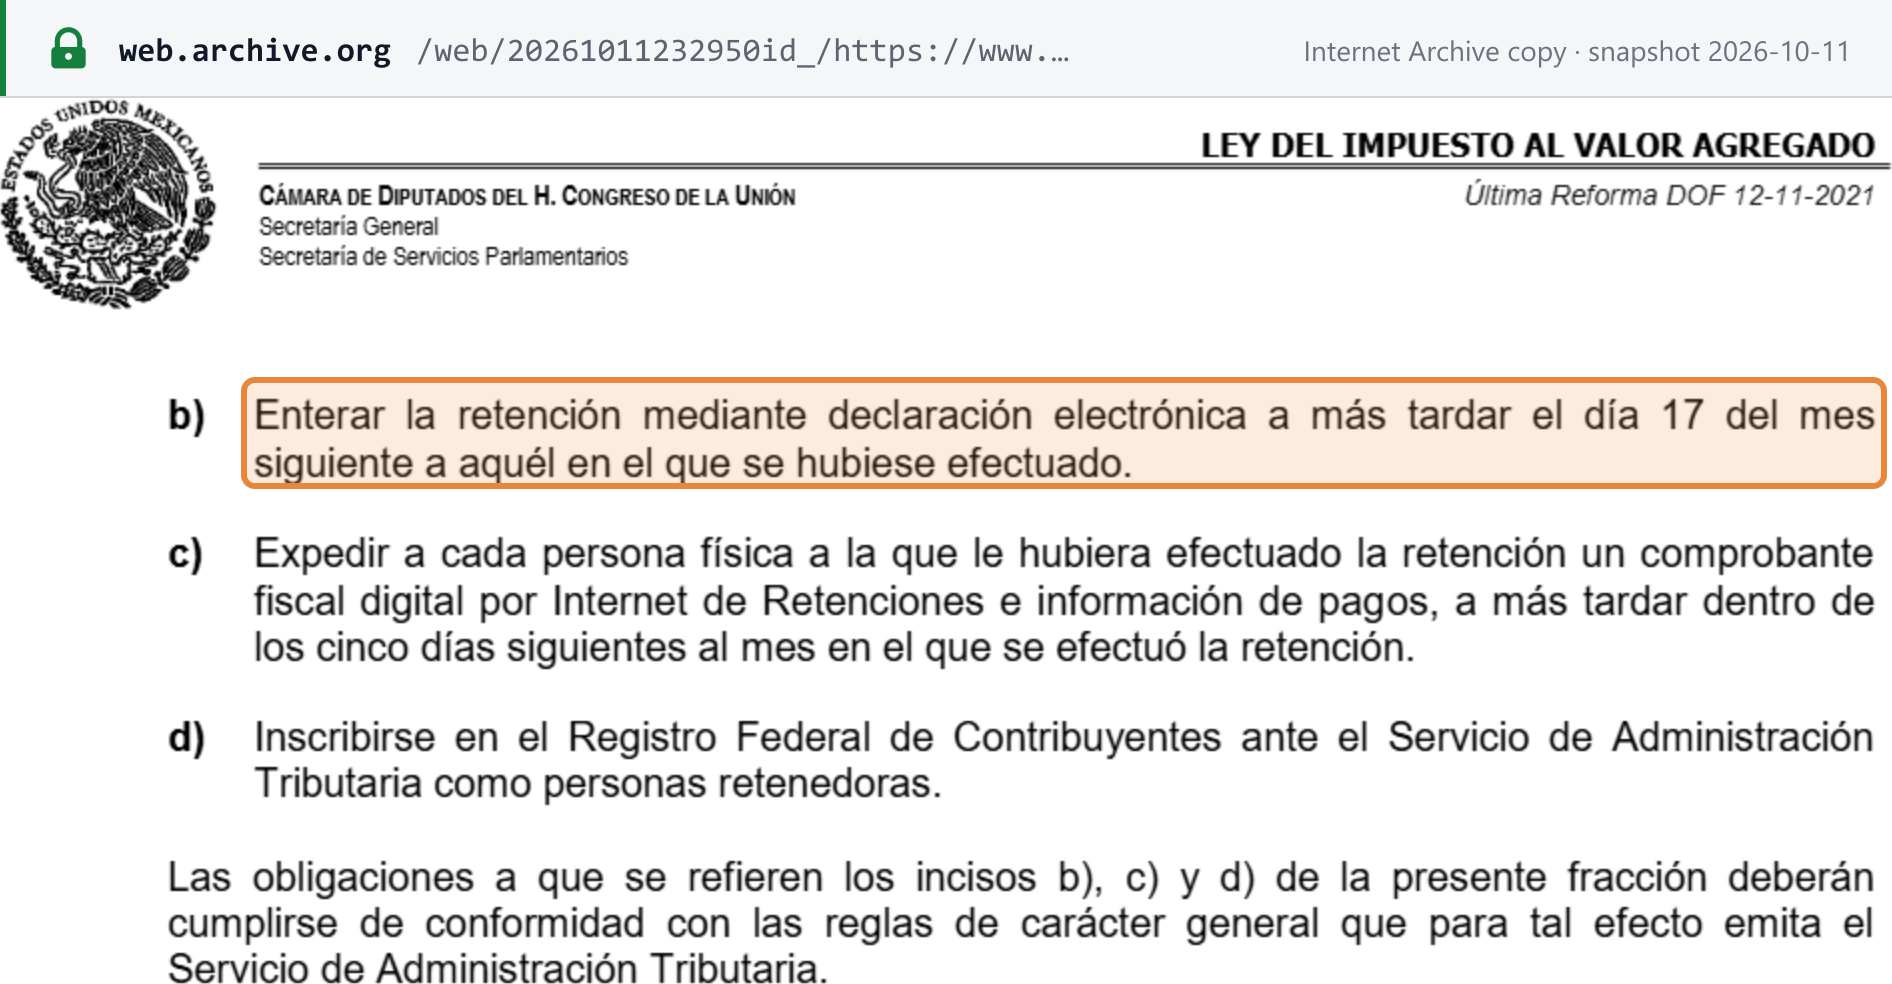
“Enterar la retención mediante declaración electrónica a más tardar el día 17 del mes siguiente a aquél en el que se hubiese efectuado.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Entero de retenciones de IVA por plataformas digitales — platform IVA withholding remittance deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Información de enajenantes y prestadores — platform seller-information return (art. 18-J fr. III)

Impuesto al Valor Agregado (IVA) — plataformas digitales · Monthly · report / listing

10th of the month after the month ends Verified 2026-10-14
Who files
Digital intermediation platforms, foreign and Mexican-resident, for every seller or service provider they intermediate, whether or not the platform collected the price
Notes
Platforms report, seller by seller, the name, RFC, CURP, tax address, bank account and the value of the transactions they intermediated — plus the property address for short-term lodging — by the 10th of the following month, a week before the IVA itself. When the 10th falls on a weekend it moves to Monday: the December 2026 report is due 11 January 2027.
Source
Ley del Impuesto al Valor Agregado — artículo 18-J, fracción III Cámara de Diputados del H. Congreso de la Unión
See the source text
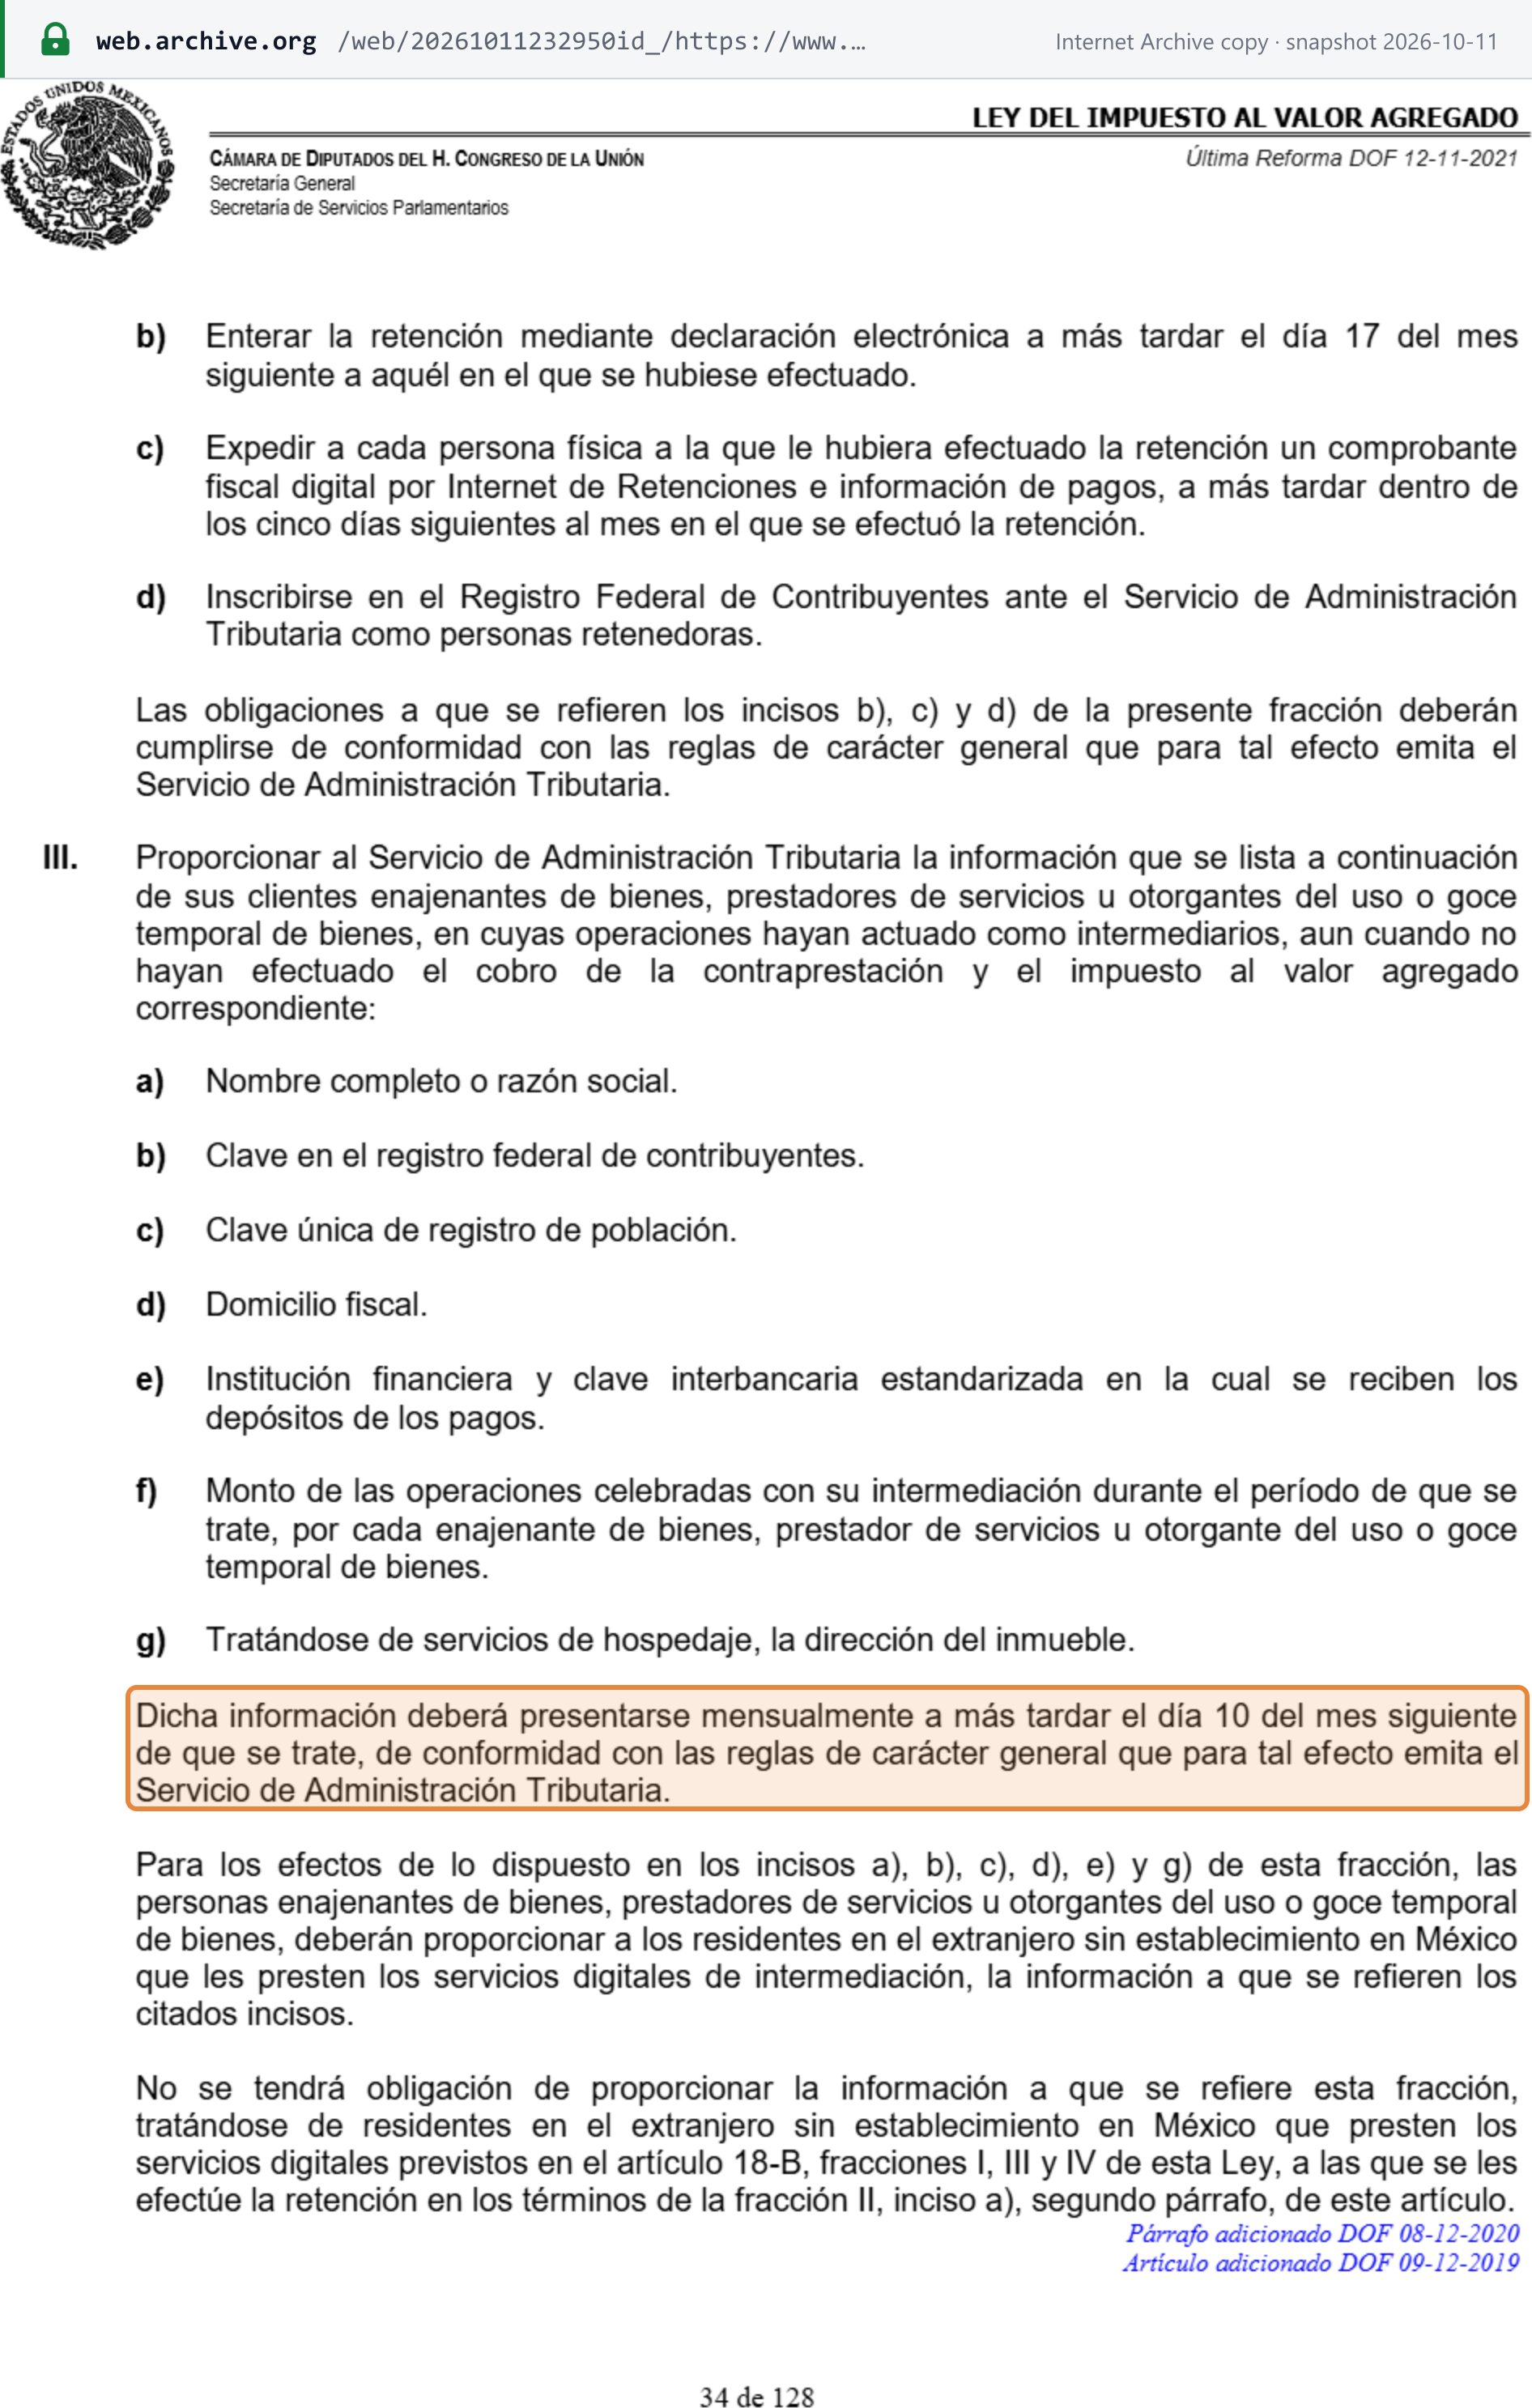
“Dicha información deberá presentarse mensualmente a más tardar el día 10 del mes siguiente de que se trate, de conformidad con las reglas de carácter general que para tal efecto emita el Servicio de Administración Tributaria.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Información de enajenantes y prestadores — platform seller-information return (art. 18-J fr. III) deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Declaración de pago definitivo mensual de IEPS — monthly excise (IEPS) return and payment

Impuesto Especial sobre Producción y Servicios (IEPS) · Monthly · return filing

17th of the month after the month ends Verified 2026-10-14
Who files
Producers, importers and sellers liable to IEPS — alcohol, beer, tobacco, fuels, sugary drinks, high-calorie foods, pesticides, gambling, telecommunications and, from 2026, violent or adult video games
Notes
IEPS is Mexico's excise tax and runs on the same day as IVA: calculated per month, paid by the 17th of the next month, and each month's payment is final. Imports are the exception, with the tax paid at customs. For June 2027 the 17th falls on a Saturday, so that payment is due Monday 19 July. Producers of tobacco, alcohol and fuels also owe separate product-specific information returns not shown here.
Source
Ley del Impuesto Especial sobre Producción y Servicios — artículo 5o., primer párrafo Cámara de Diputados del H. Congreso de la Unión
See the source text
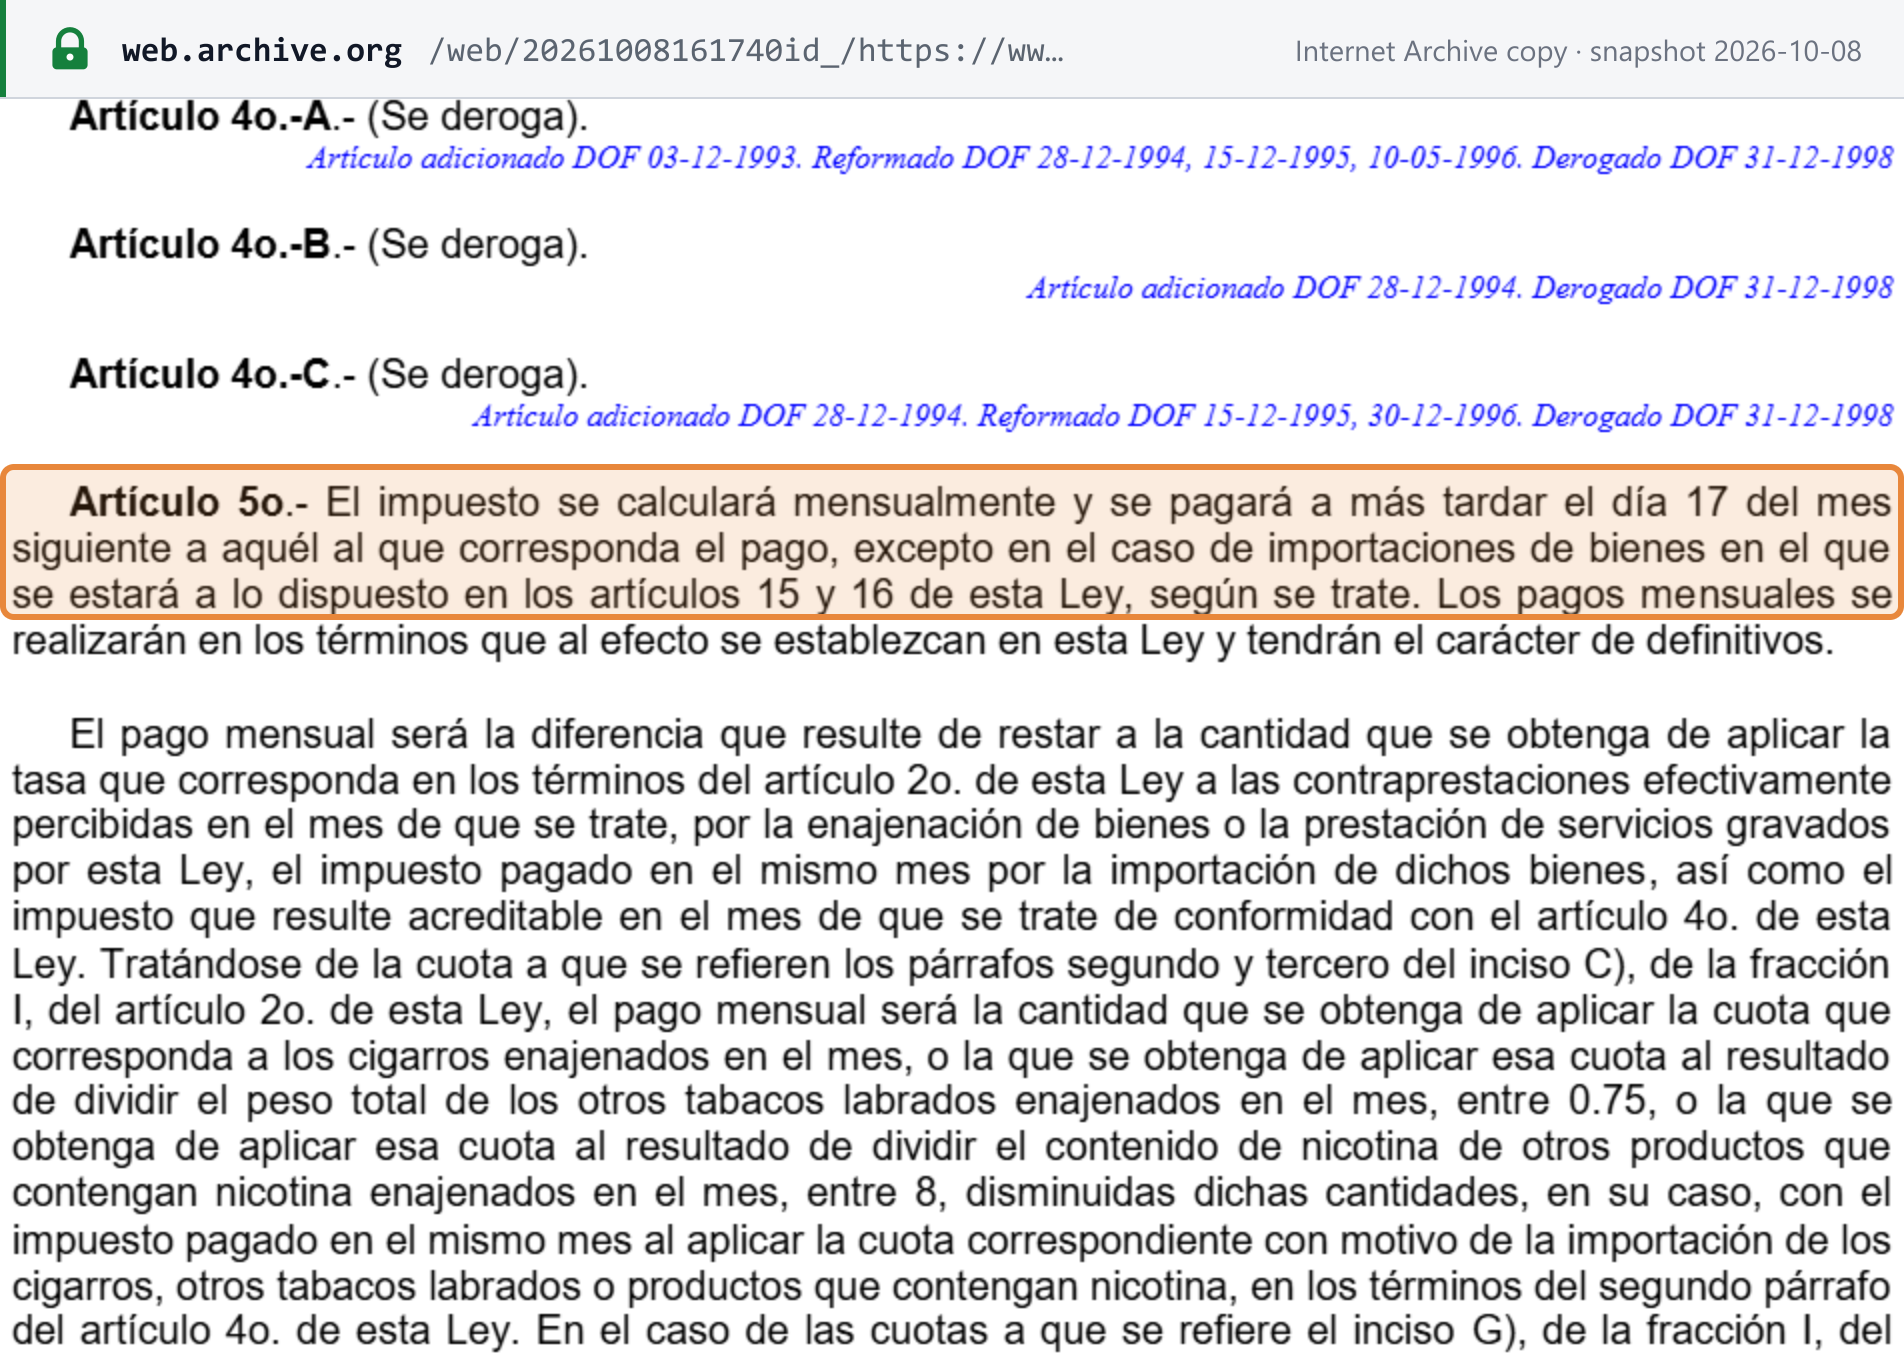
“El impuesto se calculará mensualmente y se pagará a más tardar el día 17 del mes siguiente a aquél al que corresponda el pago, excepto en el caso de importaciones de bienes en el que se estará a lo dispuesto en los artículos 15 y 16 de esta Ley, según se trate.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Declaración de pago definitivo mensual de IEPS — monthly excise (IEPS) return and payment deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
IEPS por servicios digitales — non-resident digital services (video games, online betting)

Impuesto Especial sobre Producción y Servicios (IEPS) — servicios digitales · Monthly · return filing

17th of the month after the month ends Verified 2026-10-14
Who files
Non-residents without a Mexican establishment that give recipients in Mexico access to or downloads of violent or adult video games (8%), and non-resident online betting and sweepstakes operators
Notes
New from 1 January 2026, under the decree published in the Diario Oficial on 7 November 2025. Foreign suppliers of violent or adult video games, and foreign online-betting operators, register in Mexico, charge IEPS in the price and pay what they collected each month by the 17th of the following month; the first payment, for January 2026, was due 17 February 2026. The monthly count of services and customers goes on the same payment return. A video-game supplier selling through a platform that withholds the tax is covered by the platform instead.
Source
Ley del Impuesto Especial sobre Producción y Servicios — artículo 20-A, fracción III, incisos c) y d) Cámara de Diputados del H. Congreso de la Unión
See the source text
“mediante declaración electrónica que presentarán a más tardar el día 17 del mes siguiente de que se trate.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the IEPS por servicios digitales — non-resident digital services (video games, online betting) deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Información de los 50 principales clientes y proveedores (IEPS) — quarterly excise information return

Impuesto Especial sobre Producción y Servicios (IEPS) · Quarterly · report / listing

last day of the month after the quarter ends Verified 2026-10-14
Who files
IEPS taxpayers on the goods in LIEPS art. 2o. fr. I incisos A–D and F–J (alcoholic drinks, beer, tobacco, fuels, flavoured drinks, pesticides, high-calorie foods and the others listed)
Notes
Excise taxpayers on most taxed goods report their 50 largest customers and suppliers for each quarter during the following April, July, October and January, so the last day of that month is the deadline. The fourth-quarter 2026 report is due Tuesday 2 February 2027, because 31 January is a Sunday and 1 February a holiday. Table-wine sellers report half-yearly instead, in January and July.
Source
Ley del Impuesto Especial sobre Producción y Servicios — artículo 19, fracción VIII Cámara de Diputados del H. Congreso de la Unión
See the source text
“deberán proporcionar al Servicio de Administración Tributaria, trimestralmente, en los meses de abril, julio, octubre y enero, del año que corresponda, la información sobre sus 50 principales clientes y proveedores del trimestre inmediato anterior al de su declaración, respecto de dichos bienes.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Información de los 50 principales clientes y proveedores (IEPS) — quarterly excise information return deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Inscripción en el Registro Federal de Contribuyentes (RFC) — tax registration

Registro Federal de Contribuyentes (all federal taxes, including IVA) · One-off · registration

within 1 month of the day you start an activity that requires periodic tax returns Verified 2026-10-14
Who files
Anyone who must file periodic returns or issue electronic invoices — there is no IVA registration threshold; companies formed before a notary are registered through the notary at signing
Notes
Mexico has no turnover threshold: as soon as you start an activity that means filing periodic returns, you must be in the RFC within the following month — counted to the same day of the next month. Companies set up before a notary are registered by the notary when the deed is signed. Changes such as a new tax address, suspension or closure are notified within the month after they happen.
Source
Reglamento del Código Fiscal de la Federación — artículo 23 Cámara de Diputados del H. Congreso de la Unión
See the source text
“En los demás supuestos, la solicitud de inscripción se presentará dentro del mes siguiente al día en que:”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Inscripción en el Registro Federal de Contribuyentes (RFC) — tax registration deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Inscripción en el RFC — non-resident digital-service providers

Impuesto al Valor Agregado (IVA) — servicios digitales (non-residents) · One-off · registration

within 30 days of first supplying a digital service to a recipient in Mexico Verified 2026-10-14
Who files
Non-residents without a Mexican establishment that start supplying digital services to recipients in Mexico — including, for IEPS, suppliers of violent or adult video games and online betting, whose registration follows the same 30-day rule (LIEPS art. 20-A fr. III a)
Notes
A foreign digital supplier — including a video-game or online-betting operator liable to IEPS — has 30 calendar days from its first sale to a customer in Mexico to register with the SAT, naming a legal representative and a Mexican address for notices and obtaining an e.firma. The SAT publishes the list of registered foreign suppliers, and one that fails to register can have its service blocked in Mexico.
Source
Ley del Impuesto al Valor Agregado — artículo 18-D, fracción I Cámara de Diputados del H. Congreso de la Unión
See the source text
“La inscripción en el registro se realizará dentro de los 30 días naturales siguientes contados a partir de la fecha en que se proporcionen por primera vez los servicios digitales a un receptor ubicado en territorio nacional.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Inscripción en el RFC — non-resident digital-service providers deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Aviso de retenedor de IVA — notice of regular IVA withholding

Impuesto al Valor Agregado (IVA) — retenciones · One-off · registration

within 30 business days of your first regular IVA withholding Verified 2026-10-14
Who files
Businesses that regularly withhold IVA under LIVA art. 1o.-A or 3o. — typically companies paying individuals for professional services or rent, buying waste or scrap, using freight transport or commission agents, and anyone buying or renting goods from non-residents without a Mexican establishment
Notes
Once withholding IVA becomes a regular part of your business, notify the SAT within 30 working days of the first withholding — about six weeks, since the law counts only working days. The withheld IVA itself is paid over with your monthly return.
Source
Ley del Impuesto al Valor Agregado — artículo 32, fracción VI Cámara de Diputados del H. Congreso de la Unión
See the source text
“Las personas que efectúen de manera regular las retenciones a que se refieren los artículos 1o.-A y 3o., tercer párrafo de esta Ley, presentarán aviso de ello ante las autoridades fiscales dentro de los 30 días siguientes a la primera retención efectuada.”
Screenshot of Cámara de Diputados del H. Congreso de la Unión showing the Aviso de retenedor de IVA — notice of regular IVA withholding deadline Open full size Captured from Cámara de Diputados del H. Congreso de la Unión on 2026-10-15
Mexican IVA is calculated month by month and is final each month: the return and the payment are one filing, due on the 17th of the following month, and there is no annual IVA return. When a deadline falls on a Saturday, Sunday or one of the public holidays listed in the Código Fiscal de la Federación (which, unlike the labour-law list, includes 5 May), it moves to the next working day. Many taxpayers get one to five extra working days after the 17th depending on the sixth digit of their RFC; large taxpayers and some others do not, so the 17th shown here is the safe date for everyone. The law also lets a payment made at an authorised bank on a Friday deadline wait until the next working day; this calendar shows the Friday. The monthly DIOT report on supplier transactions runs to the end of the following month. IEPS, the excise tax, sits on the same day-17 grid. IVA on imports is paid with the customs entry, not on a return. Electronic invoices (CFDI) are validated one by one when issued, so there is no periodic e-invoice filing.

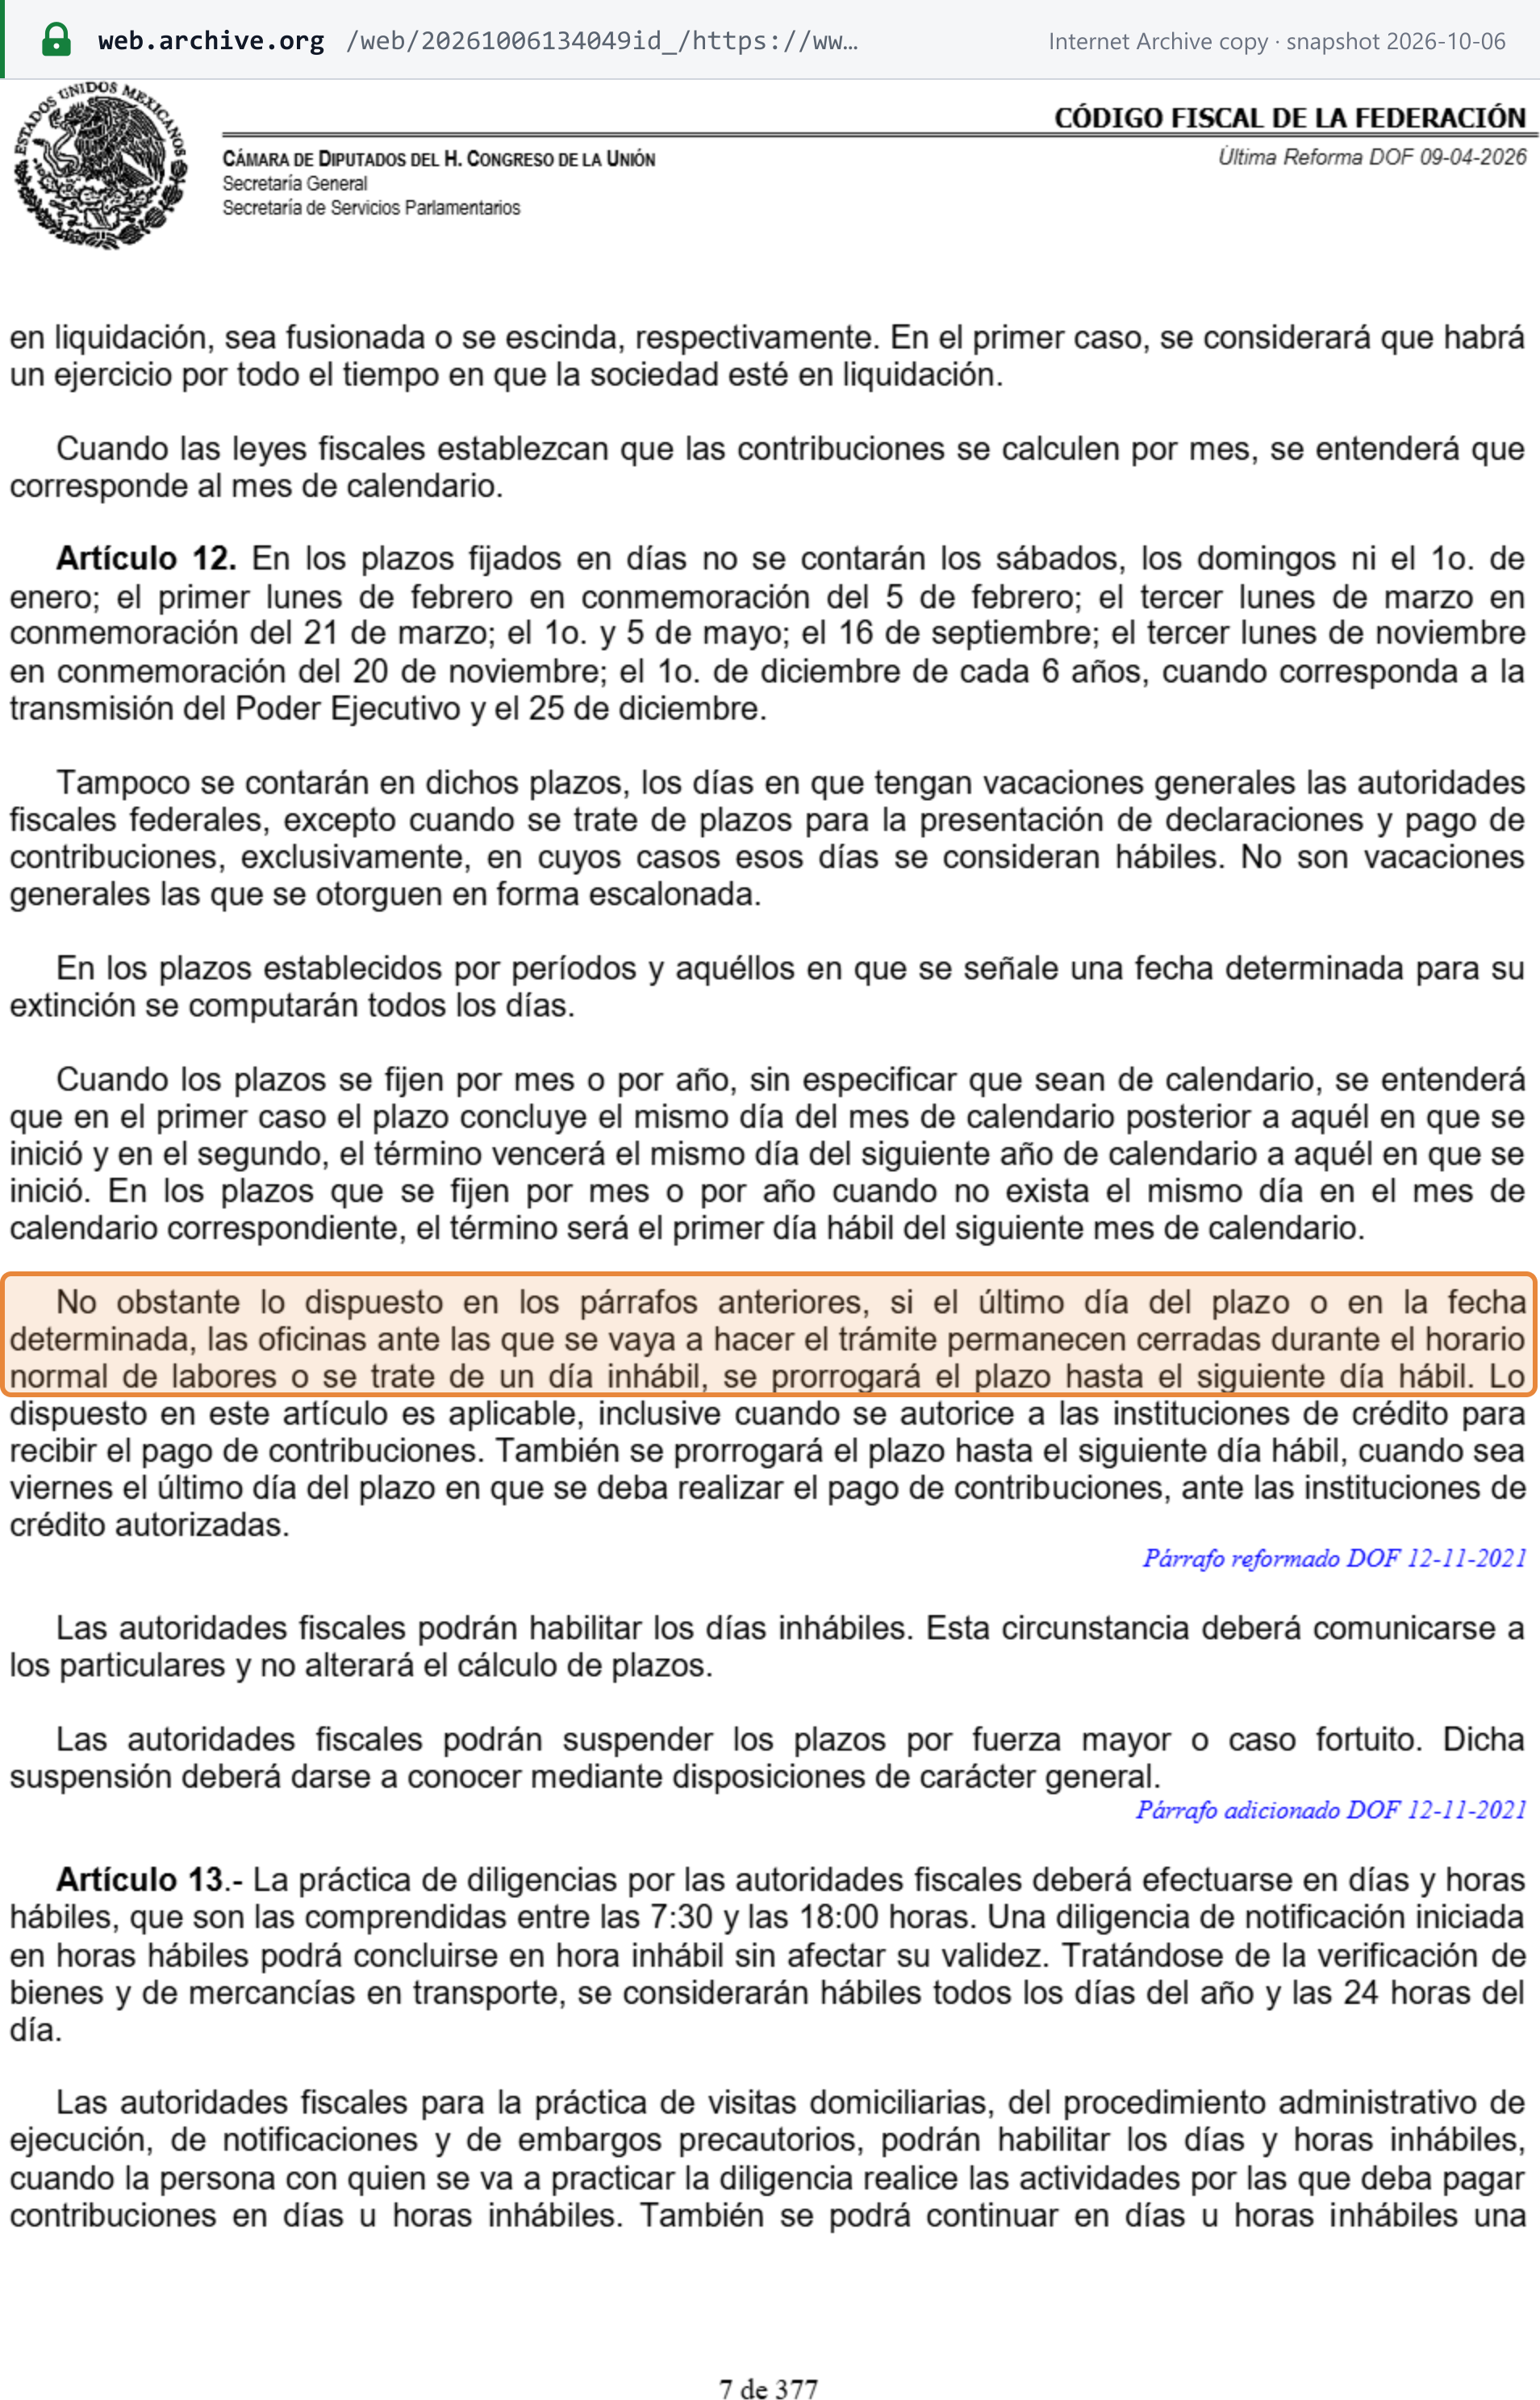
“No obstante lo dispuesto en los párrafos anteriores, si el último día del plazo o en la fecha determinada, las oficinas ante las que se vaya a hacer el trámite permanecen cerradas durante el horario normal de labores o se trate de un día inhábil, se prorrogará el plazo hasta el siguiente día hábil.”
Screenshot of the official source stating the rule that governs Mexico's deadlines
Código Fiscal de la Federación — artículo 12, quinto párrafo — Cámara de Diputados del H. Congreso de la Unión, captured 2026-10-15

What this calendar does not list

  • Not applicable Annual or reconciliation return — The Ley del IVA (Cámara de Diputados text, last reform DOF 12-11-2021) calculates IVA per calendar month — "El impuesto se calculará por cada mes de calendario, salvo los casos señalados en los artículos 5o.-F y 33 de esta Ley" (art. 5o.-D) — and monthly payments are final; the law contains no annual IVA return in force (searched for "declaración del ejercicio" and "declaración anual": only historical transitory provisions). Checked 2026-10-14.
  • Not applicable E-invoicing / e-reporting cycle — Every CFDI is validated and sealed by the SAT or an authorised certification provider before it is issued (CFF art. 29 fr. IV), so there is no separate periodic e-invoice submission. The only period-based CFDI timing is the optional global CFDI for sales to the general public, which may be sent within 24 hours after the close of the daily, weekly, monthly or two-monthly period the taxpayer chooses (RMF 2026 rule 2.7.1.21); being optional and taxpayer-chosen it fixes no common filing cycle. Checked 2026-10-14.

About this calendar

Which Mexico tax deadlines does this calendar cover?

12 recurring indirect-tax obligations — Impuesto al Valor Agregado (IVA), Impuesto Especial sobre Producción y Servicios (IEPS) and Registro Federal de Contribuyentes (all federal taxes, including IVA) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-14). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.