Philippines compliance calendar

9 recurring Value-added tax (VAT) and Percentage tax obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Philippines rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Return filing Law change takes effect

Dates already include the weekend and public-holiday shift where Philippines applies one — 6 of 9 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

BIR Form 2550Q — Quarterly Value-Added Tax Return (calendar quarters)

Value-added tax (VAT) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-15
Who files
VAT-registered persons whose taxable year is the calendar year, or whose fiscal year ends in March, June or September — and anyone required to register for VAT (sales above PHP 3,000,000 in 12 months) who has not.
Notes
Return and VAT payment are both due by the 25th of the month after each quarter ends: 25 April, July, October and January. File it every quarter while the VAT registration stands, even with no sales at all. The quarterly Summary List of Sales and Purchases is a separate submission and its deadline is not shown here. Filing a monthly 2550M is optional and carries no deadline; it does not replace this return.
Source
Guidelines and Instructions for BIR Form No. 2550Q (April 2024 ENCS) — When and Where to File and Pay Bureau of Internal Revenue (BIR)
See the source text
“The return shall be filed within twenty-five (25) days following the close of each taxable quarter.”
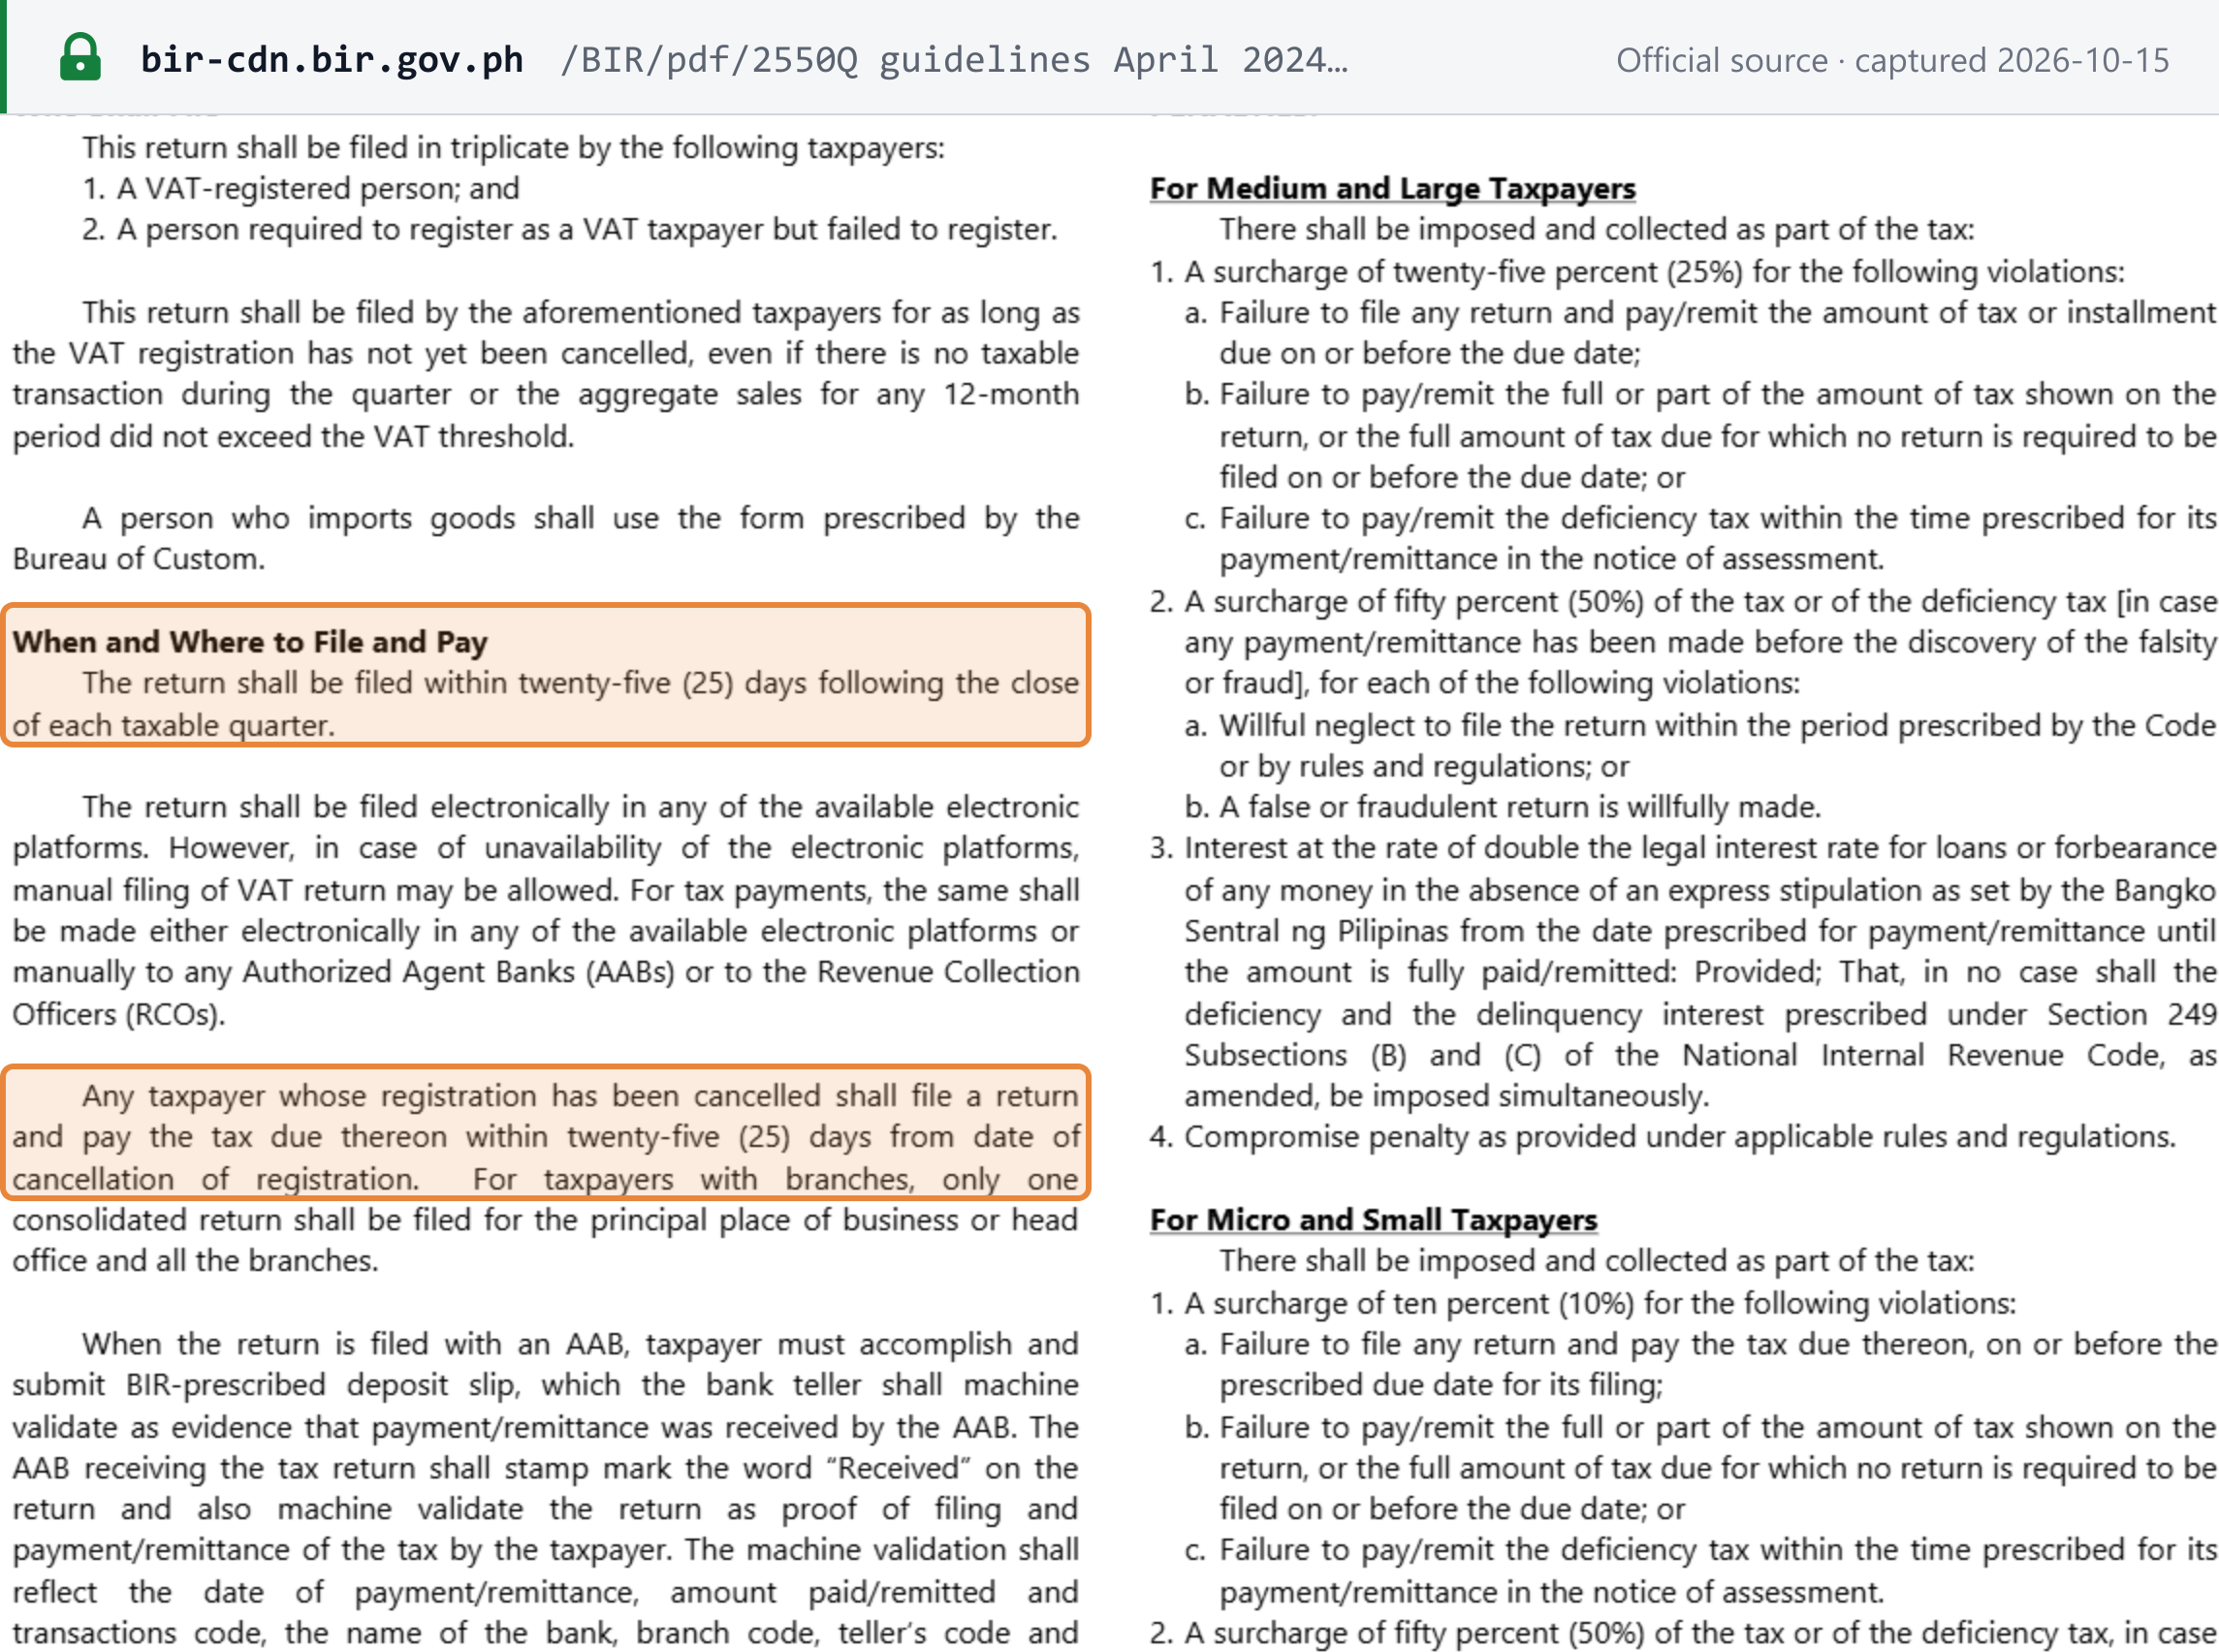
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR Form 2550Q — Quarterly Value-Added Tax Return (calendar quarters) deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
BIR Form 2550Q — fiscal quarters ending January, April, July and October

Value-added tax (VAT) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-15
Who files
VAT-registered persons on a fiscal year ending in January, April, July or October, whose taxable quarters therefore close in those months.
Notes
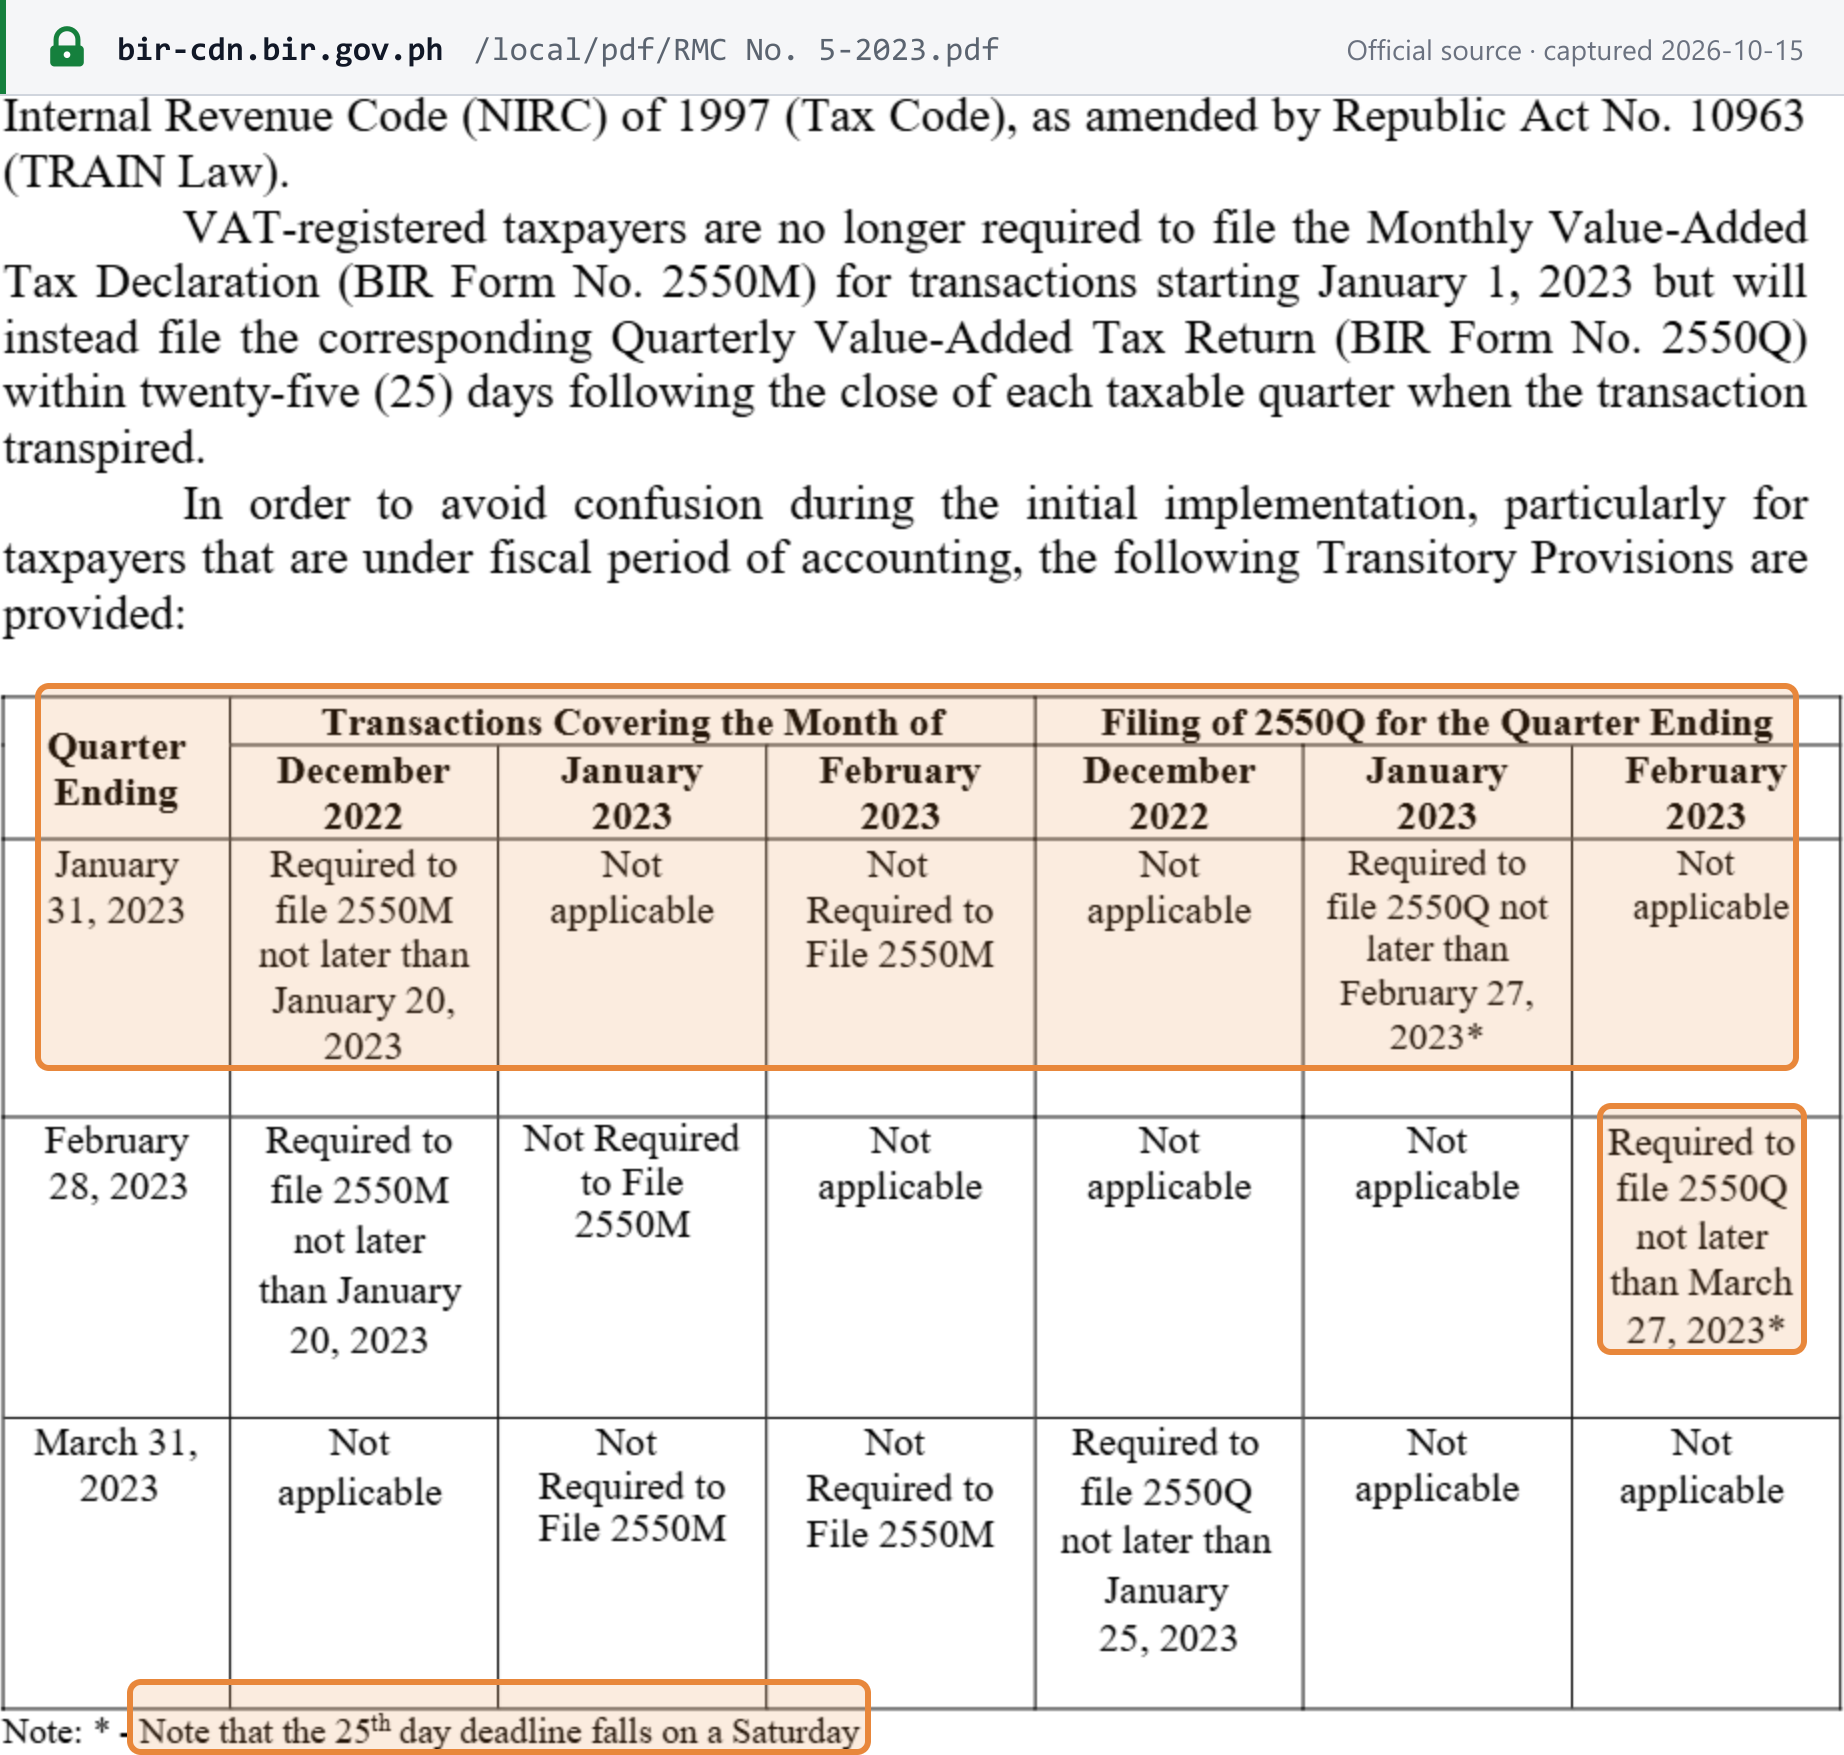
For a business whose fiscal year ends in January, April, July or October, the VAT quarter is its own fiscal quarter, so the 2550Q and payment fall due on 25 February, May, August and November. The BIR's 2023 transition table shows exactly this: a quarter ending 31 January 2023 was due on 27 February 2023, the 25th being a Saturday. A nil return is still required in a quarter without sales.
Source
Revenue Memorandum Circular No. 5-2023 (BIR digest) — transitory provisions for quarterly VAT filing, including fiscal-period taxpayers Bureau of Internal Revenue (BIR)
See the source text
“Required to file 2550Q not later than February 27, 2023*”
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR Form 2550Q — fiscal quarters ending January, April, July and October deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
BIR Form 2550Q — fiscal quarters ending February, May, August and November

Value-added tax (VAT) · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-15
Who files
VAT-registered persons on a fiscal year ending in February, May, August or November, whose taxable quarters therefore close in those months.
Notes
For a fiscal year ending in February, May, August or November, returns and payment fall due on 25 March, June, September and December. Holidays bite this group hardest: the quarter ending November 2026 is due Monday 28 December 2026 because Christmas falls on the 25th, and the quarter ending February 2027 is due Monday 29 March 2027, after Holy Week. In 2023 the BIR moved this cohort's Saturday 25 March deadline to the 27th. File the quarterly return even when there were no sales.
Source
Revenue Memorandum Circular No. 5-2023 (BIR digest) — transitory provisions for quarterly VAT filing, including fiscal-period taxpayers Bureau of Internal Revenue (BIR)
See the source text
“Note that the 25th day deadline falls on a Saturday”
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR Form 2550Q — fiscal quarters ending February, May, August and November deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
BIR Form 2550-DS — Quarterly VAT Return of nonresident digital service providers (VDS Portal)

Value-added tax (VAT) on digital services · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-15
Who files
Nonresident digital service providers (NRDSPs) registered for VAT, including nonresident e-marketplaces: they report B2B and B2C sales of digital services consumed in the Philippines, and pay the 12% VAT on B2C sales.
Notes
Filed through the BIR's VAT on Digital Services (VDS) Portal by the 25th of the month after each calendar quarter, with B2C VAT paid by the same date. A provider selling only to businesses still files, to report those sales; the Philippine business customer withholds and remits that VAT itself on the 1600-VT. Paying monthly is allowed, but the quarterly return is still owed. Under RR 14-2025, nonresident providers had to register by 1 June 2025 and owe VAT on sales from 2 June 2025.
Source
Revenue Regulations No. 3-2025 (BIR digest), Section 6(B)(2) — business-to-consumer transactions Bureau of Internal Revenue (BIR)
See the source text
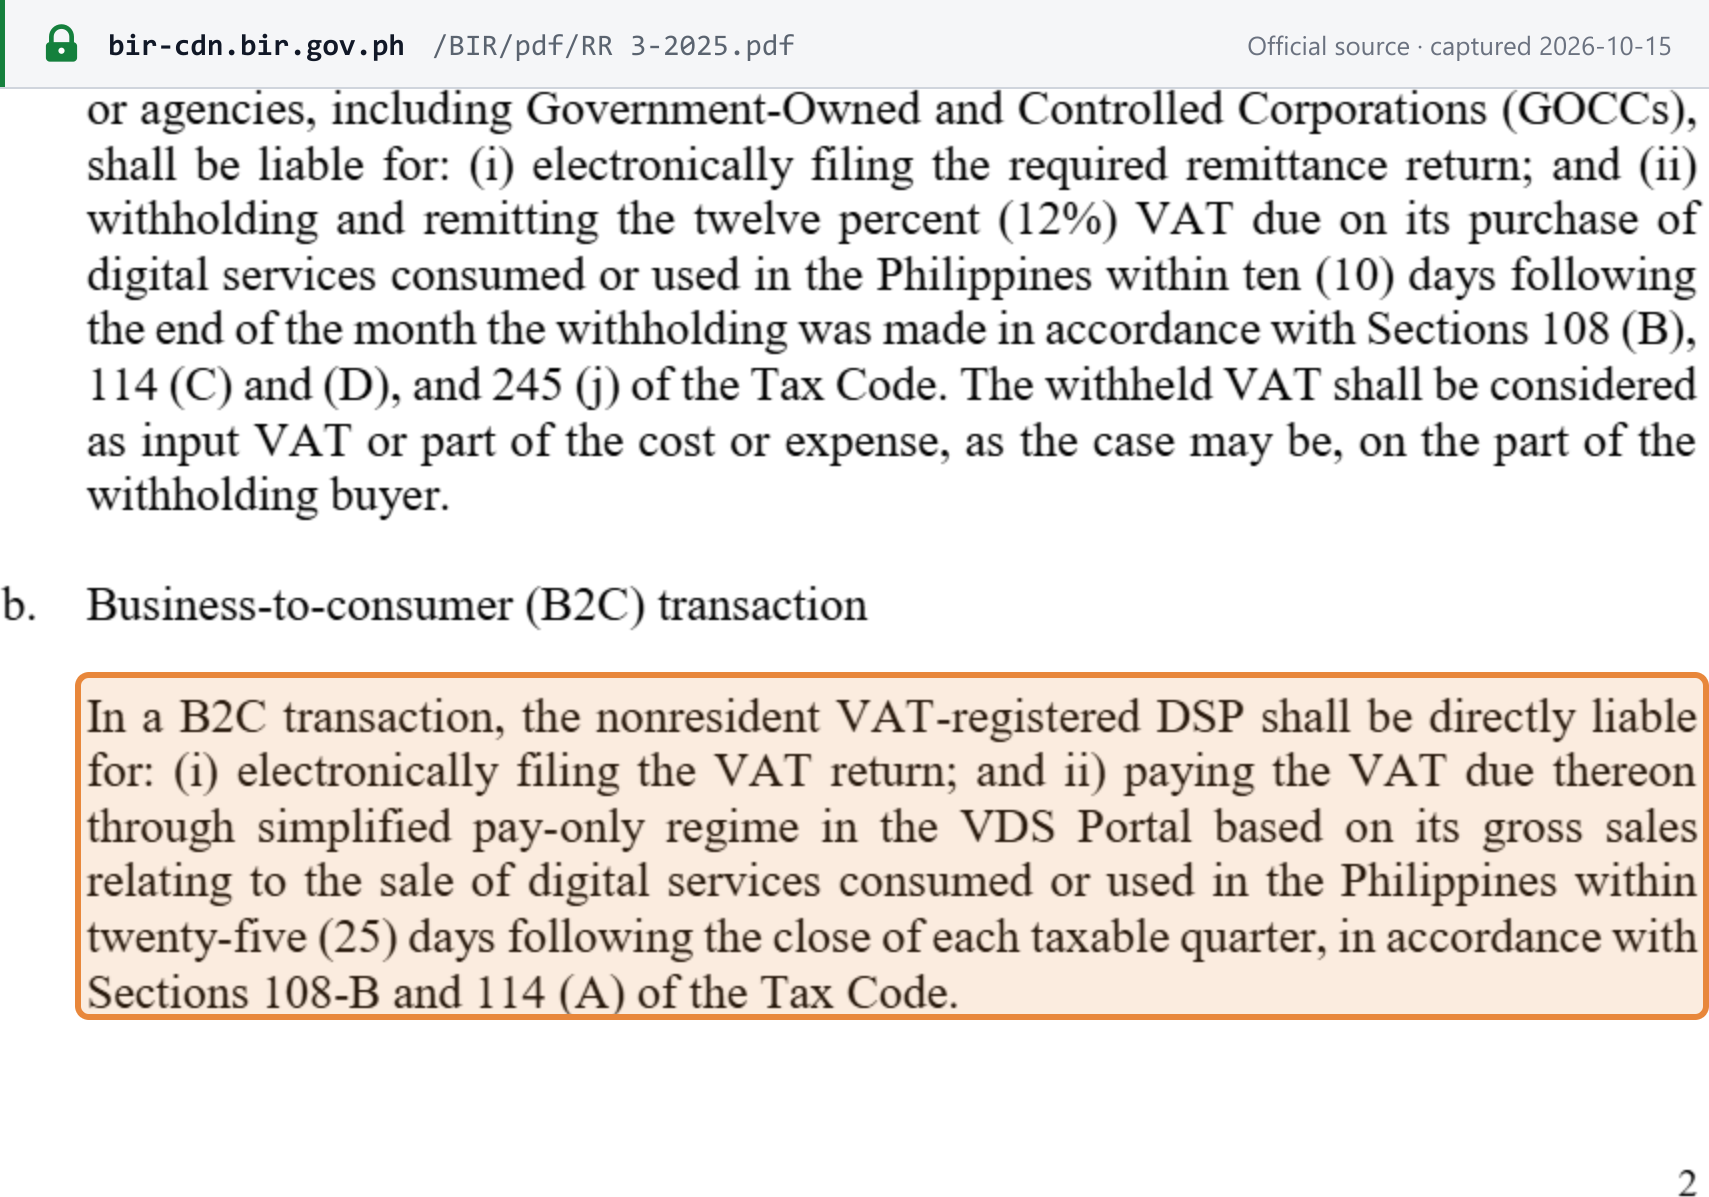
“In a B2C transaction, the nonresident VAT-registered DSP shall be directly liable for: (i) electronically filing the VAT return; and ii) paying the VAT due thereon through simplified pay-only regime in the VDS Portal based on its gross sales relating to the sale of digital services consumed or used in the Philippines within twenty-five (25) days following the close of each taxable quarter”
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR Form 2550-DS — Quarterly VAT Return of nonresident digital service providers (VDS Portal) deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
BIR Form 1600-VT — Monthly Remittance Return of Value-Added Tax Withheld

Value-added tax (VAT) — withholding · Monthly · return filing

10th of the month after the month ends Verified 2026-10-15
Who files
Withholding agents: government offices, local government units and GOCCs withholding 5% creditable VAT on purchases; any payor withholding 12% VAT on rent paid to nonresident owners or services from nonresident suppliers; and Philippine businesses buying digital services from nonresident providers (reverse charge).
Notes
VAT withheld in a month is remitted, with this return, by the 10th of the following month. For the digital-services reverse charge the Tax Code itself sets the window — within ten days after the end of the month of withholding — and the BIR says the buyer uses this form whether or not it is VAT-registered. Government withholding at 5% has been creditable since 2021, so the supplier receives BIR Form 2307 rather than 2306. Agents on eFPS file the general Form 1600 instead, on the same date. Government withholding of percentage tax goes on a separate monthly return, BIR Form 1600-PT, also due on the 10th; it is not shown here.
Source
Guidelines and Instructions for BIR Form No. 1600-VT (January 2018) — When and Where to File and Pay Bureau of Internal Revenue (BIR)
See the source text
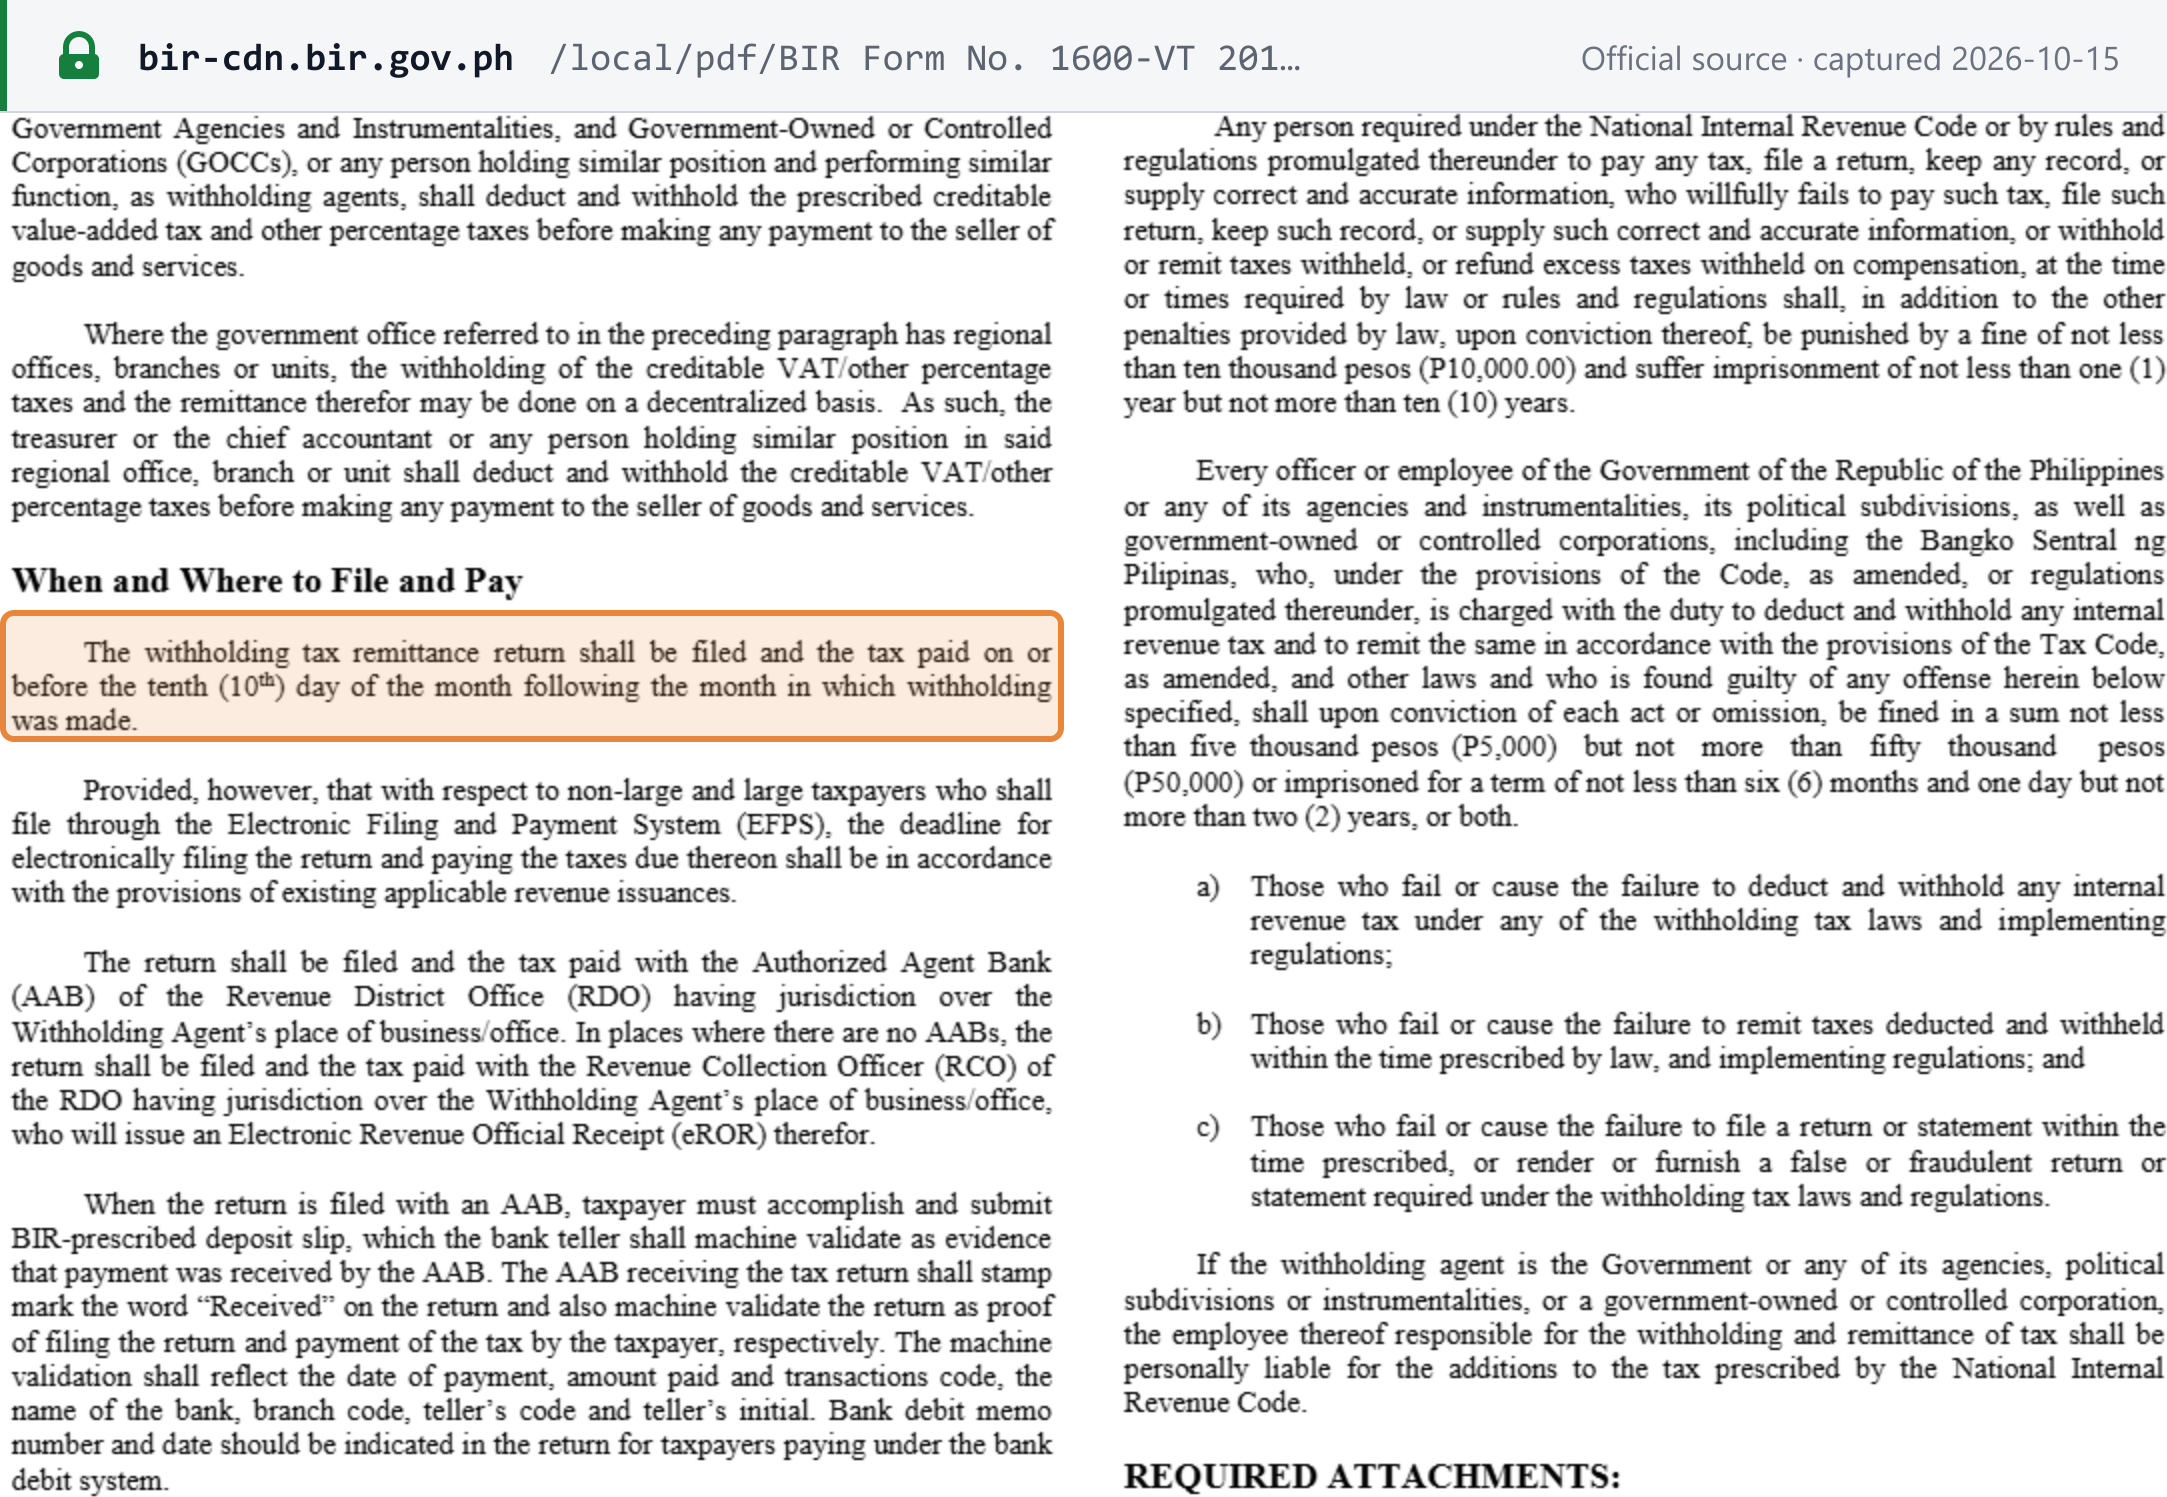
“The withholding tax remittance return shall be filed and the tax paid on or before the tenth (10th) day of the month following the month in which withholding was made.”
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR Form 1600-VT — Monthly Remittance Return of Value-Added Tax Withheld deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
BIR Form 2551Q — Quarterly Percentage Tax Return

Percentage tax · Quarterly · return filing

25th of the month after the quarter ends Verified 2026-10-15
Who files
Calendar-year filers that are not VAT-registered and whose gross sales or receipts do not exceed PHP 3,000,000 (3% under s.116, cooperatives exempt), plus calendar-year businesses subject to the special percentage taxes — carriers, franchise grantees, banks and other financial intermediaries, insurers, amusement operators and others.
Notes
For calendar-year filers, return and percentage tax are due within 25 days after each quarter: 25 April, July, October and January. A business on a fiscal year counts the 25 days from the end of its own fiscal quarter instead, so its dates are not the ones shown here. Individuals who elect the 8% income-tax option stop filing this return and must end-date it with the BIR. A business whose VAT registration is cancelled owes percentage tax from the date of cancellation.
Source
Republic Act No. 12023, Section 10 amending NIRC Section 128(A)(1) — BIR copy Bureau of Internal Revenue (BIR)
See the source text
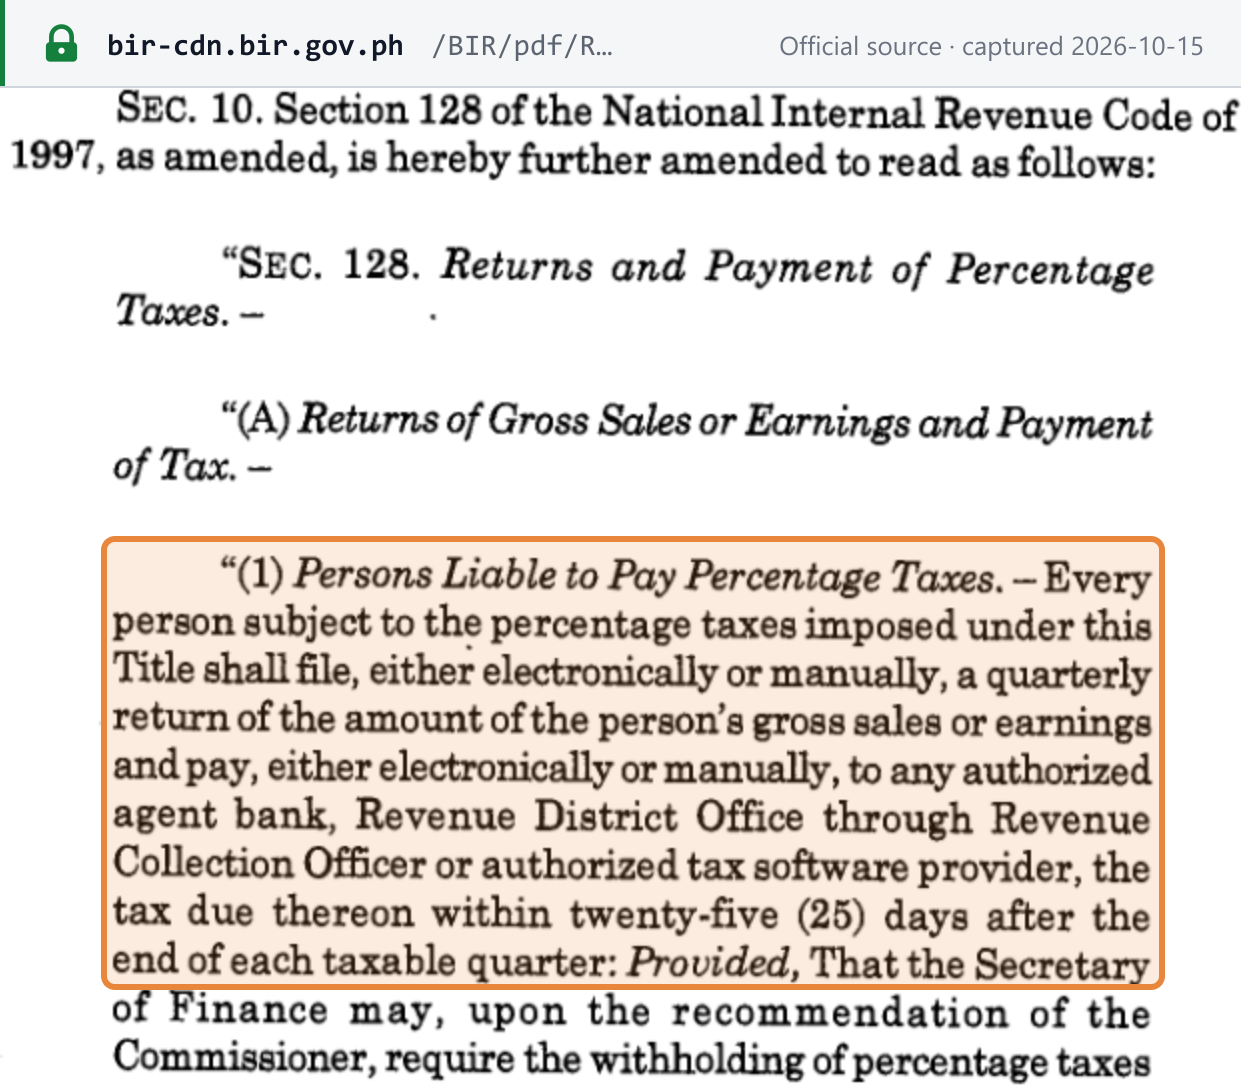
“the tax due thereon within twenty-five (25) days after the end of each taxable quarter”
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR Form 2551Q — Quarterly Percentage Tax Return deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
Final BIR Form 2550Q after cancellation of VAT registration

Value-added tax (VAT) · One-off · return filing

within 25 days of the date the VAT registration is cancelled Verified 2026-10-15
Who files
Any taxpayer whose VAT registration has been cancelled — on closing the business, or on dropping below the threshold and opting out.
Notes
Cancelling a VAT registration triggers one last 2550Q, with the VAT due paid, within 25 days of the cancellation. Until the registration is actually cancelled, the quarterly return stays due every quarter even with nothing to report. Cancellation takes effect from the first day of the month after it is granted.
Source
Guidelines and Instructions for BIR Form No. 2550Q (April 2024 ENCS) — When and Where to File and Pay Bureau of Internal Revenue (BIR)
See the source text
“Any taxpayer whose registration has been cancelled shall file a return and pay the tax due thereon within twenty-five (25) days from date of cancellation of registration.”
Screenshot of Bureau of Internal Revenue (BIR) showing the Final BIR Form 2550Q after cancellation of VAT registration deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15
Percentage tax return on retiring from business

Percentage tax · One-off · return filing

within 20 days of closing the business Verified 2026-10-15
Who files
Any person retiring from a business subject to percentage tax.
Notes
Closing a business that pays percentage tax shortens the clock: notify the nearest BIR office, then file the return and pay within 20 days after closing — five days fewer than the regular quarterly 2551Q allows.
Source
Republic Act No. 12023, Section 10 amending NIRC Section 128(A)(2) — BIR copy Bureau of Internal Revenue (BIR)
See the source text
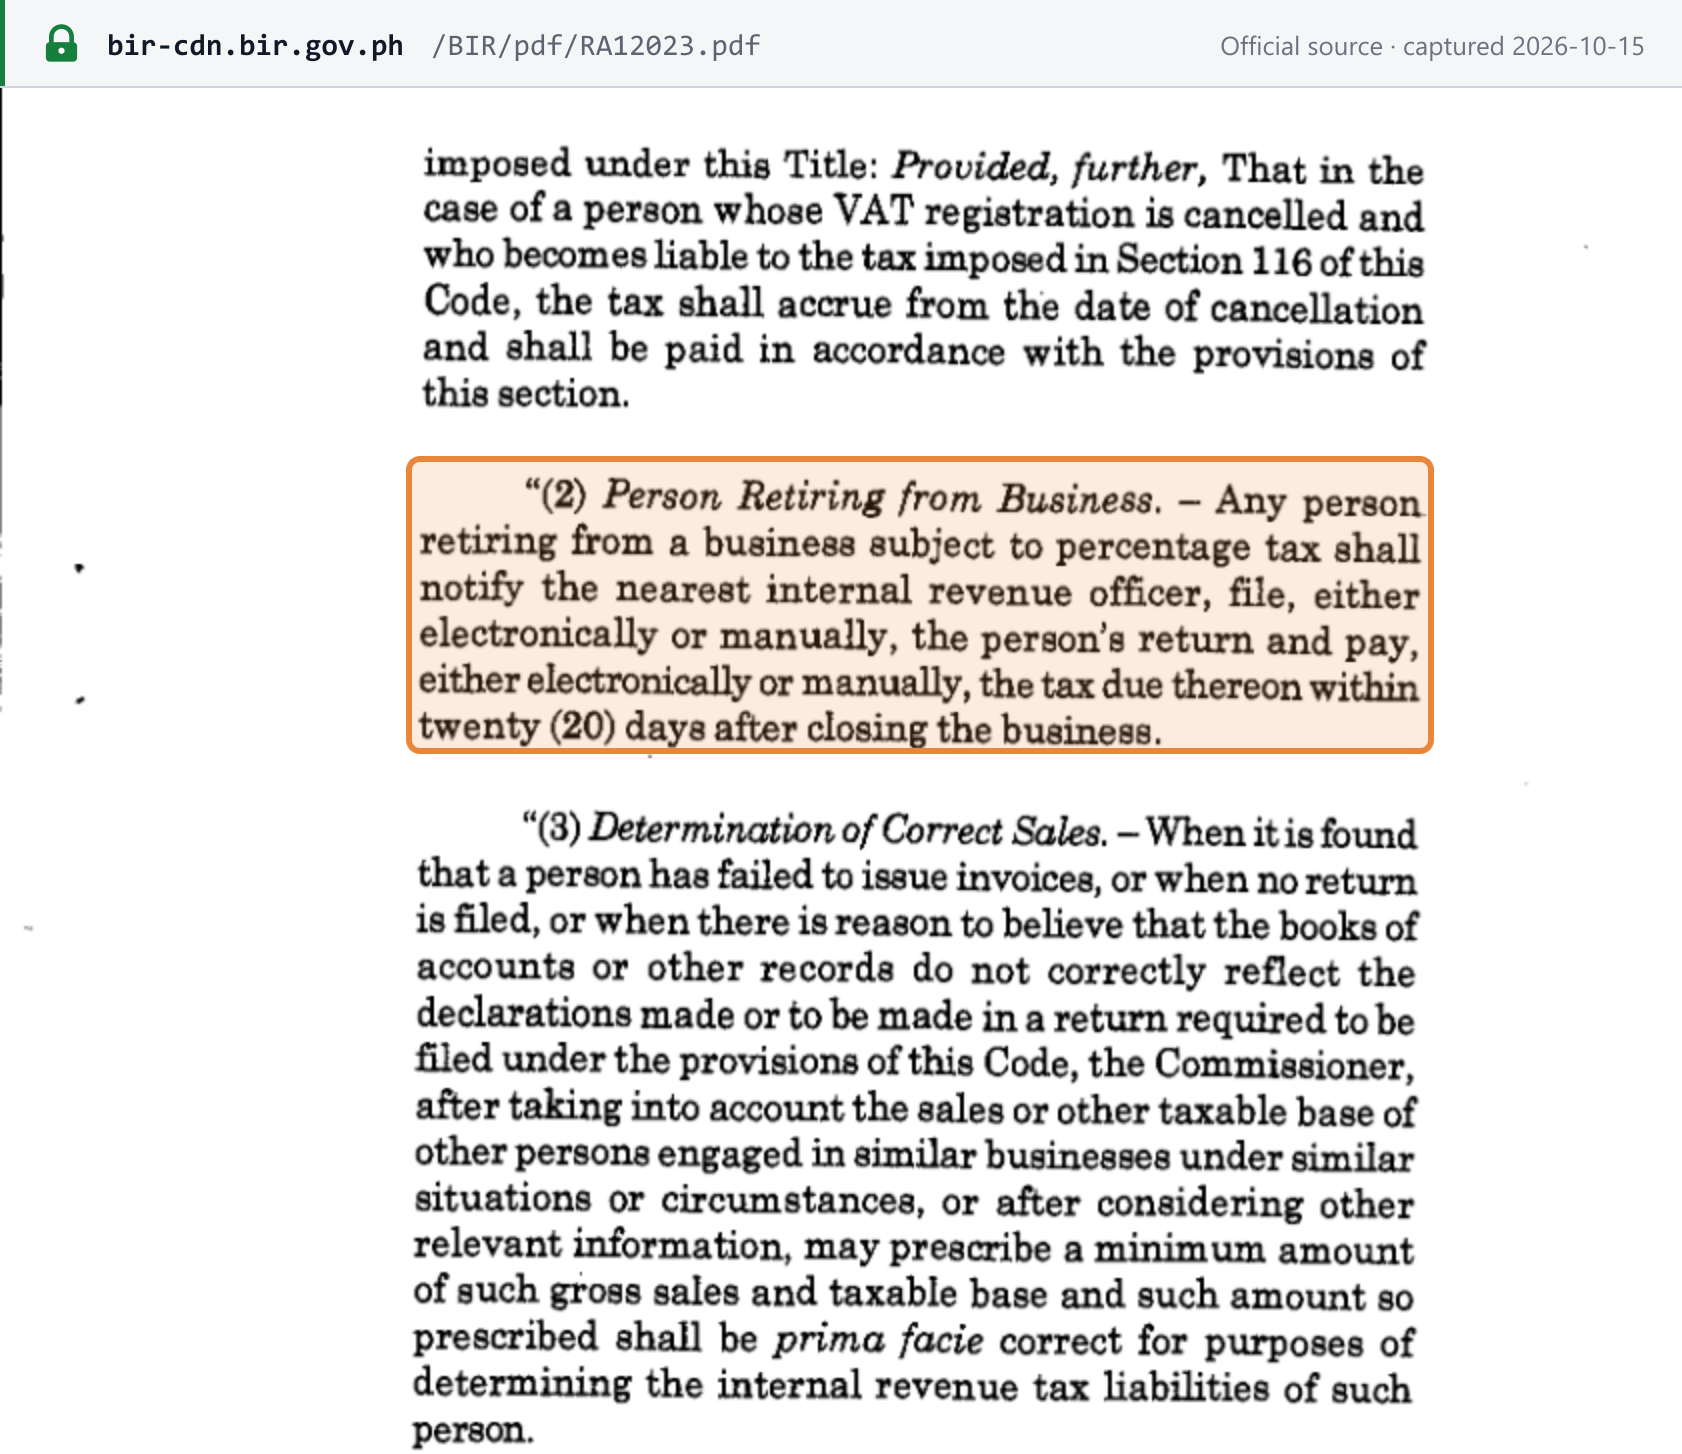
“either electronically or manually, the tax due thereon within twenty (20) days after closing the”
Screenshot of Bureau of Internal Revenue (BIR) showing the Percentage tax return on retiring from business deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15

BIR registration, including VAT or percentage tax — on or before commencement of business

Value-added tax (VAT) and percentage tax · One-off · registration

no later than the day of commencement of business (the first sale, or 30 calendar days after the Mayor's Permit, DTI business-name or SEC registration is issued, whichever comes first) Verified 2026-10-15
Who files
Self-employed individuals, estates, trusts, corporations and their branches starting a business, registering each tax type they will owe — VAT where sales are expected to exceed PHP 3,000,000 in the next 12 months, otherwise percentage tax.
Notes
Register with the Revenue District Office on or before the day the business commences. Commencement is the first sale, or 30 calendar days after the local Mayor's Permit, DTI business-name certificate or SEC registration is issued, whichever comes first, and the BIR treats a business that has not registered within 30 calendar days of those permits or of its first sale as in violation. A business that later crosses the PHP 3,000,000 VAT threshold must register for VAT, but the Tax Code sets no number of days for doing so; until it registers it pays VAT without input tax credits.
Source
Revenue Memorandum Circular No. 91-2024 (BIR digest) — registration-related procedures under RR 7-2024 as amended Bureau of Internal Revenue (BIR)
See the source text
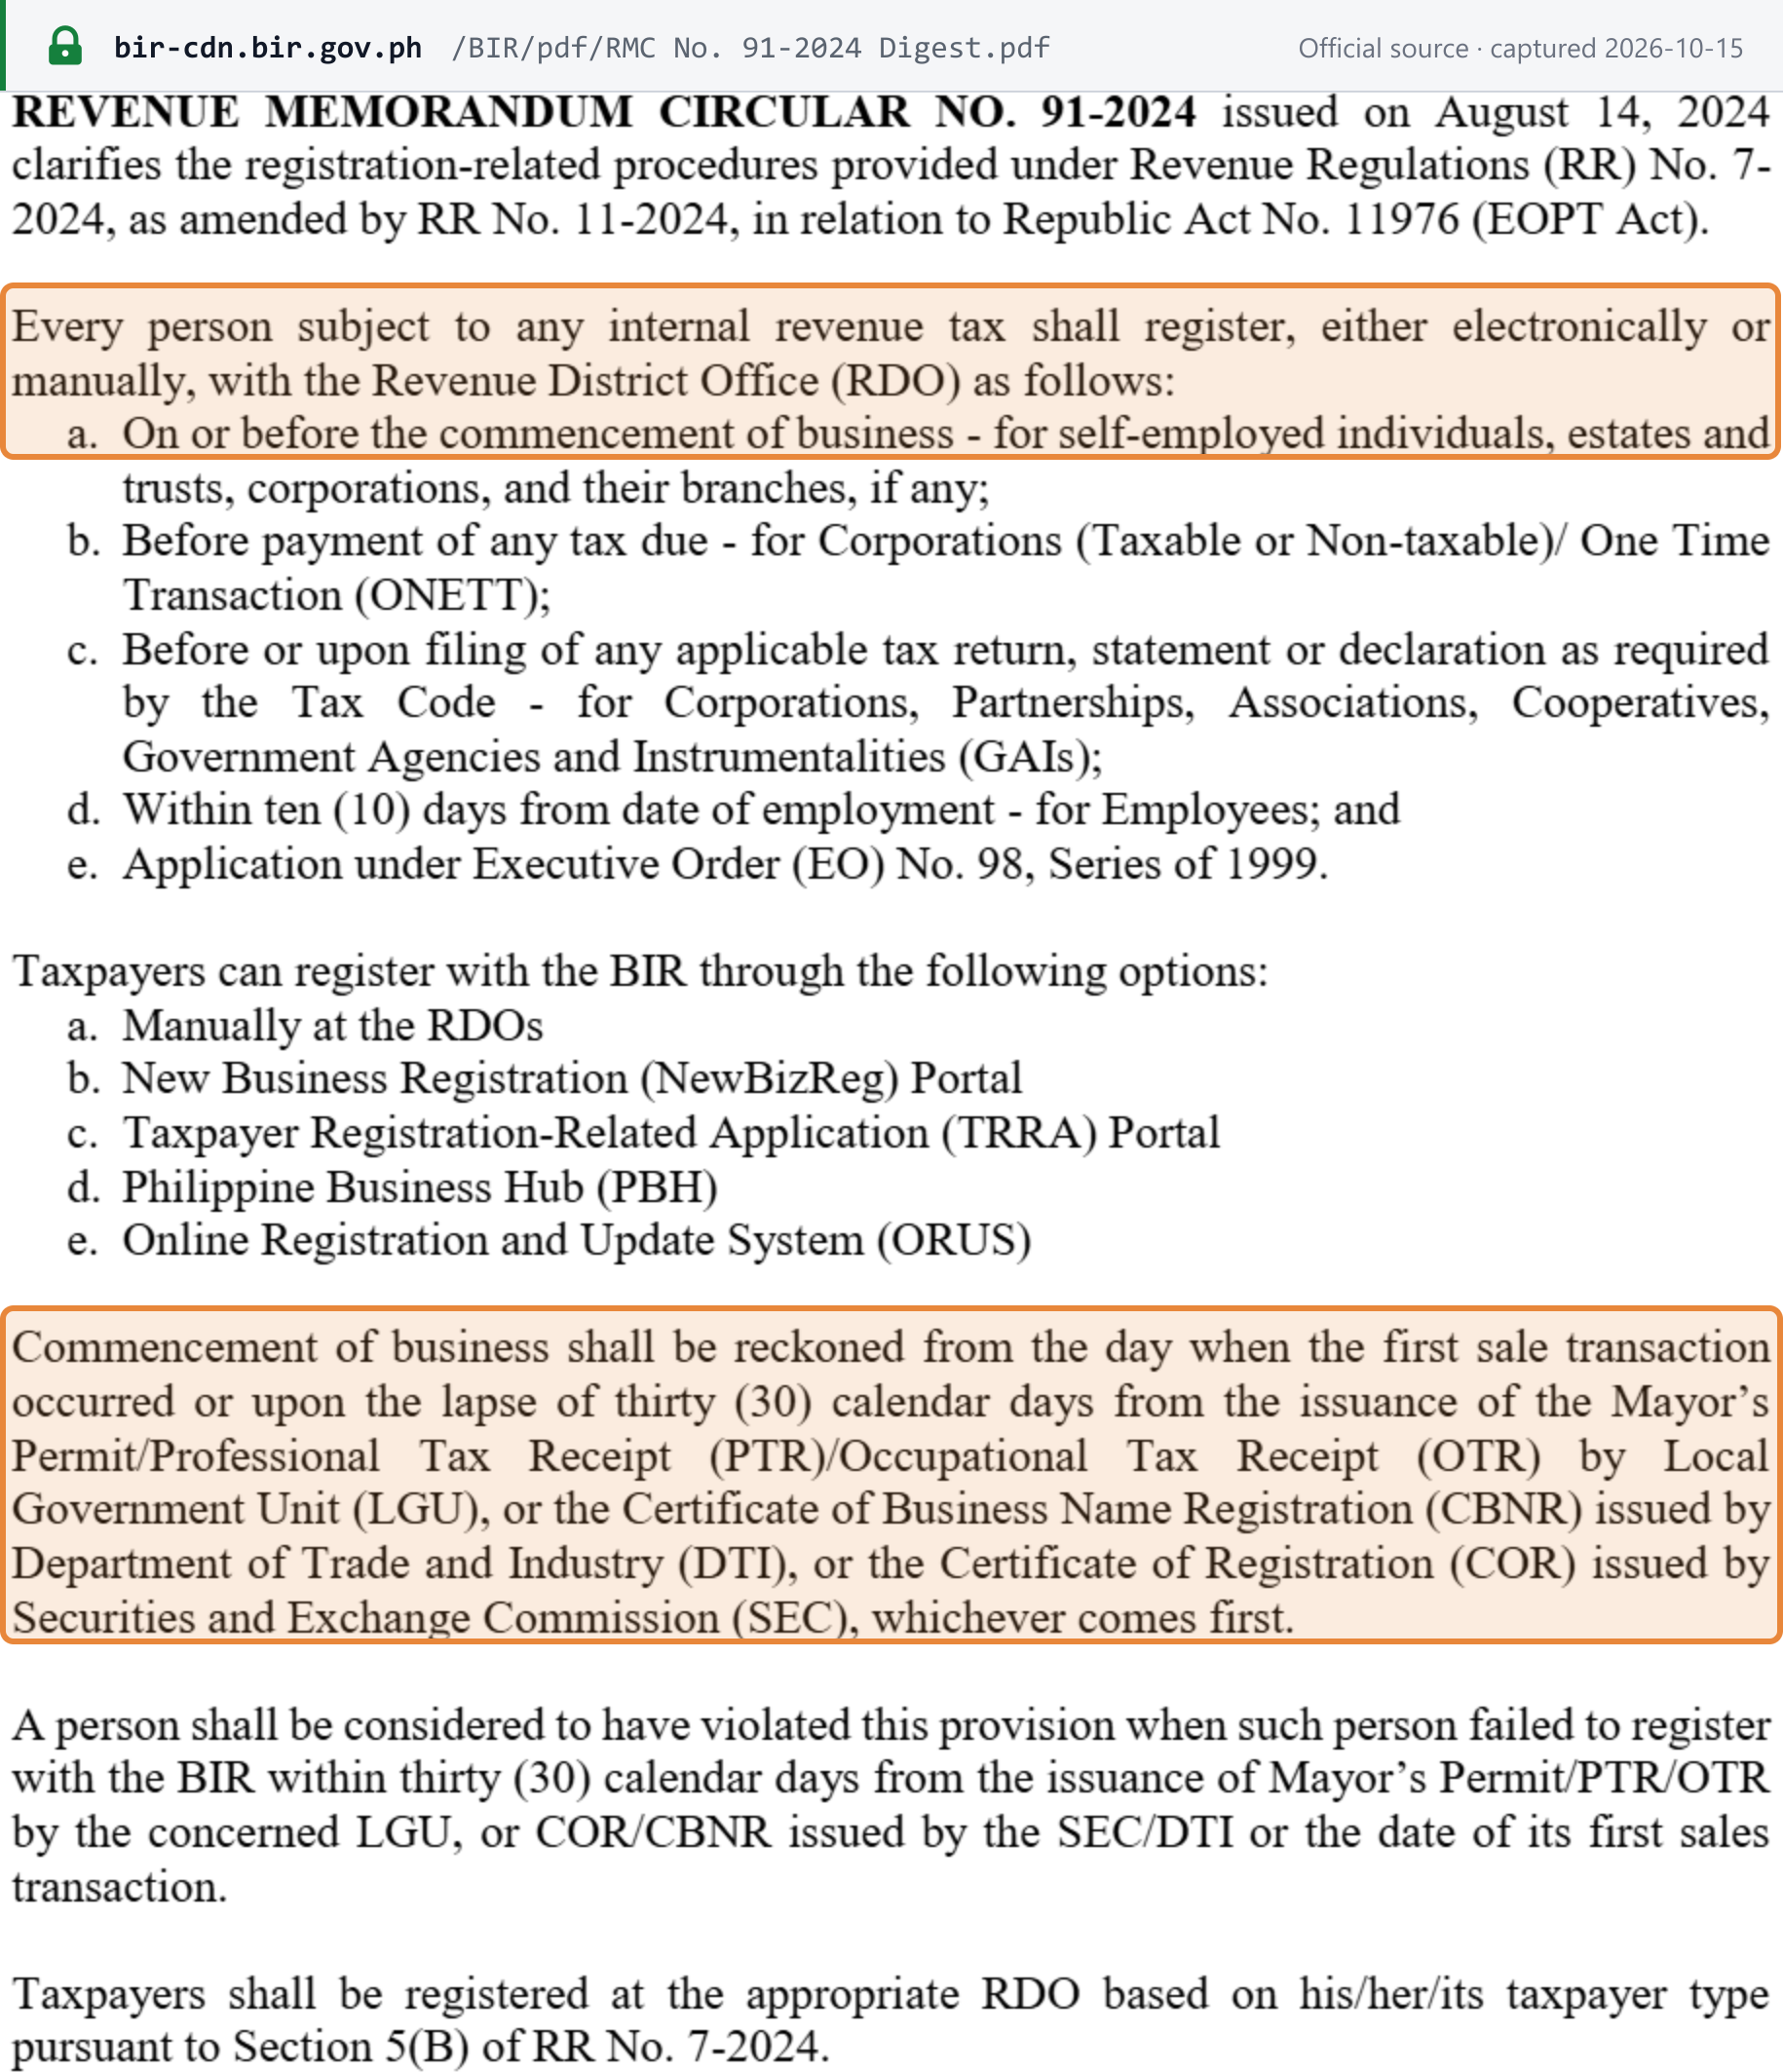
“On or before the commencement of business”
Screenshot of Bureau of Internal Revenue (BIR) showing the BIR registration, including VAT or percentage tax — on or before commencement of business deadline Open full size Captured from Bureau of Internal Revenue (BIR) on 2026-10-15

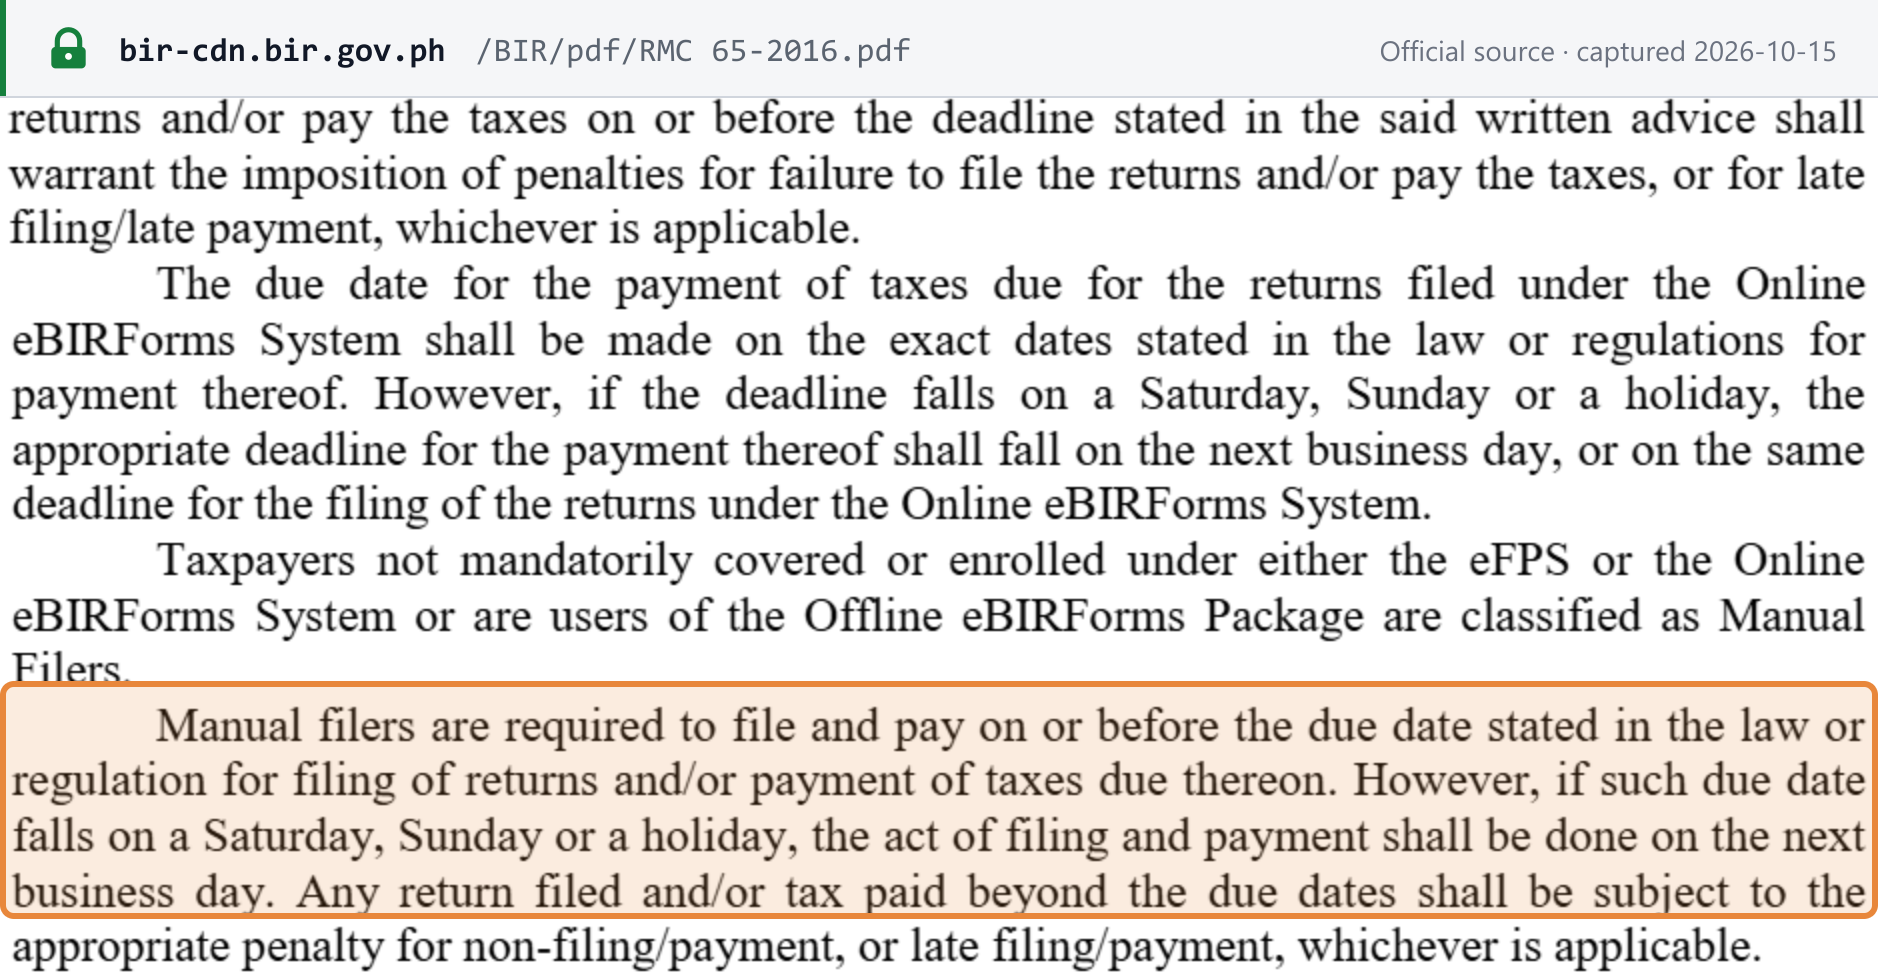
Philippine VAT has been filed quarterly since 1 January 2023: the BIR Form 2550Q and the VAT it reports are due together within 25 days after the close of each taxable quarter, and that quarter is the taxpayer's own, so a fiscal-year business counts from its fiscal quarter ends rather than from March, June, September and December. Businesses below the PHP 3,000,000 VAT threshold usually owe percentage tax on the 2551Q instead, on the same 25-day cycle. When a deadline falls on a Saturday, Sunday or a national holiday, filing and payment move to the next business day. Local holidays declared for a single city or province, and ad hoc extensions the BIR grants to disaster-hit areas, can also move a deadline for the taxpayers they cover; they are announced case by case and are not shown on this calendar. Excise tax is outside the scope of this calendar. Most excise — on alcohol, tobacco, fuel, vehicles and similar goods — is paid before the goods leave the place of production or on importation, but two excise returns are monthly: BIR Form 2200-C for cosmetic procedures, due within 10 days after the month ends, and BIR Form 2200-M for metallic minerals. Neither is shown here. VAT on imported goods is paid to the Bureau of Customs before release.

“However, if such due date falls on a Saturday, Sunday or a holiday, the act of filing and payment shall be done on the next business day.”
Screenshot of the official source stating the rule that governs Philippines's deadlines
Revenue Memorandum Circular No. 65-2016 (BIR digest) — due dates falling on a Saturday, Sunday or holiday — Bureau of Internal Revenue (BIR), captured 2026-10-15

What this calendar does not list

  • Not applicable Annual or reconciliation return — The National Internal Revenue Code prescribes no annual VAT or percentage-tax return: s.114(A) and s.128(A) provide only quarterly returns, and the BIR's form guidance lists only the quarterly 2550Q and 2551Q for these taxes. Checked 2026-10-15.
  • Not yet covered E-invoicing / e-reporting cycle — RR 8-2022 requires sales data to be transmitted to the BIR within three calendar days of each transaction, but RMC 98-2026 (22 September 2026) defers electronic sales reporting until the BIR issues implementing guidelines, so no taxpayer transmits on that cycle yet. The separate 31 December 2026 deadline to start issuing e-invoices is an issuance mandate, not a reporting cycle. Checked 2026-10-15.
  • Not yet covered Periodic return — Excise taxes (NIRC Title VI) are out of scope and not shown. Most excise is paid before removal from the place of production or on importation, but BIR Form 2200-C (cosmetic procedures, monthly, within 10 days after the month ends under RR 2-2019) and BIR Form 2200-M (metallic minerals, monthly) are periodic returns this calendar does not carry. Smaller percentage-tax cycles such as the overseas-communications tax (20 days after the quarter) and the monthly 1600-PT remittance of percentage tax withheld by government are also not shown.
  • Not yet covered Recapitulative listing — VAT-registered persons submit a quarterly Summary List of Sales and Purchases (SLSP), but its deadline differs by filer group and could not be confirmed from the regulations (RR 1-2012 and RR 16-2005 were not retrievable from the BIR's site), so it is not dated here. Checked 2026-10-15.

New Philippines rules taking effect

Confirmed changes from the weekly scan — each links to its full record with the official source.

About this calendar

Which Philippines tax deadlines does this calendar cover?

9 recurring indirect-tax obligations — Value-added tax (VAT) and Percentage tax returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-15). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.