營業人銷售額與稅額申報書 (Forms 401 / 403 / 404) — two-monthly
Business tax (營業稅 — VAT) · Every 2 months · return filing
15th of the month after the two-month period ends Verified 2026-10-15- Who files
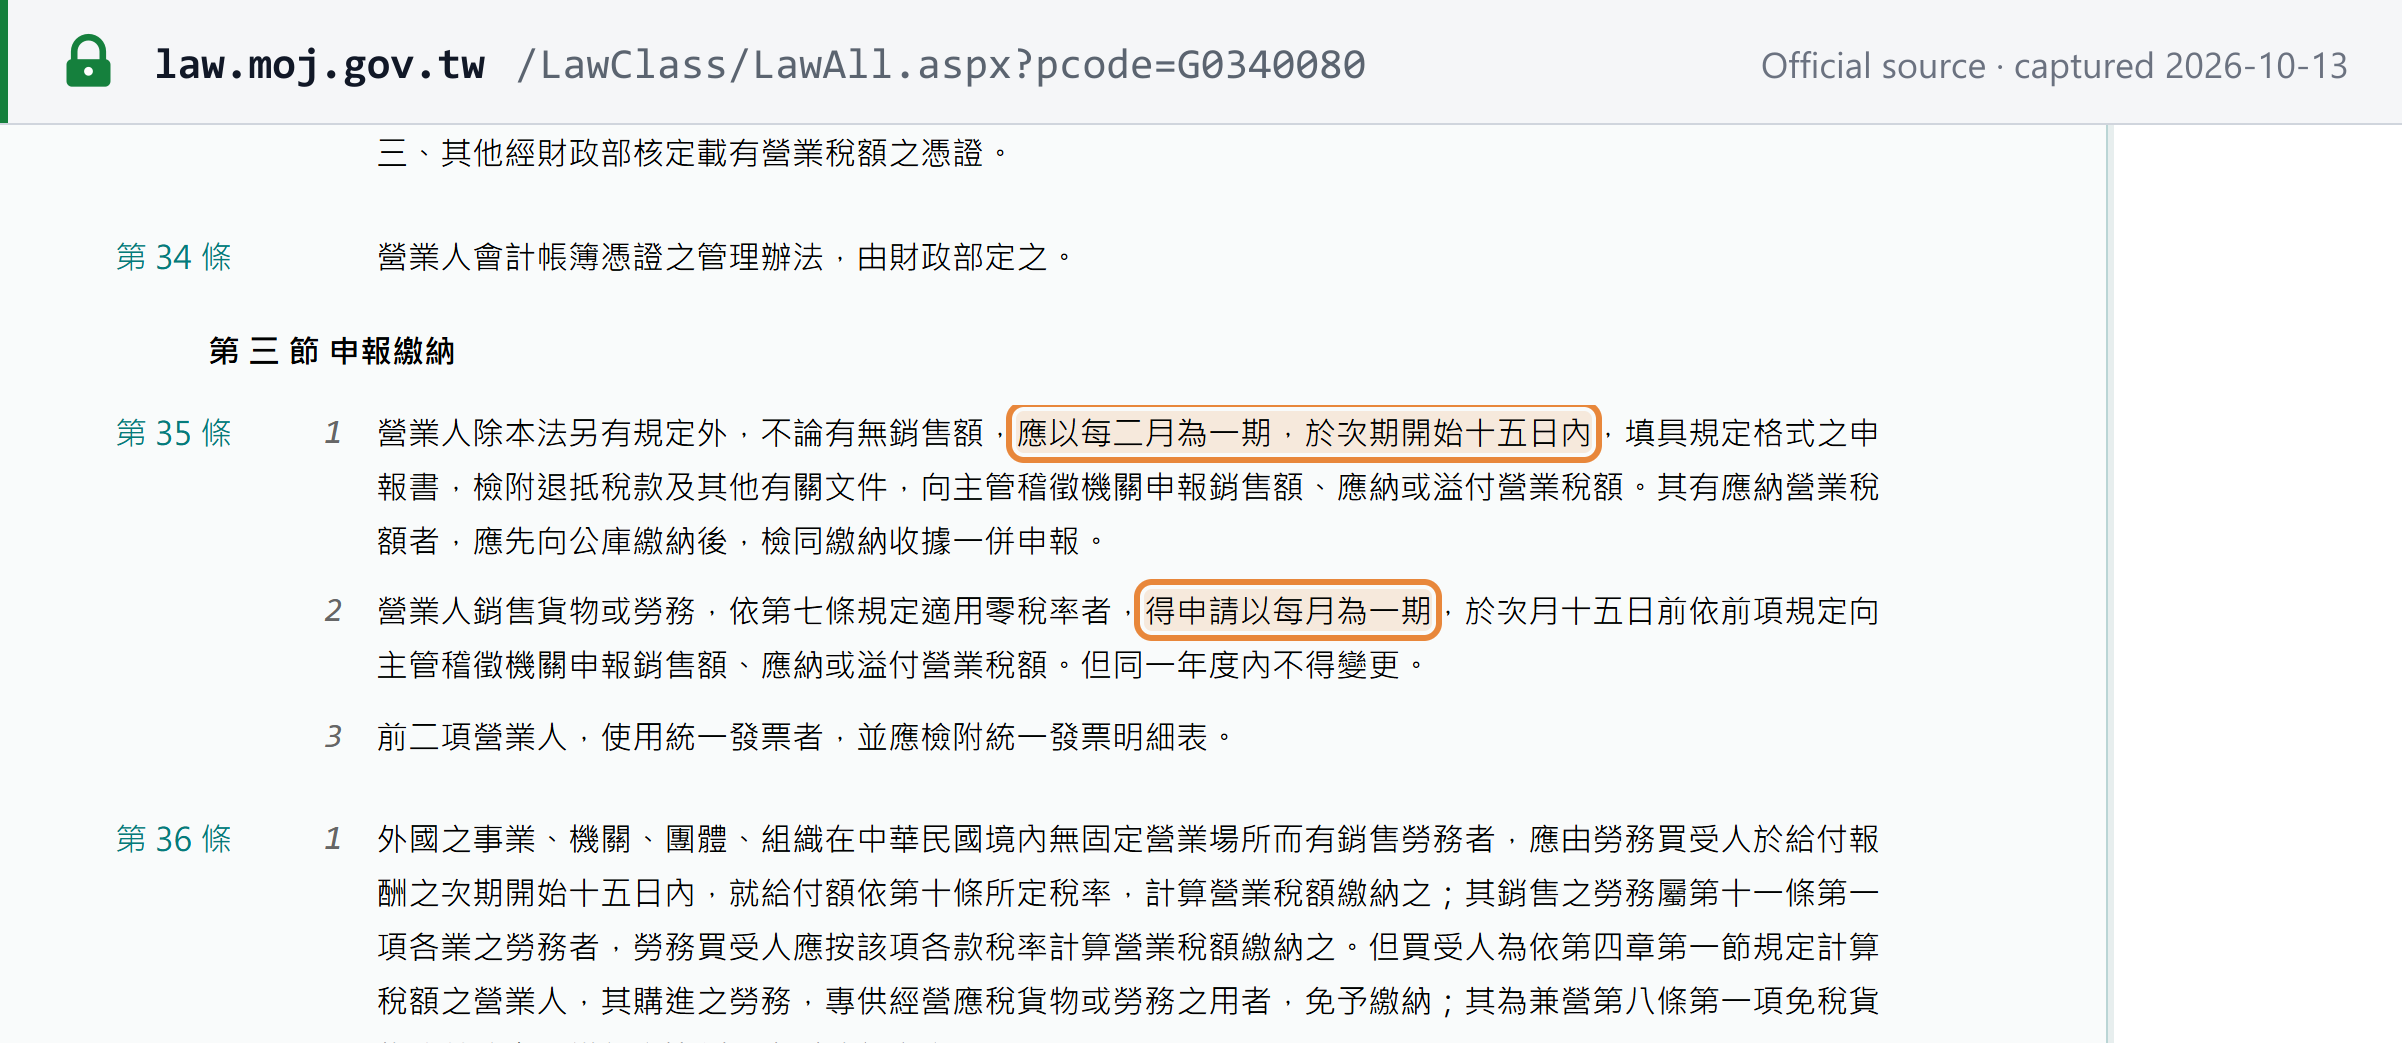
- Every business that files business-tax returns under Article 35 of the Business Tax Act, whether or not it made sales in the period — VAT-method businesses on Forms 401 and 403, and non-VAT-method filers such as banks, insurers and other financial businesses on Form 404 — unless approved to file monthly.
- Notes
- A return is due for every two-month period even if you sold nothing. Pay any tax due first, at a bank or online, and file the return with the payment receipt by the same date. Users of uniform invoices attach the invoice detail list. Filing late costs a surcharge of 1% of the tax for every two days, between NT$1,200 and NT$12,000, rising to 30% once the return is more than 30 days late.
- Source
- 加值型及非加值型營業稅法施行細則 (Business Tax Act Enforcement Rules), Art 38-1 para 1 Ministry of Justice — Laws & Regulations Database of the Republic of China (Taiwan)
See the source text
“應以每二月為一期,分別於每年一月、三月、五月、七月、九月、十一月之十五日前向主管稽徵機關申報上期之銷售額、應納或溢付營業稅額。”
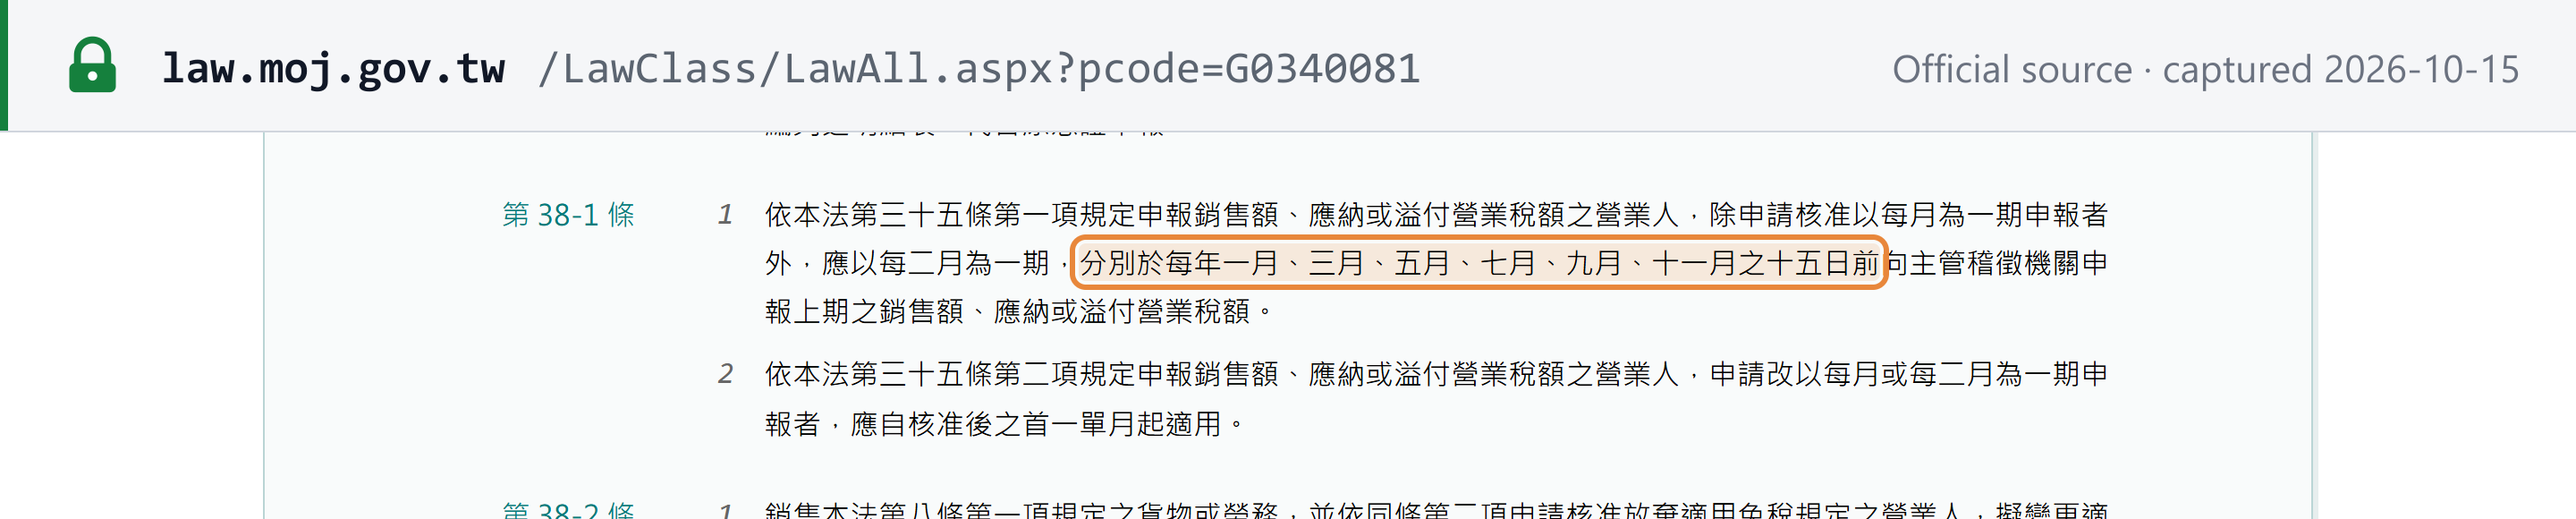 Open full size Captured from Ministry of Justice — Laws & Regulations Database of the Republic of China (Taiwan) on 2026-10-15