Thailand compliance calendar

13 recurring VAT (ภาษีมูลค่าเพิ่ม) and Specific business tax (ภาษีธุรกิจเฉพาะ) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Thailand rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Payment Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Thailand applies one — 7 of 13 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

ภ.พ.30 (P.P.30) VAT return and payment — paper filing

VAT (ภาษีมูลค่าเพิ่ม) · Monthly · return filing

15th of the month after the month ends Verified 2026-10-21
Who files
Every VAT registrant (registration is compulsory above THB 1.8 million of annual turnover), one return per place of business unless joint filing has been approved, when filing on paper.
Notes
The statutory deadline: return and payment for each tax month by the 15th of the next month. A nil return is still required in a month with no sales. Each branch files separately unless the Revenue Department has approved joint filing. Filing online gives until the 23rd, but only until that extension lapses at the end of January 2027.
Source
Revenue Code s.83 (consolidated Thai text) The Revenue Department (กรมสรรพากร)
See the source text
“การยื่นแบบแสดงรายการภาษีและการชำระภาษีสำหรับเดือนภาษีใดให้ยื่นภายในวันที่สิบห้าของเดือนถัดไป เว้นแต่อธิบดีจะกำหนดเป็นอย่างอื่น”
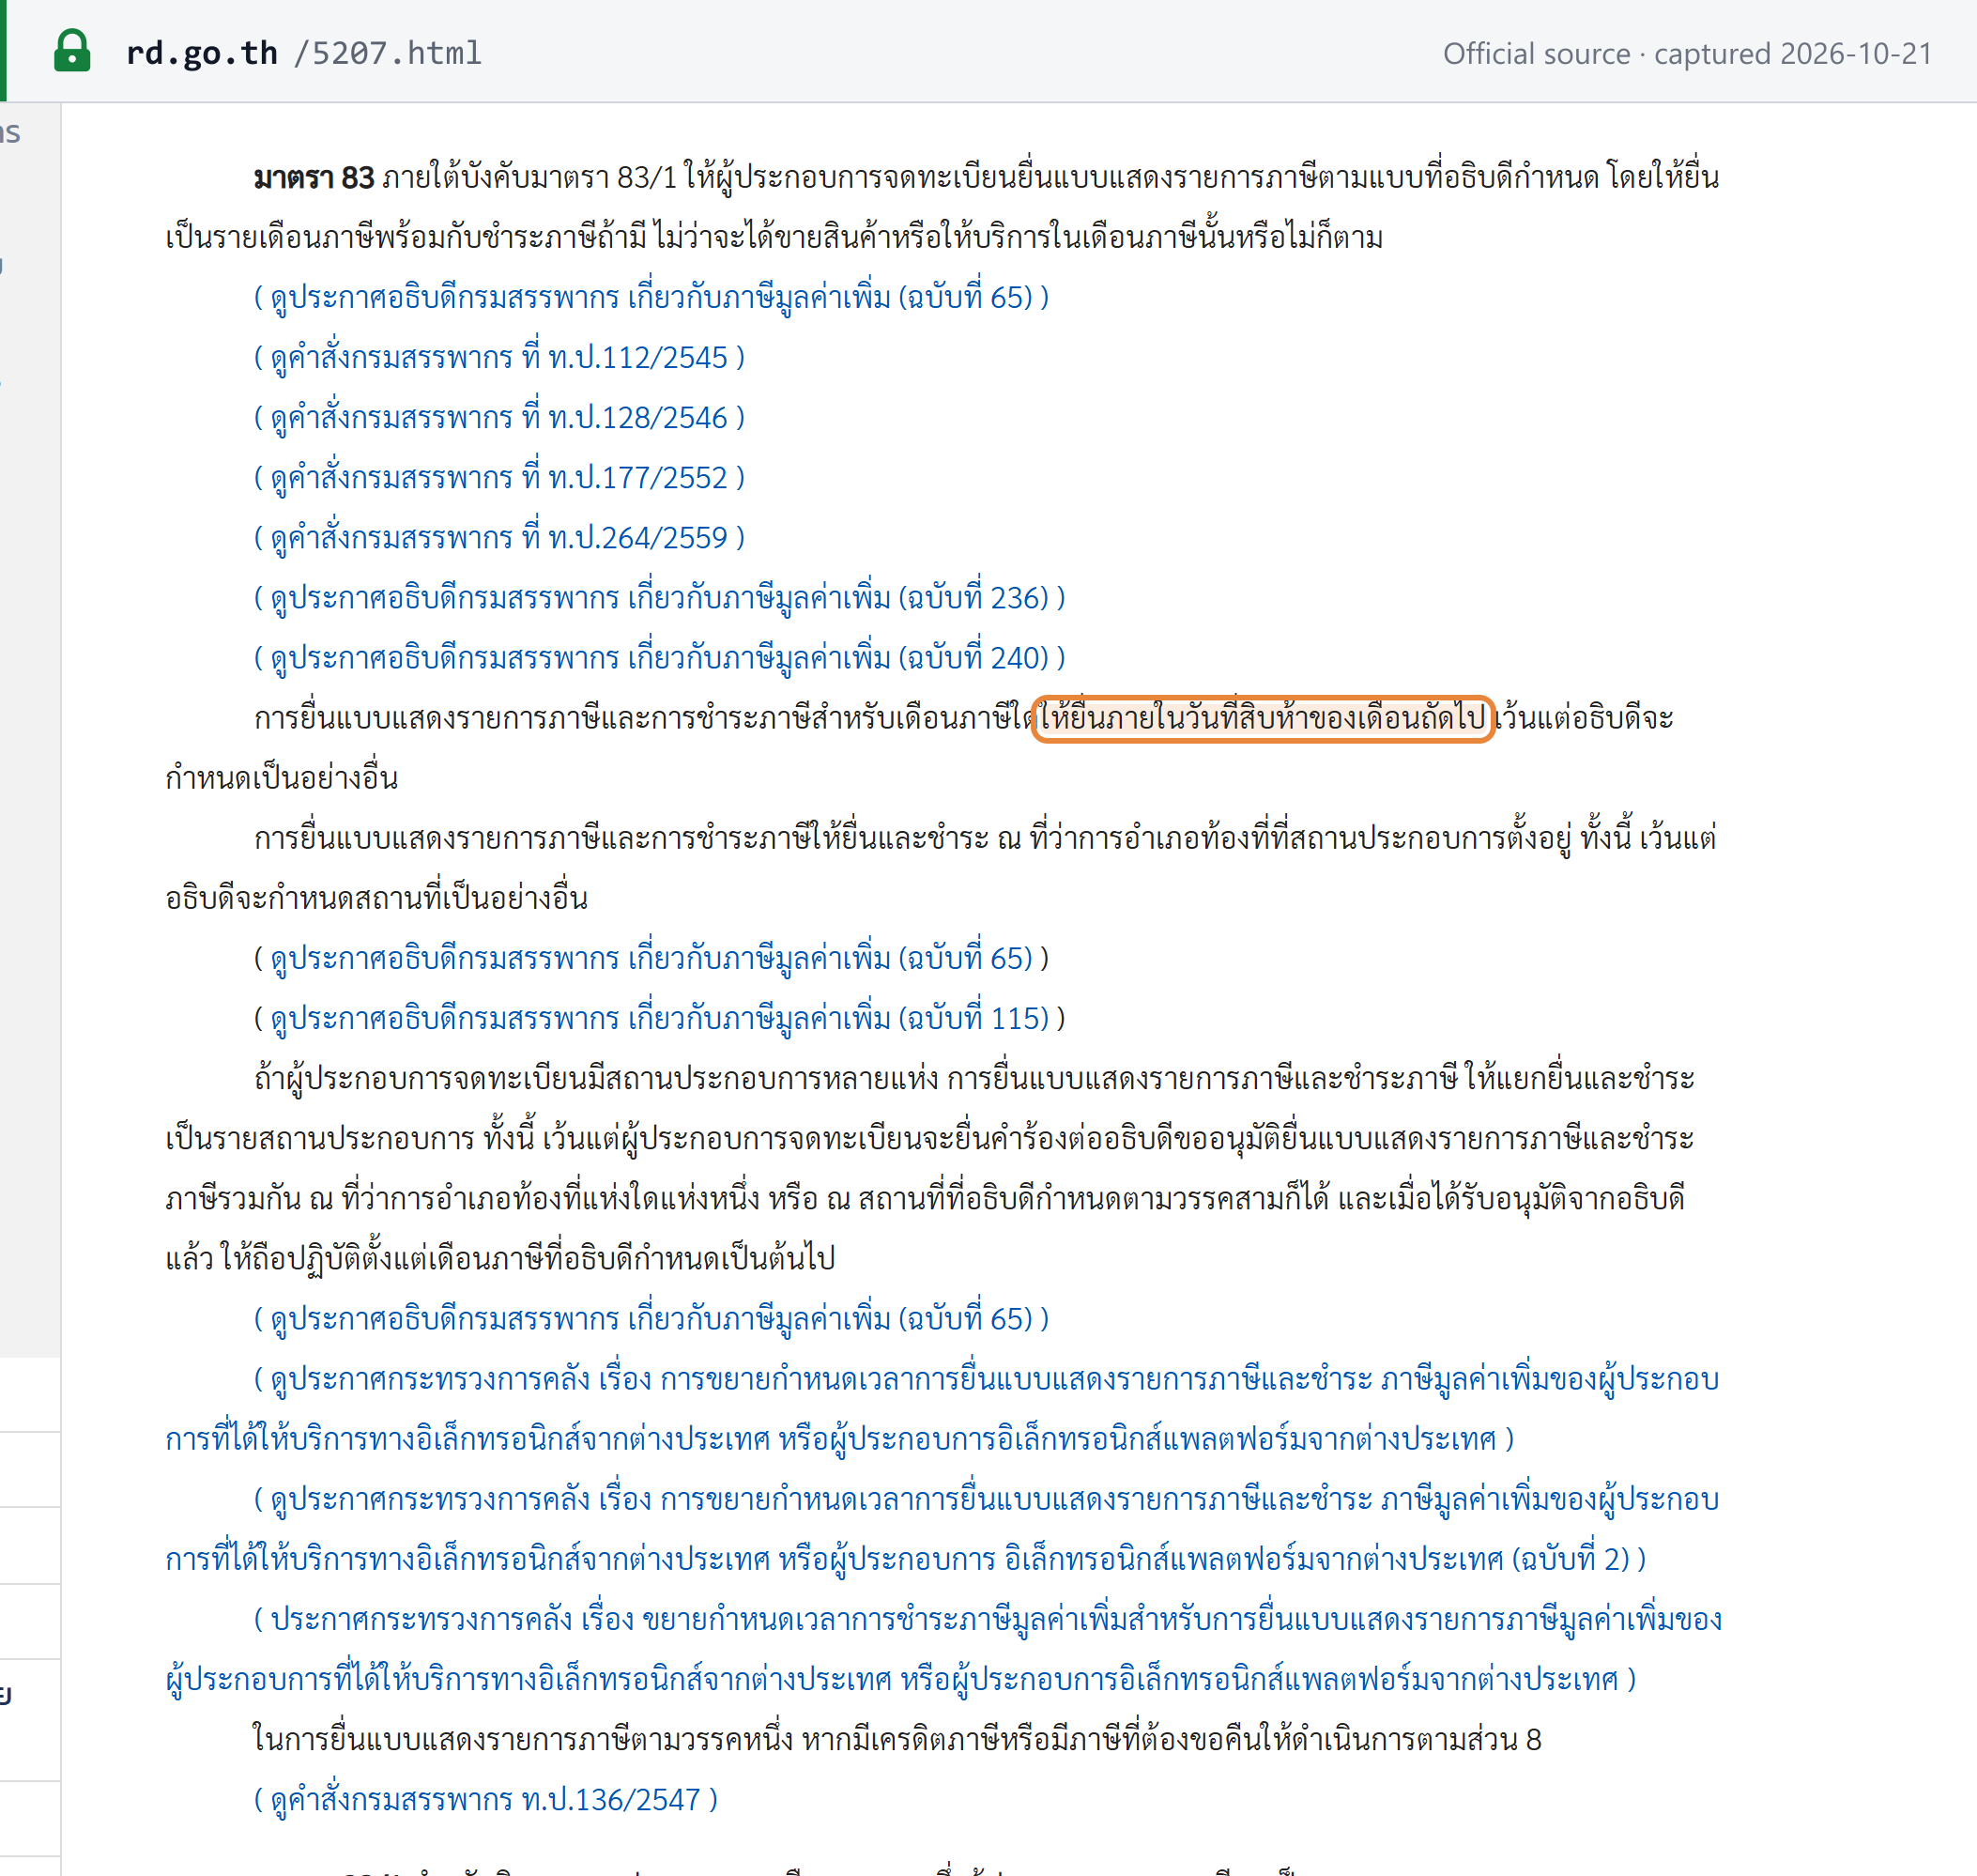
Screenshot of The Revenue Department (กรมสรรพากร) showing the ภ.พ.30 (P.P.30) VAT return and payment — paper filing deadline Open full size Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
ภ.พ.30 (P.P.30) VAT return and payment — filed online

VAT (ภาษีมูลค่าเพิ่ม) · Monthly · return filing

23rd of the month after the month ends Verified 2026-10-21
Who files
VAT registrants who file both the original and any additional return through the Revenue Department's e-filing system. Anyone who first filed that month's return on paper loses the extra days.
Notes
Filing online moves the 15th to the 23rd. The extension ceases after returns due by 31 January 2027: Ministry of Finance notification No. 7, as amended by Nos. 8 and 9, covers only returns whose deadline falls between 1 February 2024 and 31 January 2027. The last covered return is December 2026's, due 23 January 2027, a Saturday, so Monday 25 January. No renewal had been published by 21 October 2026; until one is, plan on the 15th from February 2027.
Source
Ministry of Finance notification on extending filing and payment deadlines for internet filing (No. 7, 12 January 2024, as amended by Nos. 8 and 9), item 1.6(1) Ministry of Finance, published by The Revenue Department
See the source text
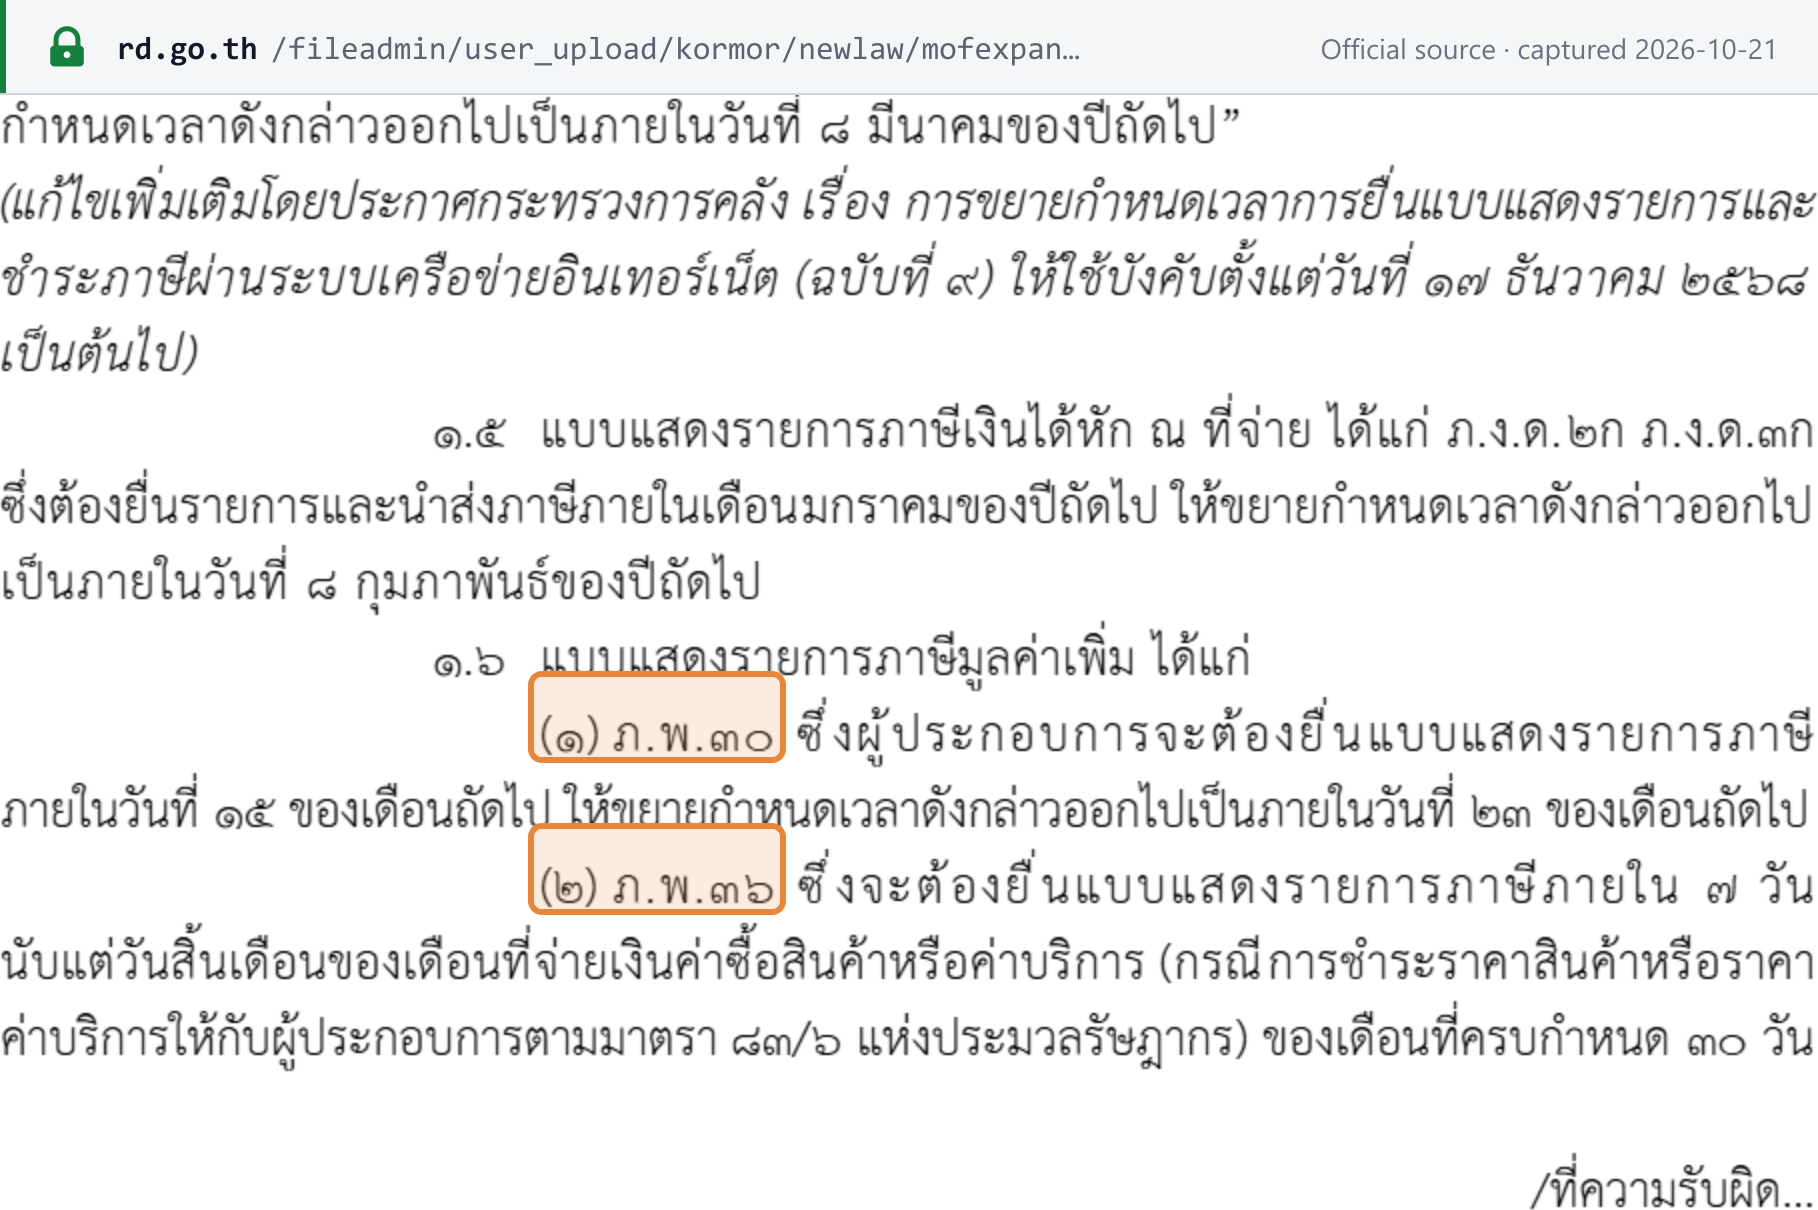
“ภ.พ.๓๐ ซึ่งผู้ประกอบการจะต้องยื่นแบบแสดงรายการภาษีภายในวันที่ ๑๕ ของเดือนถัดไป ให้ขยายกำหนดเวลาดังกล่าวออกไปเป็นภายในวันที่ ๒๓ ของเดือนถัดไป”
Screenshot of Ministry of Finance, published by The Revenue Department showing the ภ.พ.30 (P.P.30) VAT return and payment — filed online deadline Open full size Captured from Ministry of Finance, published by The Revenue Department on 2026-10-21

ภ.พ.36 (P.P.36) self-assessed VAT remittance — paper filing

VAT (ภาษีมูลค่าเพิ่ม) — reverse charge · Monthly · payment

7th of the month after the month ends Verified 2026-10-21
Who files
Anyone in Thailand who pays a foreign provider for services used in Thailand (other than e-services bought by non-registrants, which the provider handles), or pays a temporary non-resident operator; also zero-rated transferees (s.83/7) and auctioneers selling a registrant's property (s.83/5). Only for months in which such a payment is made.
Notes
The payer, not the foreign supplier, remits the VAT: within seven days after the end of the month in which the service fee was paid, so by the 7th of the next month. The return is tied to payments, so there is nothing to file for a month with none. A transferee under s.83/7 counts its seven days from the end of the month in which 30 days from the tax point expire. The 7 November 2026 deadline moved to Monday 9 November. Filing online gives until the 15th, but only for forms due by 31 January 2027.
Source
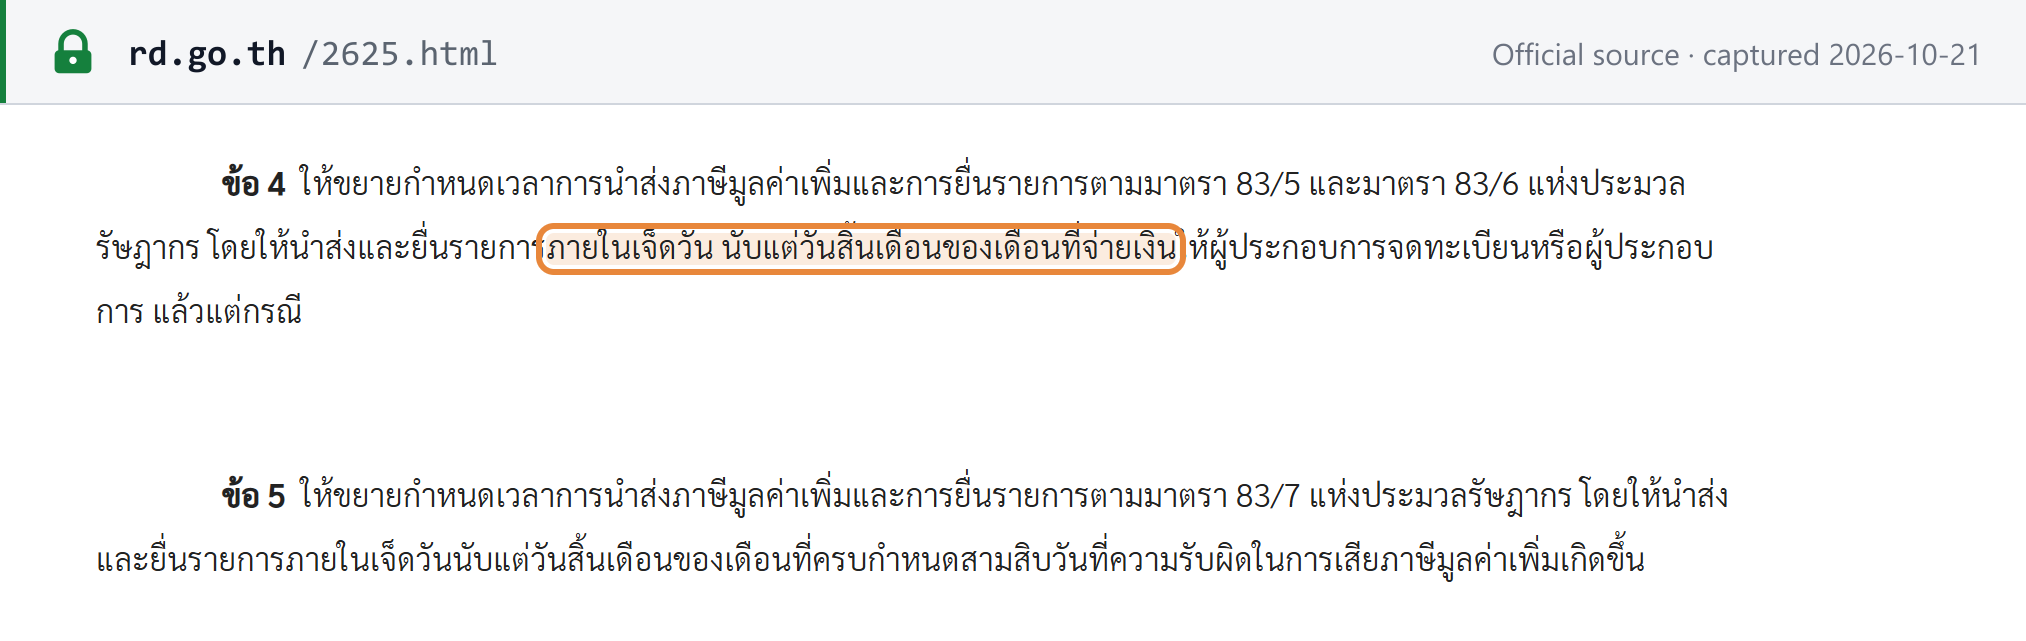
Ministry of Finance notification of 24 July 2001 extending the remittance deadline for VAT under Revenue Code ss.83/5, 83/6 and 83/7, clause 4 Ministry of Finance, published by The Revenue Department
See the source text
“ให้ขยายกำหนดเวลาการนำส่งภาษีมูลค่าเพิ่มและการยื่นรายการตามมาตรา 83/5 และมาตรา 83/6 แห่งประมวลรัษฎากร โดยให้นำส่งและยื่นรายการภายในเจ็ดวัน นับแต่วันสิ้นเดือนของเดือนที่จ่ายเงินให้ผู้ประกอบการจดทะเบียนหรือผู้ประกอบการ”
Screenshot of Ministry of Finance, published by The Revenue Department showing the ภ.พ.36 (P.P.36) self-assessed VAT remittance — paper filing deadline Open full size Captured from Ministry of Finance, published by The Revenue Department on 2026-10-21

ภ.พ.36 (P.P.36) self-assessed VAT remittance — filed online

VAT (ภาษีมูลค่าเพิ่ม) — reverse charge · Monthly · payment

15th of the month after the month ends Verified 2026-10-21
Who files
Payers who remit ภ.พ.36 through the Revenue Department's e-filing system, original and any additional form both online, in months with a qualifying payment.
Notes
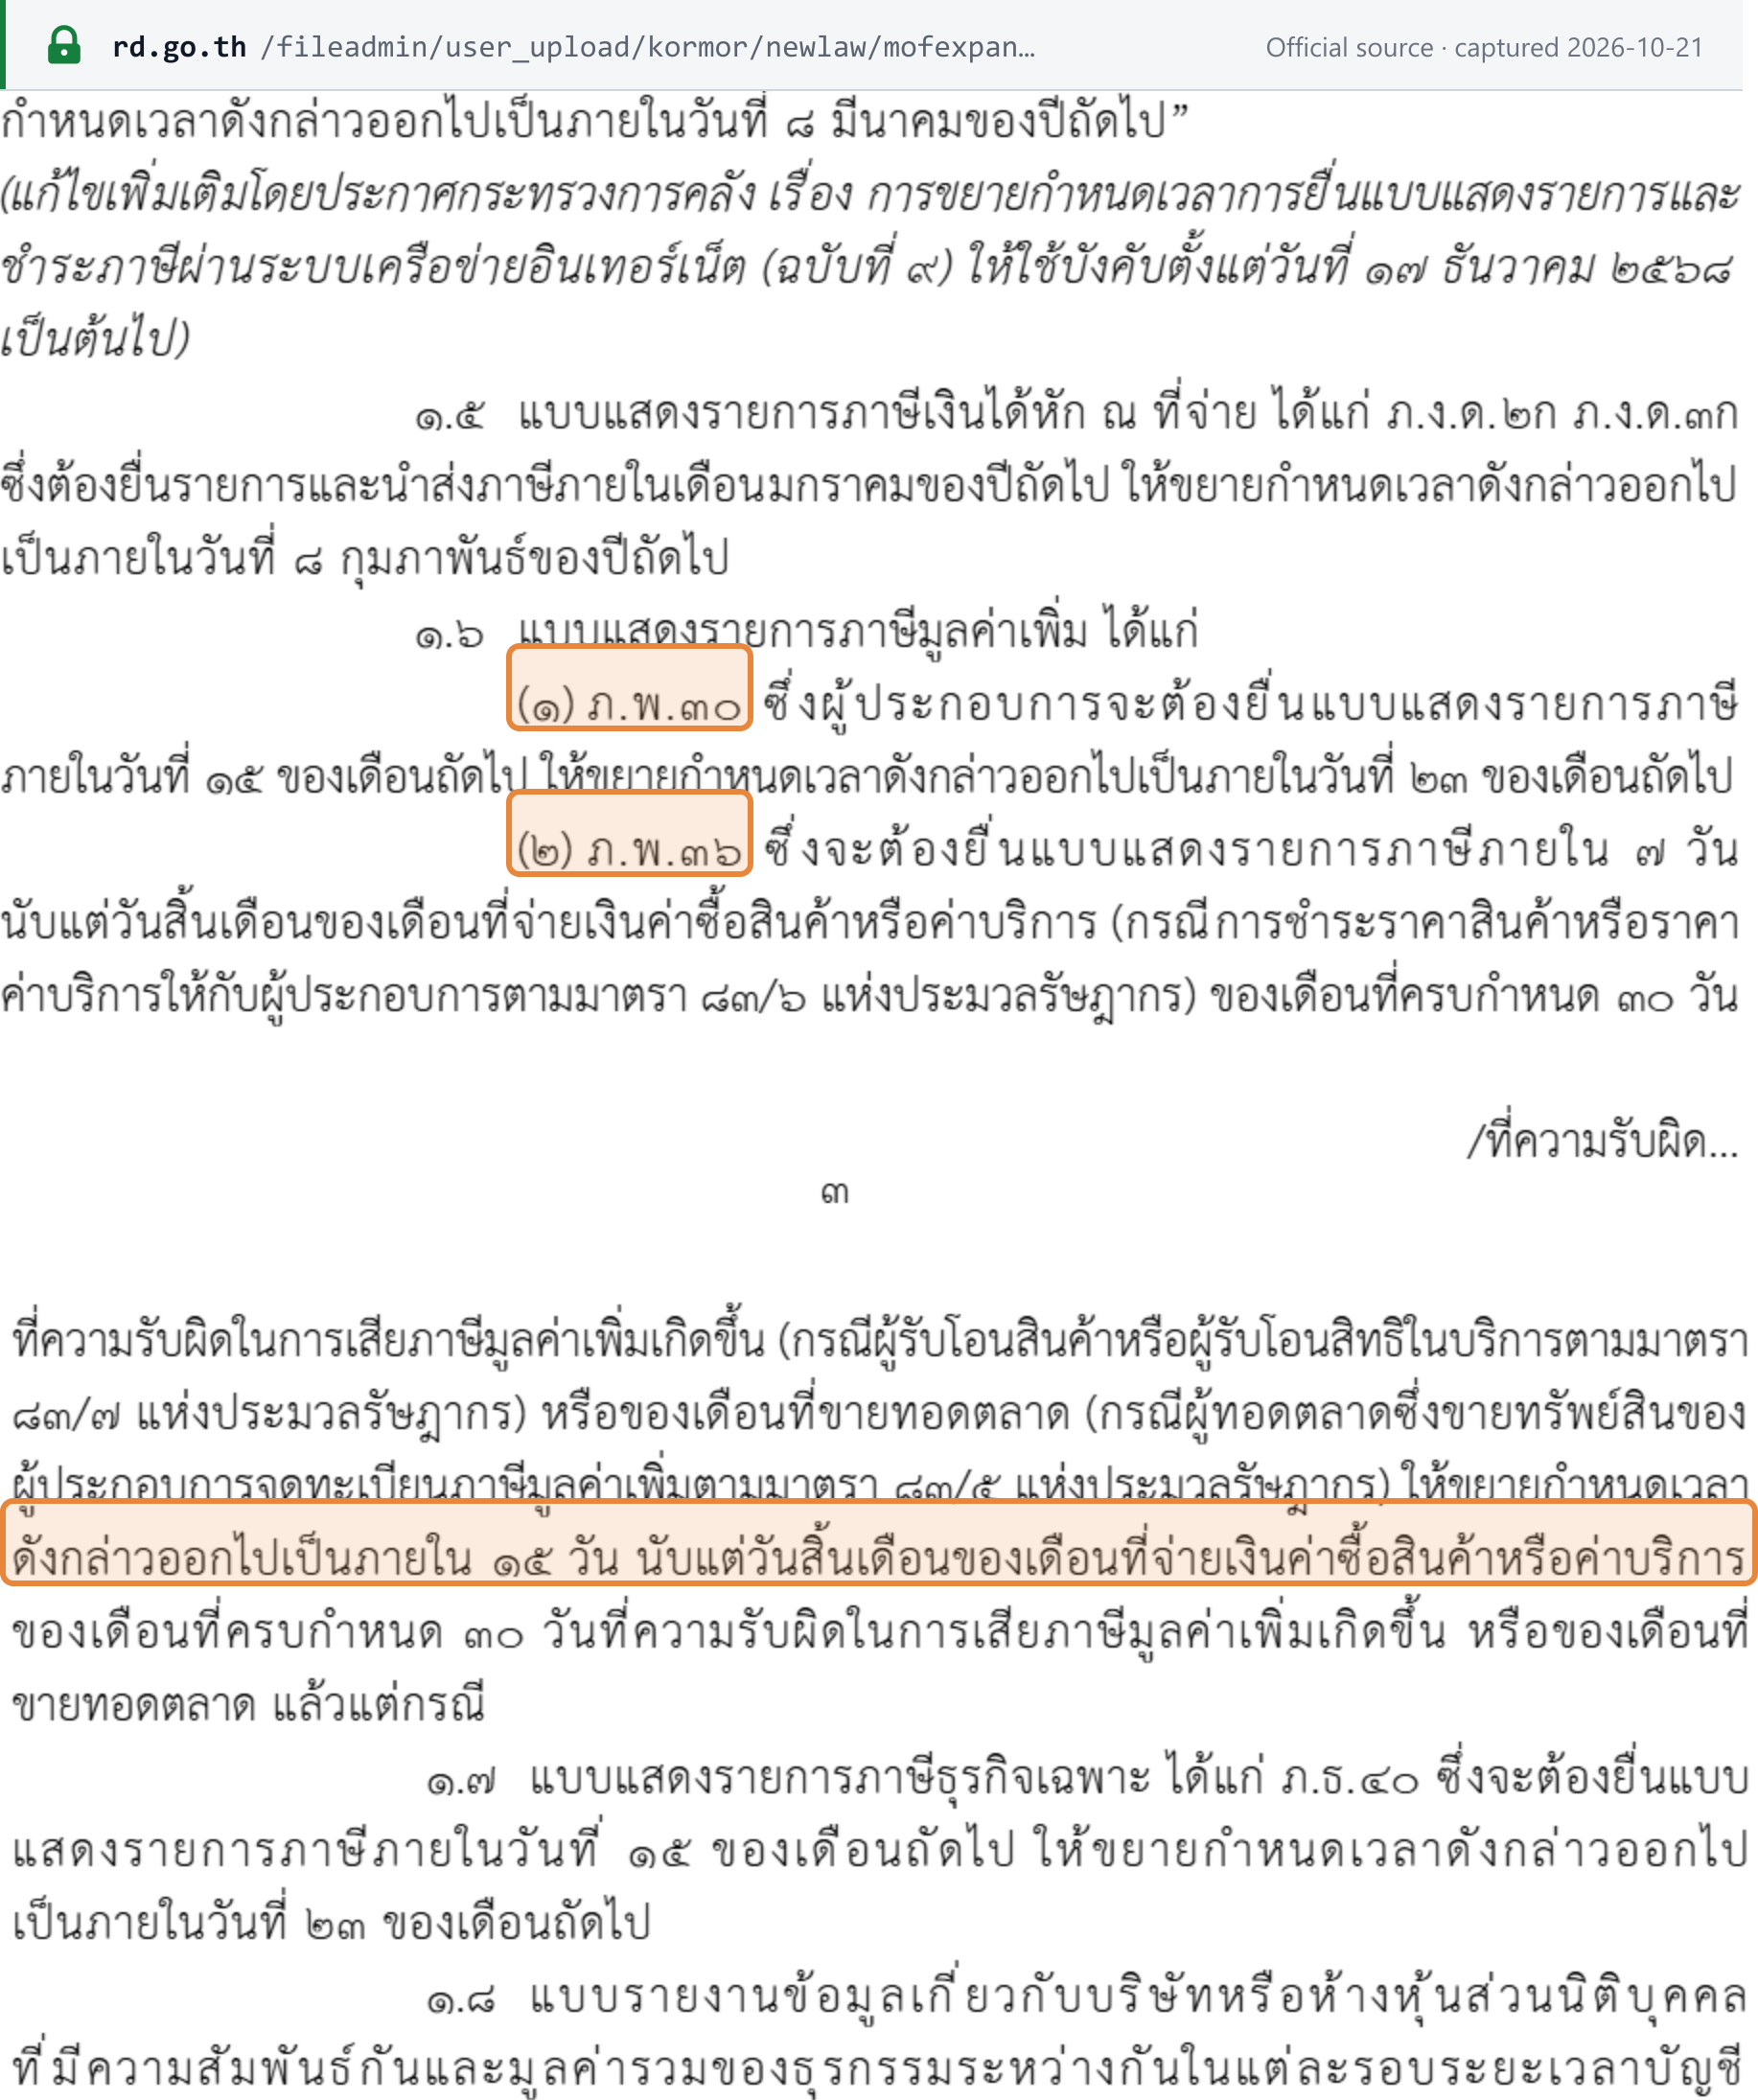
Online, the seven days become 15 days from the end of the payment month. This relief ceases with the same Ministry of Finance notification (No. 7, as amended by Nos. 8 and 9) that extends the VAT return: it reaches only forms due by 31 January 2027. Payments made in December 2026 are the last covered, due Friday 15 January 2027; payments from January 2027 onwards fall back to the 7th unless the notification is renewed.
Source
Ministry of Finance notification on extending filing and payment deadlines for internet filing (No. 7, as amended), item 1.6(2) Ministry of Finance, published by The Revenue Department
See the source text
“ให้ขยายกำหนดเวลาดังกล่าวออกไปเป็นภายใน ๑๕ วัน นับแต่วันสิ้นเดือนของเดือนที่จ่ายเงินค่าซื้อสินค้าหรือค่าบริการ”
Screenshot of Ministry of Finance, published by The Revenue Department showing the ภ.พ.36 (P.P.36) self-assessed VAT remittance — filed online deadline Open full size Captured from Ministry of Finance, published by The Revenue Department on 2026-10-21

P.P.30.9 VAT return and payment — non-resident e-service providers and platforms (VES)

VAT (ภาษีมูลค่าเพิ่ม) — e-services from abroad · Monthly · return filing

23rd of the month after the month ends Verified 2026-10-21
Who files
Non-resident electronic service providers and electronic platforms registered under the VES system because their income from e-services to Thai non-VAT-registered customers exceeds THB 1.8 million a year.
Notes
Filed and paid monthly through the VES portal only, by the 23rd of the following month, and moved to the next business day when the 23rd is not one. A return is due every month, including months with no Thai sales. Unlike the domestic online extension, this 23rd has no end date. Payment by wire must be completed by 3.30 pm Thai time on the due date.
Source
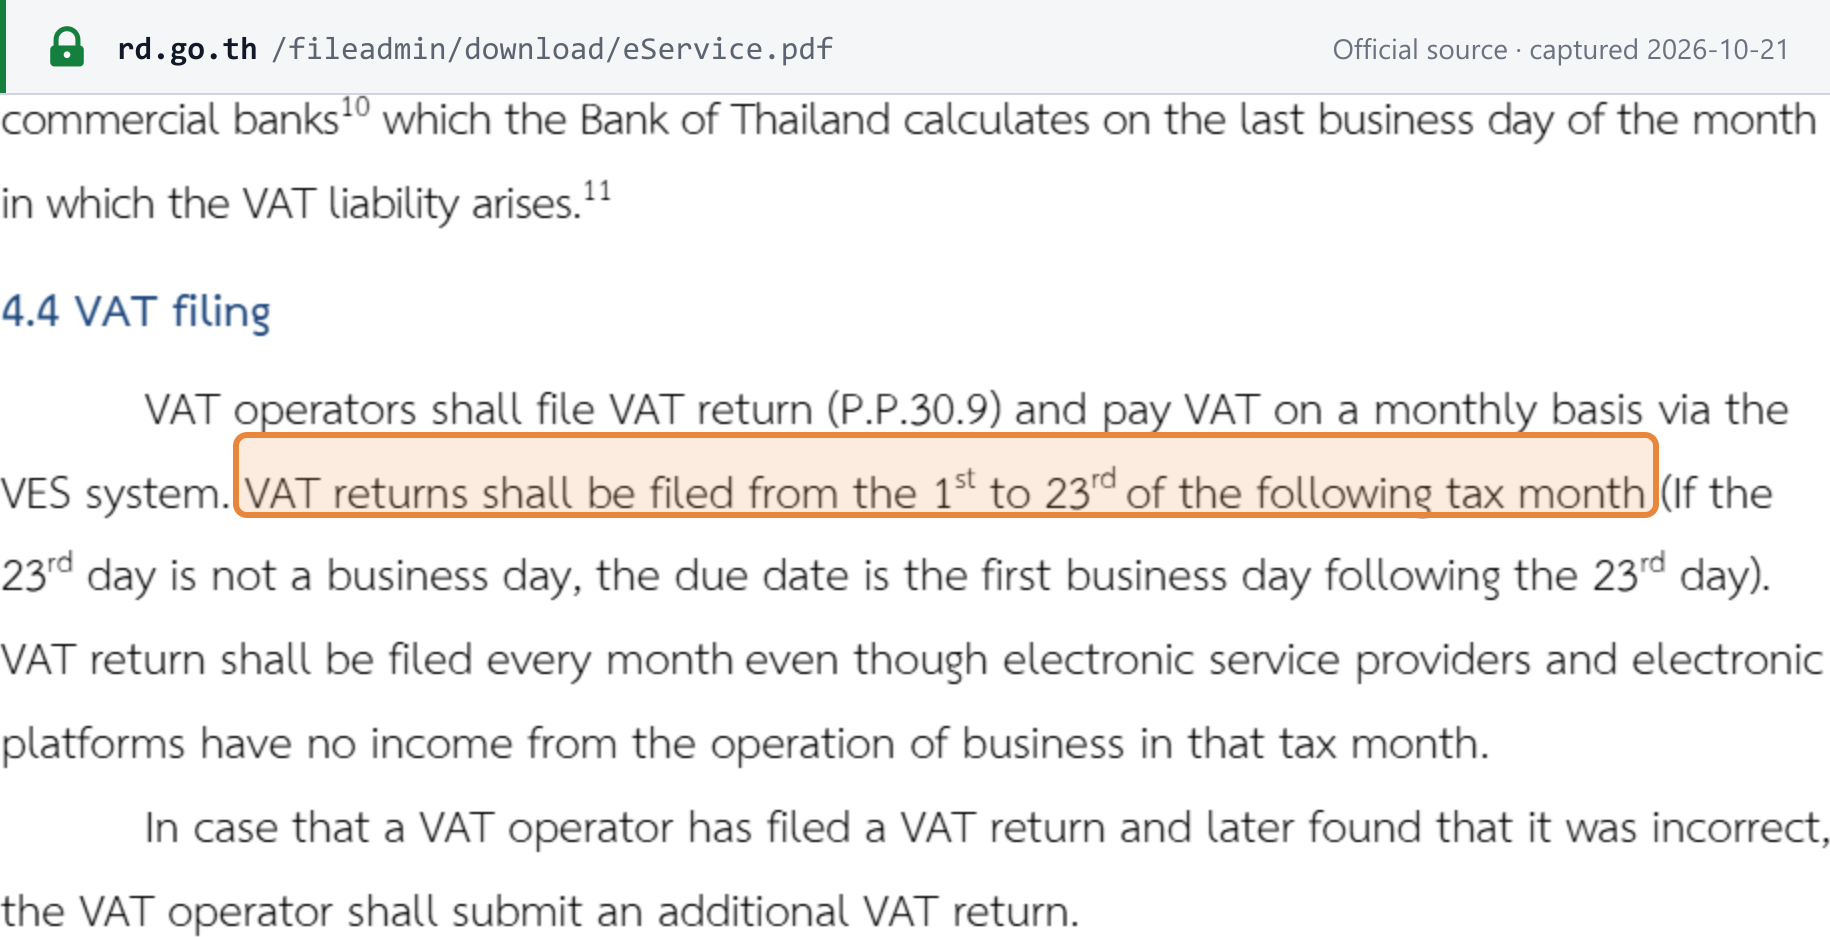
A Guide on VAT on Electronic Service (2nd edition, May 2022), section 4.4 VAT filing The Revenue Department (กรมสรรพากร)
See the source text
“VAT returns shall be filed from the 1st to 23rd of the following tax month (If the 23rd day is not a business day, the due date is the first business day following the 23rd day).”
Screenshot of The Revenue Department (กรมสรรพากร) showing the P.P.30.9 VAT return and payment — non-resident e-service providers and platforms (VES) deadline Open full size Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
ภ.ธ.40 (P.T.40) specific business tax return and payment — paper filing

Specific business tax (ภาษีธุรกิจเฉพาะ) · Monthly · return filing

15th of the month after the month ends Verified 2026-10-21
Who files
Businesses liable to specific business tax under Revenue Code s.91/2 instead of VAT, such as banking, finance and similar businesses, life insurance and pawnbroking, filing on paper. Sales of immovable property in a commercial or profit-making manner are not on this monthly return.
Notes
Specific business tax is a turnover tax charged in place of VAT on certain financial and property businesses. It is returned and paid monthly by the 15th, and a return is due even for a month with no receipts. Sales of immovable property in a commercial or profit-making manner are handled differently: the return is filed and the tax paid at the Land Office when the transfer is registered, so there is no monthly date.
Source
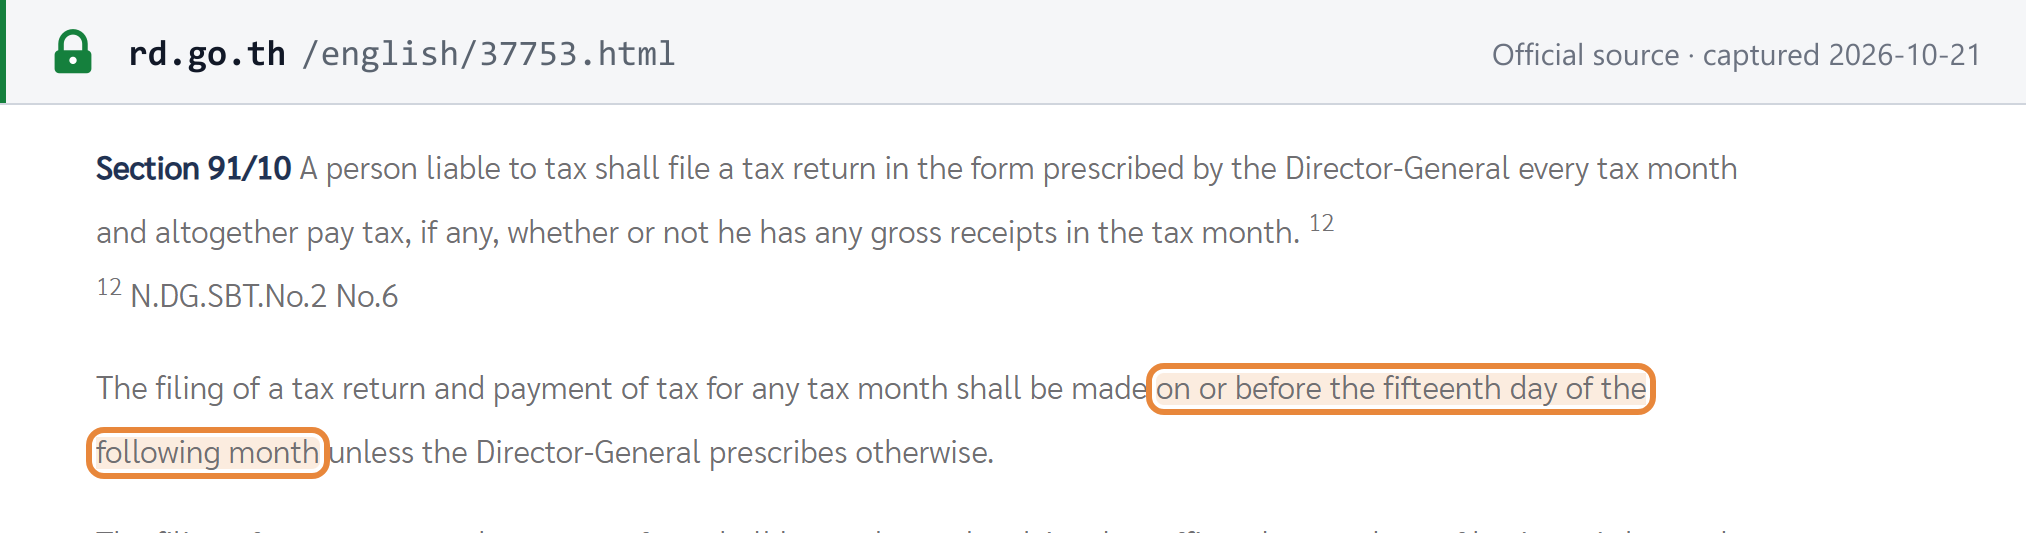
Revenue Code s.91/10 (RD English translation, Chapter 5 Specific Business Tax) The Revenue Department (กรมสรรพากร)
See the source text
“The filing of a tax return and payment of tax for any tax month shall be made on or before the fifteenth day of the following month unless the Director-General prescribes otherwise”
Screenshot of The Revenue Department (กรมสรรพากร) showing the ภ.ธ.40 (P.T.40) specific business tax return and payment — paper filing deadline Open full size Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
ภ.ธ.40 (P.T.40) specific business tax return and payment — filed online

Specific business tax (ภาษีธุรกิจเฉพาะ) · Monthly · return filing

23rd of the month after the month ends Verified 2026-10-21
Who files
Specific business tax filers who submit both the original and any additional return through the Revenue Department's e-filing system.
Notes
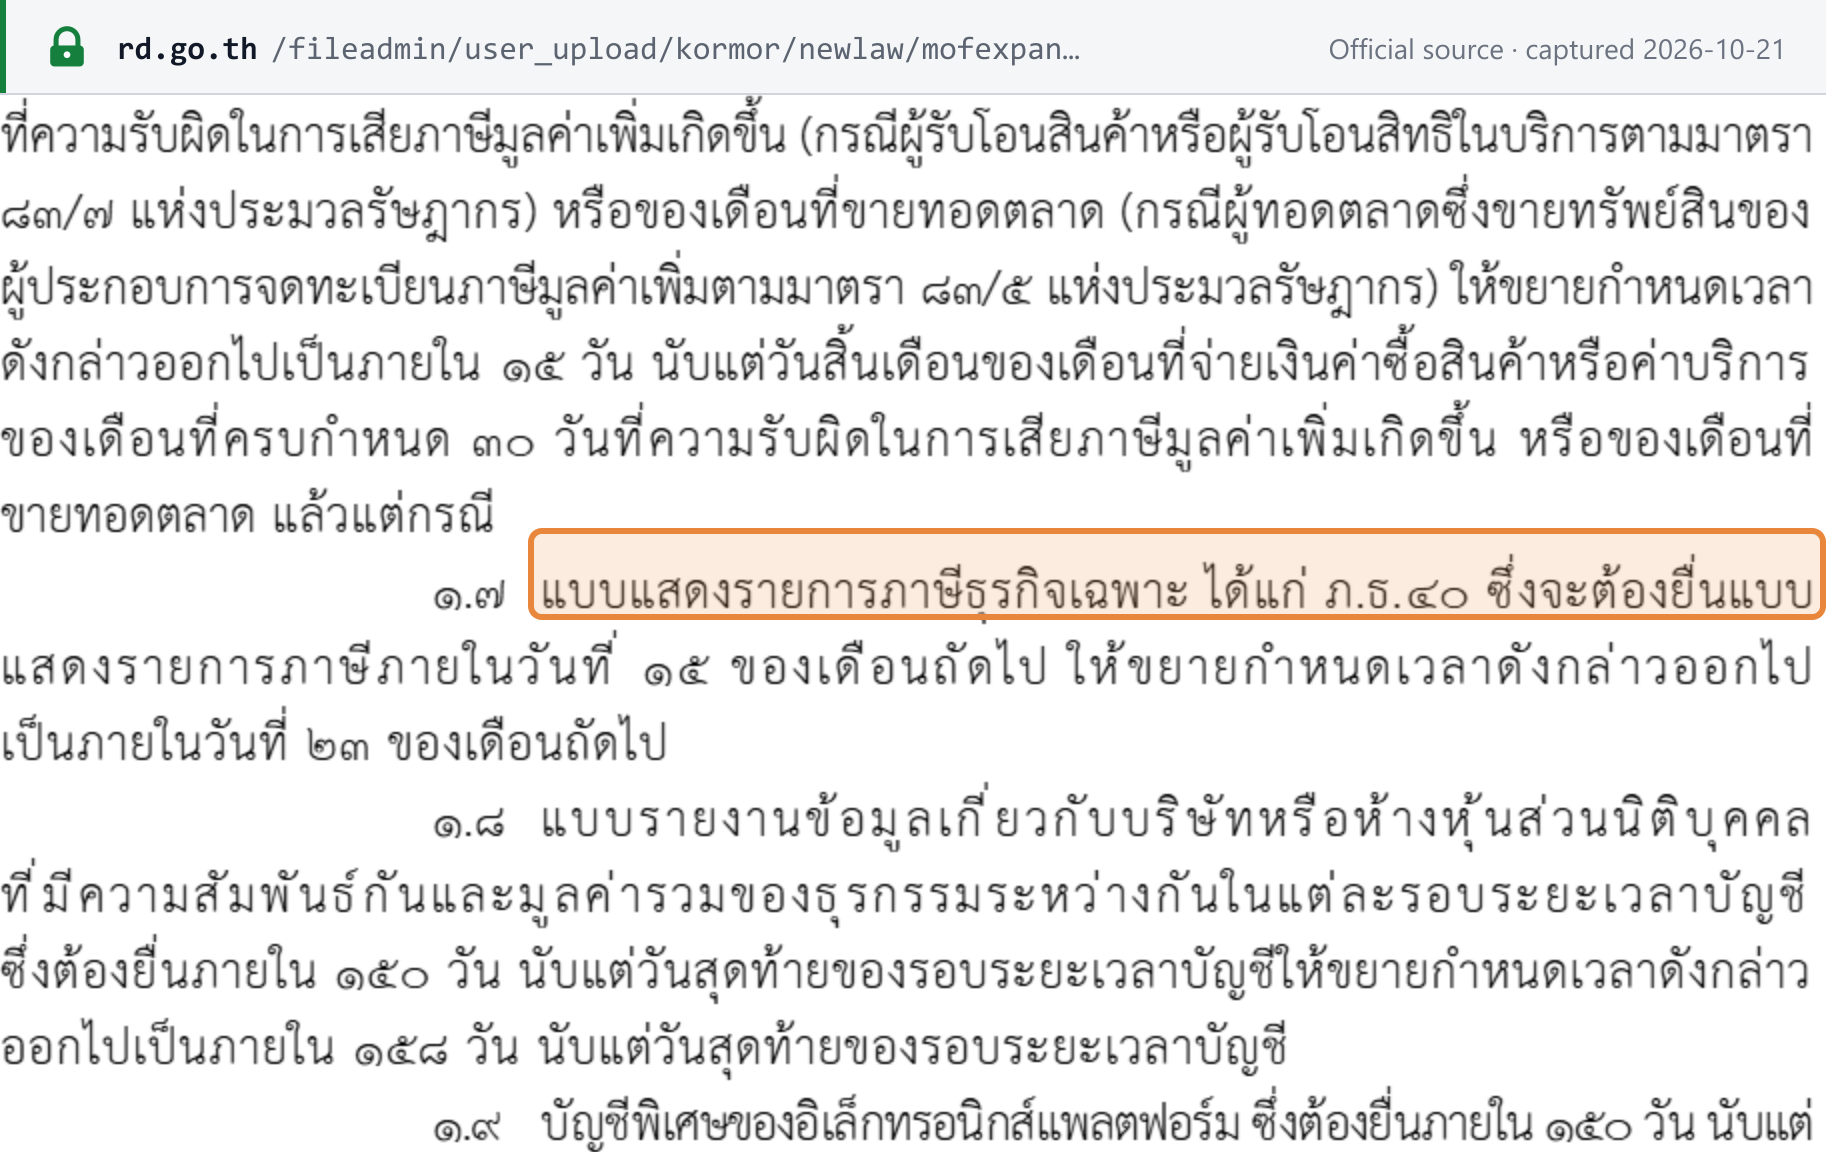
E-filers of specific business tax get eight more days, to the 23rd. That concession ceases for returns due after 31 January 2027, the end of the window set by Ministry of Finance notification No. 7 as amended. December 2026's return is the final one it covers, due Monday 25 January 2027 because the 23rd is a Saturday. Unless the notification is extended, February 2027 onwards is back to the 15th.
Source
Ministry of Finance notification on extending filing and payment deadlines for internet filing (No. 7, 12 January 2024, as amended by Nos. 8 and 9), item 1.7 Ministry of Finance, published by The Revenue Department
See the source text
“ภ.ธ.๔๐ ซึ่งจะต้องยื่นแบบแสดงรายการภาษีภายในวันที่ ๑๕ ของเดือนถัดไป ให้ขยายกำหนดเวลาดังกล่าวออกไปเป็นภายในวันที่ ๒๓ ของเดือนถัดไป”
Screenshot of Ministry of Finance, published by The Revenue Department showing the ภ.ธ.40 (P.T.40) specific business tax return and payment — filed online deadline Open full size Captured from Ministry of Finance, published by The Revenue Department on 2026-10-21

e-Tax Invoice and e-Receipt data report to the Revenue Department

VAT (ภาษีมูลค่าเพิ่ม) — e-Tax Invoice · Monthly · report / listing

15th of the month after the month ends Verified 2026-10-21
Who files
Only VAT registrants (and receipt issuers) who have opted to issue tax invoices or receipts electronically under Ministerial Regulation No. 384; Thailand has no e-invoicing mandate. Abbreviated tax invoices are excluded.
Notes
Issuing tax invoices electronically is optional in Thailand. Businesses that choose to do so must send the invoice and receipt data to the Revenue Department through its electronic system by the 15th of the following month. Abbreviated tax invoices are not reported. The date shown is the 15th itself: no source confirms that this report moves off a weekend, so treat the 15th as firm.
Source
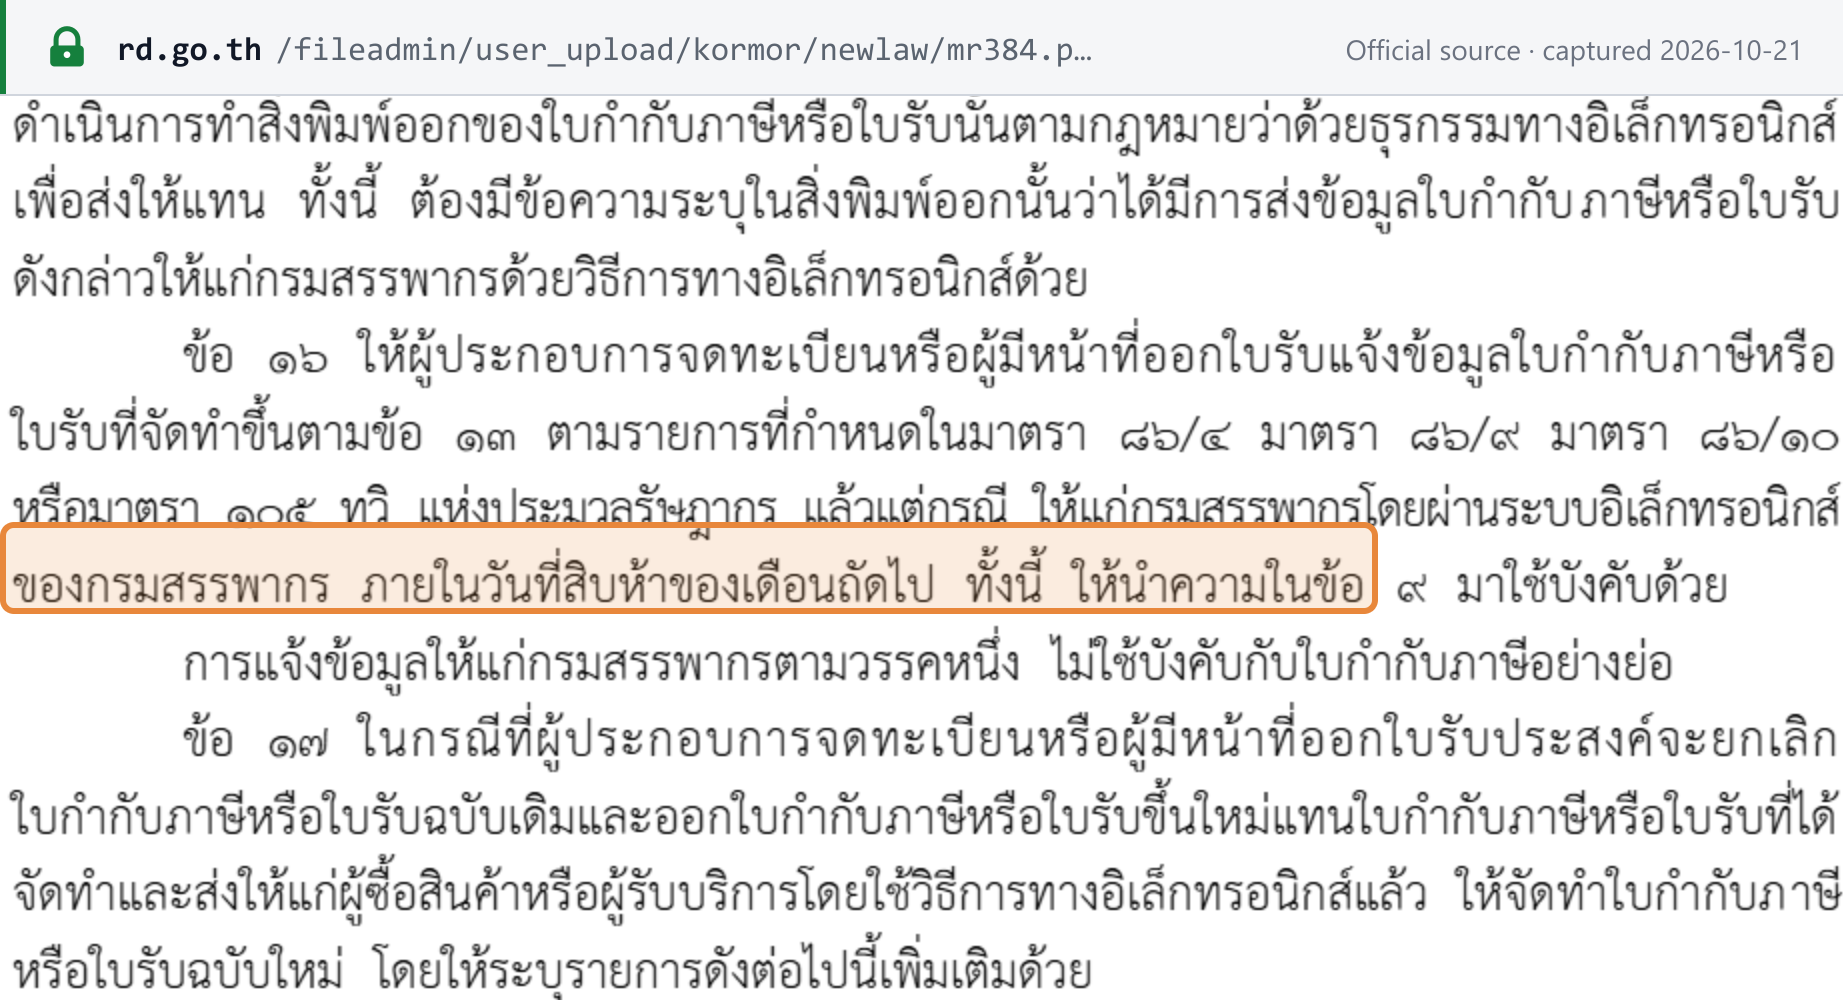
Ministerial Regulation No. 384 (B.E. 2565, 2022) on electronic tax invoices and receipts, clause 16 Ministry of Finance (Royal Gazette vol. 139 part 45 ก), published by The Revenue Department
See the source text
“ให้แก่กรมสรรพากรโดยผ่านระบบอิเล็กทรอนิกส์ของกรมสรรพากร ภายในวันที่สิบห้าของเดือนถัดไป”
Screenshot of Ministry of Finance (Royal Gazette vol. 139 part 45 ก), published by The Revenue Department showing the e-Tax Invoice and e-Receipt data report to the Revenue Department deadline Open full size Captured from Ministry of Finance (Royal Gazette vol. 139 part 45 ก), published by The Revenue Department on 2026-10-21

VAT registration when turnover exceeds THB 1.8 million

VAT (ภาษีมูลค่าเพิ่ม) · One-off · registration

within 30 days of the date annual turnover first exceeds THB 1.8 million Verified 2026-10-21
Who files
Businesses selling goods or services in Thailand whose annual turnover exceeds the small-business ceiling of THB 1.8 million (Royal Decree No. 432).
Notes
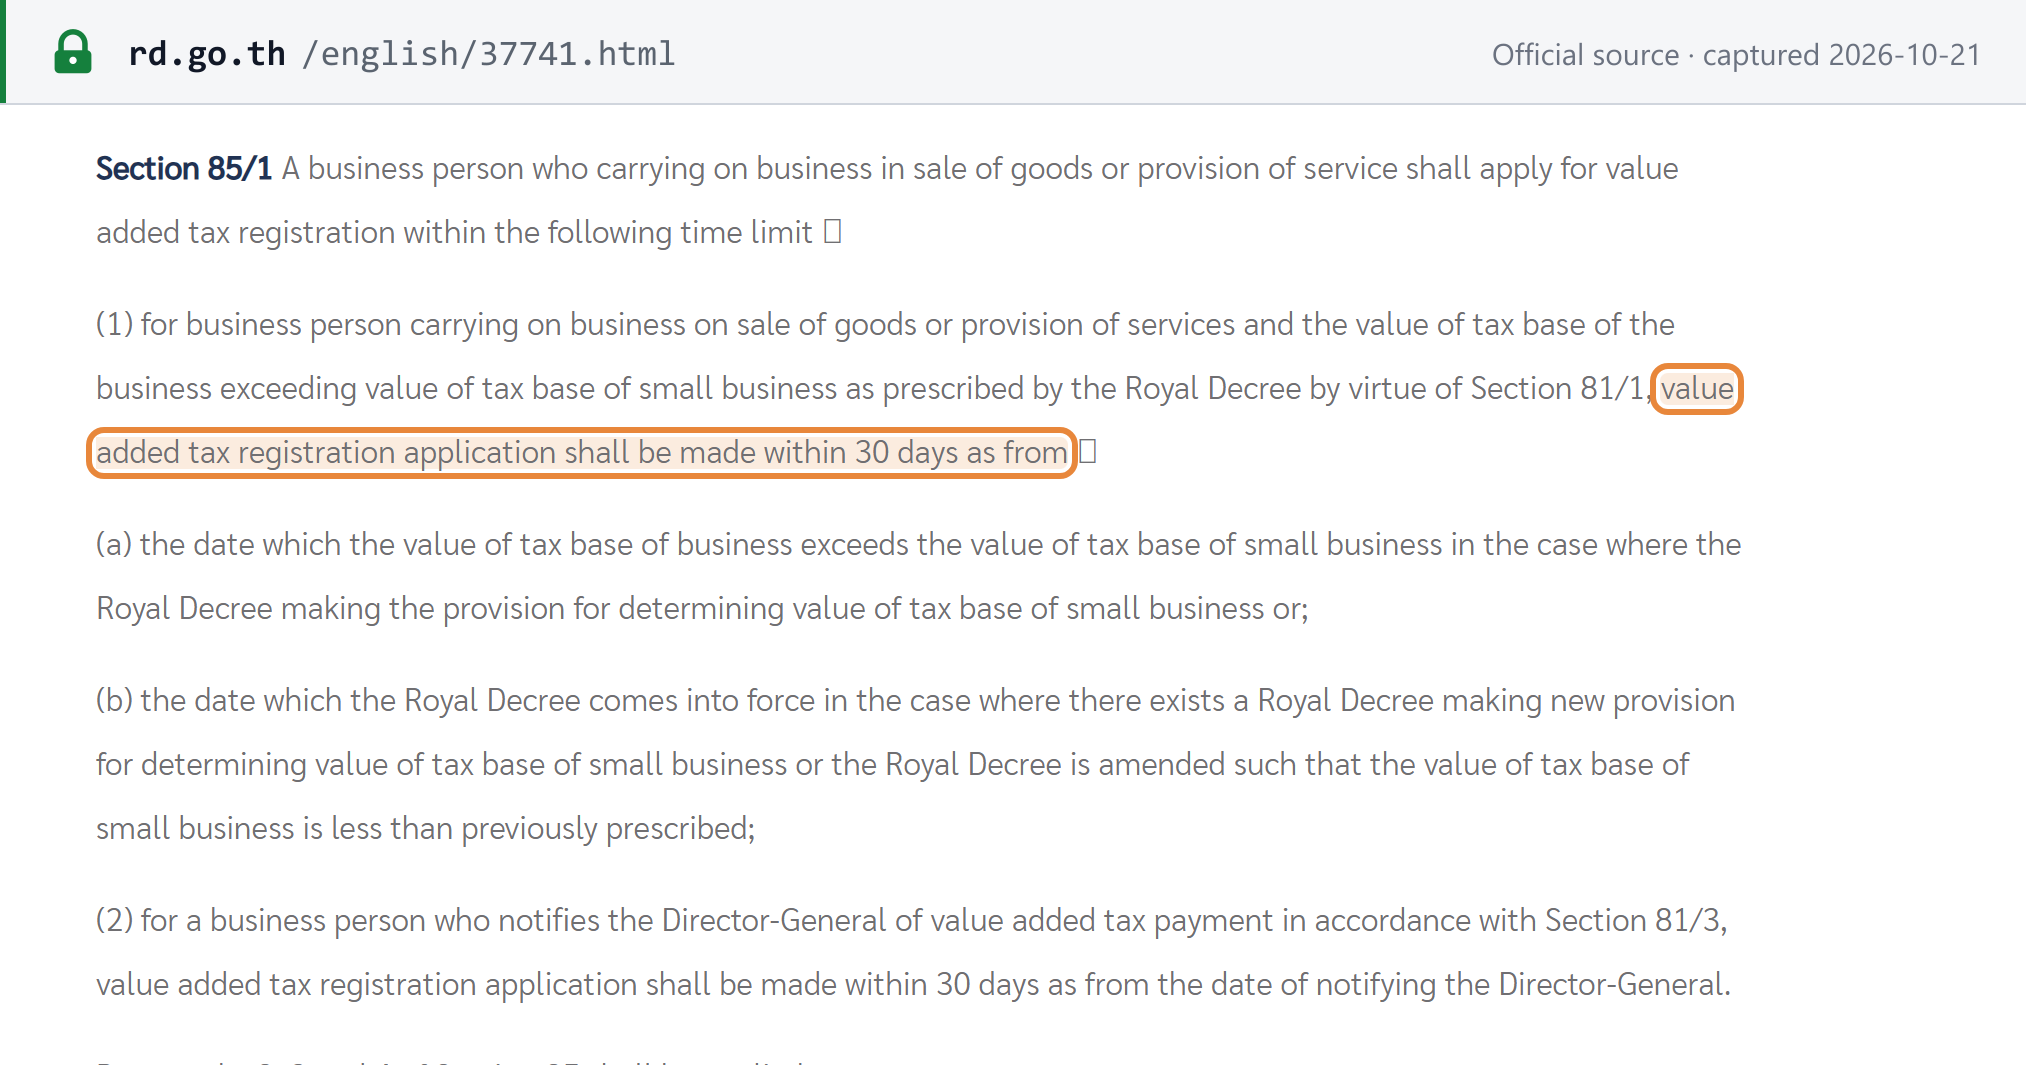
Apply within 30 days of the day turnover passes THB 1.8 million. A business below the ceiling that elects into VAT must also apply within 30 days of notifying the Director-General. A new business may register before it starts trading, but that is a right rather than a deadline.
Source
Revenue Code s.85/1 (RD English translation) The Revenue Department (กรมสรรพากร)
See the source text
“value added tax registration application shall be made within 30 days as from”
Screenshot of The Revenue Department (กรมสรรพากร) showing the VAT registration when turnover exceeds THB 1.8 million deadline Open full size Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
VES registration for non-resident e-service providers and platforms

VAT (ภาษีมูลค่าเพิ่ม) — e-services from abroad · One-off · registration

within 30 days of the day income from e-services to Thai non-VAT-registered customers exceeds THB 1.8 million Verified 2026-10-21
Who files
Non-resident e-service providers and electronic platforms whose income from e-services to Thai customers who are not VAT-registered exceeds THB 1.8 million a year.
Notes
Registration is online through the VES portal, within 30 days of the day such income crosses THB 1.8 million in the year. Sales to VAT-registered Thai businesses do not count towards it: those customers self-assess instead.
Source
A Guide on VAT on Electronic Service (2nd edition, May 2022), VAT registration The Revenue Department (กรมสรรพากร)
See the source text
“within 30 days from the day when income from such service exceeds 1.8 million Baht.”
Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
Specific business tax registration

Specific business tax (ภาษีธุรกิจเฉพาะ) · One-off · registration

within 30 days of the first day of operating the business Verified 2026-10-21
Who files
Anyone starting a business subject to specific business tax under s.91/2, unless exempt under s.91/3 or excused from registration under s.91/13.
Notes
There is no turnover threshold to wait for: a business within the tax applies within 30 days of the day it starts operating.
Source
Revenue Code s.91/12 (RD English translation, Chapter 5 Specific Business Tax) The Revenue Department (กรมสรรพากร)
See the source text
“He shall file an application for registration within 30 days from the first day of operation of the business”
Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
Notice of ceasing a specific business tax business

Specific business tax (ภาษีธุรกิจเฉพาะ) · One-off · registration

within 15 days of the date the business ceases Verified 2026-10-21
Who files
Every business registered for specific business tax that ceases operating.
Notes
Notify the Revenue Department within 15 days of ceasing a business subject to specific business tax.
Source
Revenue Code s.91/21(3) (RD English translation, Chapter 5 Specific Business Tax), applying s.85/15 The Revenue Department (กรมสรรพากร)
See the source text
“part 9, Value Added Tax Registration, sections 85/4, 85/5, 85/6, 85/7, 85/8, 85/9, 85/12, 85/13, 85/14, 85/15”
Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
Notice of ceasing business (VAT deregistration)

VAT (ภาษีมูลค่าเพิ่ม) · One-off · registration

within 15 days of the date the business ceases Verified 2026-10-21
Who files
Every VAT registrant that ceases its business.
Notes
Notify the Revenue Department, at the office where you registered, within 15 days of stopping business, and hand back the VAT registration certificate at the same time. Non-resident e-service providers registered under VES notify through the VES portal within the same 15 days.
Source
Revenue Code s.85/15 (consolidated Thai text) The Revenue Department (กรมสรรพากร)
See the source text
“ให้ผู้ประกอบการจดทะเบียนนั้นแจ้งการเลิกกิจการตามแบบที่อธิบดีกำหนด ณ สถานที่ที่ได้จดทะเบียนภาษีมูลค่าเพิ่มไว้ภายในสิบห้าวันนับจากวันเลิกประกอบกิจการ”
Screenshot of The Revenue Department (กรมสรรพากร) showing the Notice of ceasing business (VAT deregistration) deadline Open full size Captured from The Revenue Department (กรมสรรพากร) on 2026-10-21
Thai VAT and specific business tax run on calendar months. Return and payment go together: by the 15th of the following month on paper, or the 23rd when filed online. The online extra eight days are granted by a Ministry of Finance notification that covers only returns due up to 31 January 2027, so from the February 2027 deadlines the 15th applies to everyone unless a further notification renews it. Non-resident e-service providers file by the 23rd under a separate, open-ended notification. A return or payment deadline that falls on a weekend or government holiday moves to the next working day, with no penalty or surcharge. Excise tax, administered by the Excise Department, is not covered here; nor are income-tax withholding returns (the PND forms).

“วันสุดท้ายตรงกับวันหยุดทำการของทางราชการ ให้นับวันที่เริ่มทำการใหม่ต่อจากวันที่หยุดทำการนั้นเป็นวันสุดท้ายของระยะเวลา ตามมาตรา 193/8 แห่งประมวลกฎหมายแพ่งและพาณิชย์ โดยไม่ต้องเสียเบี้ยปรับและเงินเพิ่มแต่อย่างใด”
Revenue Department Order No. ป.117/2545 (28 October 2002) on counting time limits, cl. 1 — The Revenue Department (กรมสรรพากร), captured 2026-10-21

What this calendar does not list

  • Not applicable Annual or reconciliation return — Thailand has no annual VAT or specific business tax return. Revenue Code Chapter 4 (VAT, ss. 77–90/5) provides only the monthly return under s.83, and Chapter 5 (SBT, s.91) only the monthly return under s.91/10; no annual reconciliation return appears in either (RD consolidated text at rd.go.th/5207.html and /5204.html, checked 21 October 2026).
  • Not applicable Recapitulative listing — No sales, purchase or recapitulative listing is filed. Revenue Code s.87 requires VAT registrants to keep output-tax, input-tax and stock reports, not to submit them (RD English text, rd.go.th/english/37747.html, checked 21 October 2026). The only periodic data submission is the e-Tax Invoice data report, which answers the e-invoicing slot.

About this calendar

Which Thailand tax deadlines does this calendar cover?

13 recurring indirect-tax obligations — VAT (ภาษีมูลค่าเพิ่ม) and Specific business tax (ภาษีธุรกิจเฉพาะ) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-21). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.