Türkiye compliance calendar

11 recurring KDV (Katma Değer Vergisi, ÖTV (Özel Tüketim Vergisi, KDV and all taxes administered under the Tax Procedure Law (VUK) and e-Arşiv (electronic archive invoices) obligations — returns, payments and listings — each with its due rule and official source, plus the dates new Türkiye rules take effect.

Mon
Tue
Wed
Thu
Fri
Sat
Sun
26
27
28
29
30
31
1
2
3
4
5
6
Return filing Report / listing Law change takes effect

Dates already include the weekend and public-holiday shift where Türkiye applies one — 8 of 11 obligations here do. The rest stand as computed, and each obligation's notes say which applies to it and why. Confirm against the linked official source before relying on a date.

Recurring obligations, with sources

Each deadline cites the official text that states it and the date we last verified it.

1 No.lu KDV Beyannamesi (monthly) — return and payment

KDV (Katma Değer Vergisi — VAT) · Monthly · return filing

28th of the month after the month ends Verified 2026-10-21
Who files
Every KDV taxpayer taxed under the real (gerçek usul) procedure, other than the quarterly groups; there is no KDV registration threshold
Notes
Every real-procedure KDV taxpayer files monthly and pays the tax due on the same day. A return is required even for a month with no taxable transactions. The 28th has applied since December 2022; the law itself still says the 24th for filing and the 26th for payment, so guidance quoting those days is out of date. When the 28th falls on a weekend or a full-day holiday the deadline moves to the next working day: the January 2027 return is due on Monday 1 March 2027, because 28 February is a Sunday. Withheld and reverse-charge KDV goes on the separate 2 No.lu return, due by the 25th.
Source
Vergi Usul Kanunu Sirküleri 149 (VUK-149/2022-12, 22/12/2022) — KDV return and payment deadline extended to the 28th Gelir İdaresi Başkanlığı (GİB)
See the source text
“Katma Değer Vergisi Beyannamelerinin verilme ve bu beyannameler üzerine tahakkuk eden vergilerin ödeme süreleri, ilgili vergilendirme dönemini takip eden ayın 28 inci günü sonuna kadar uzatılmıştır.”
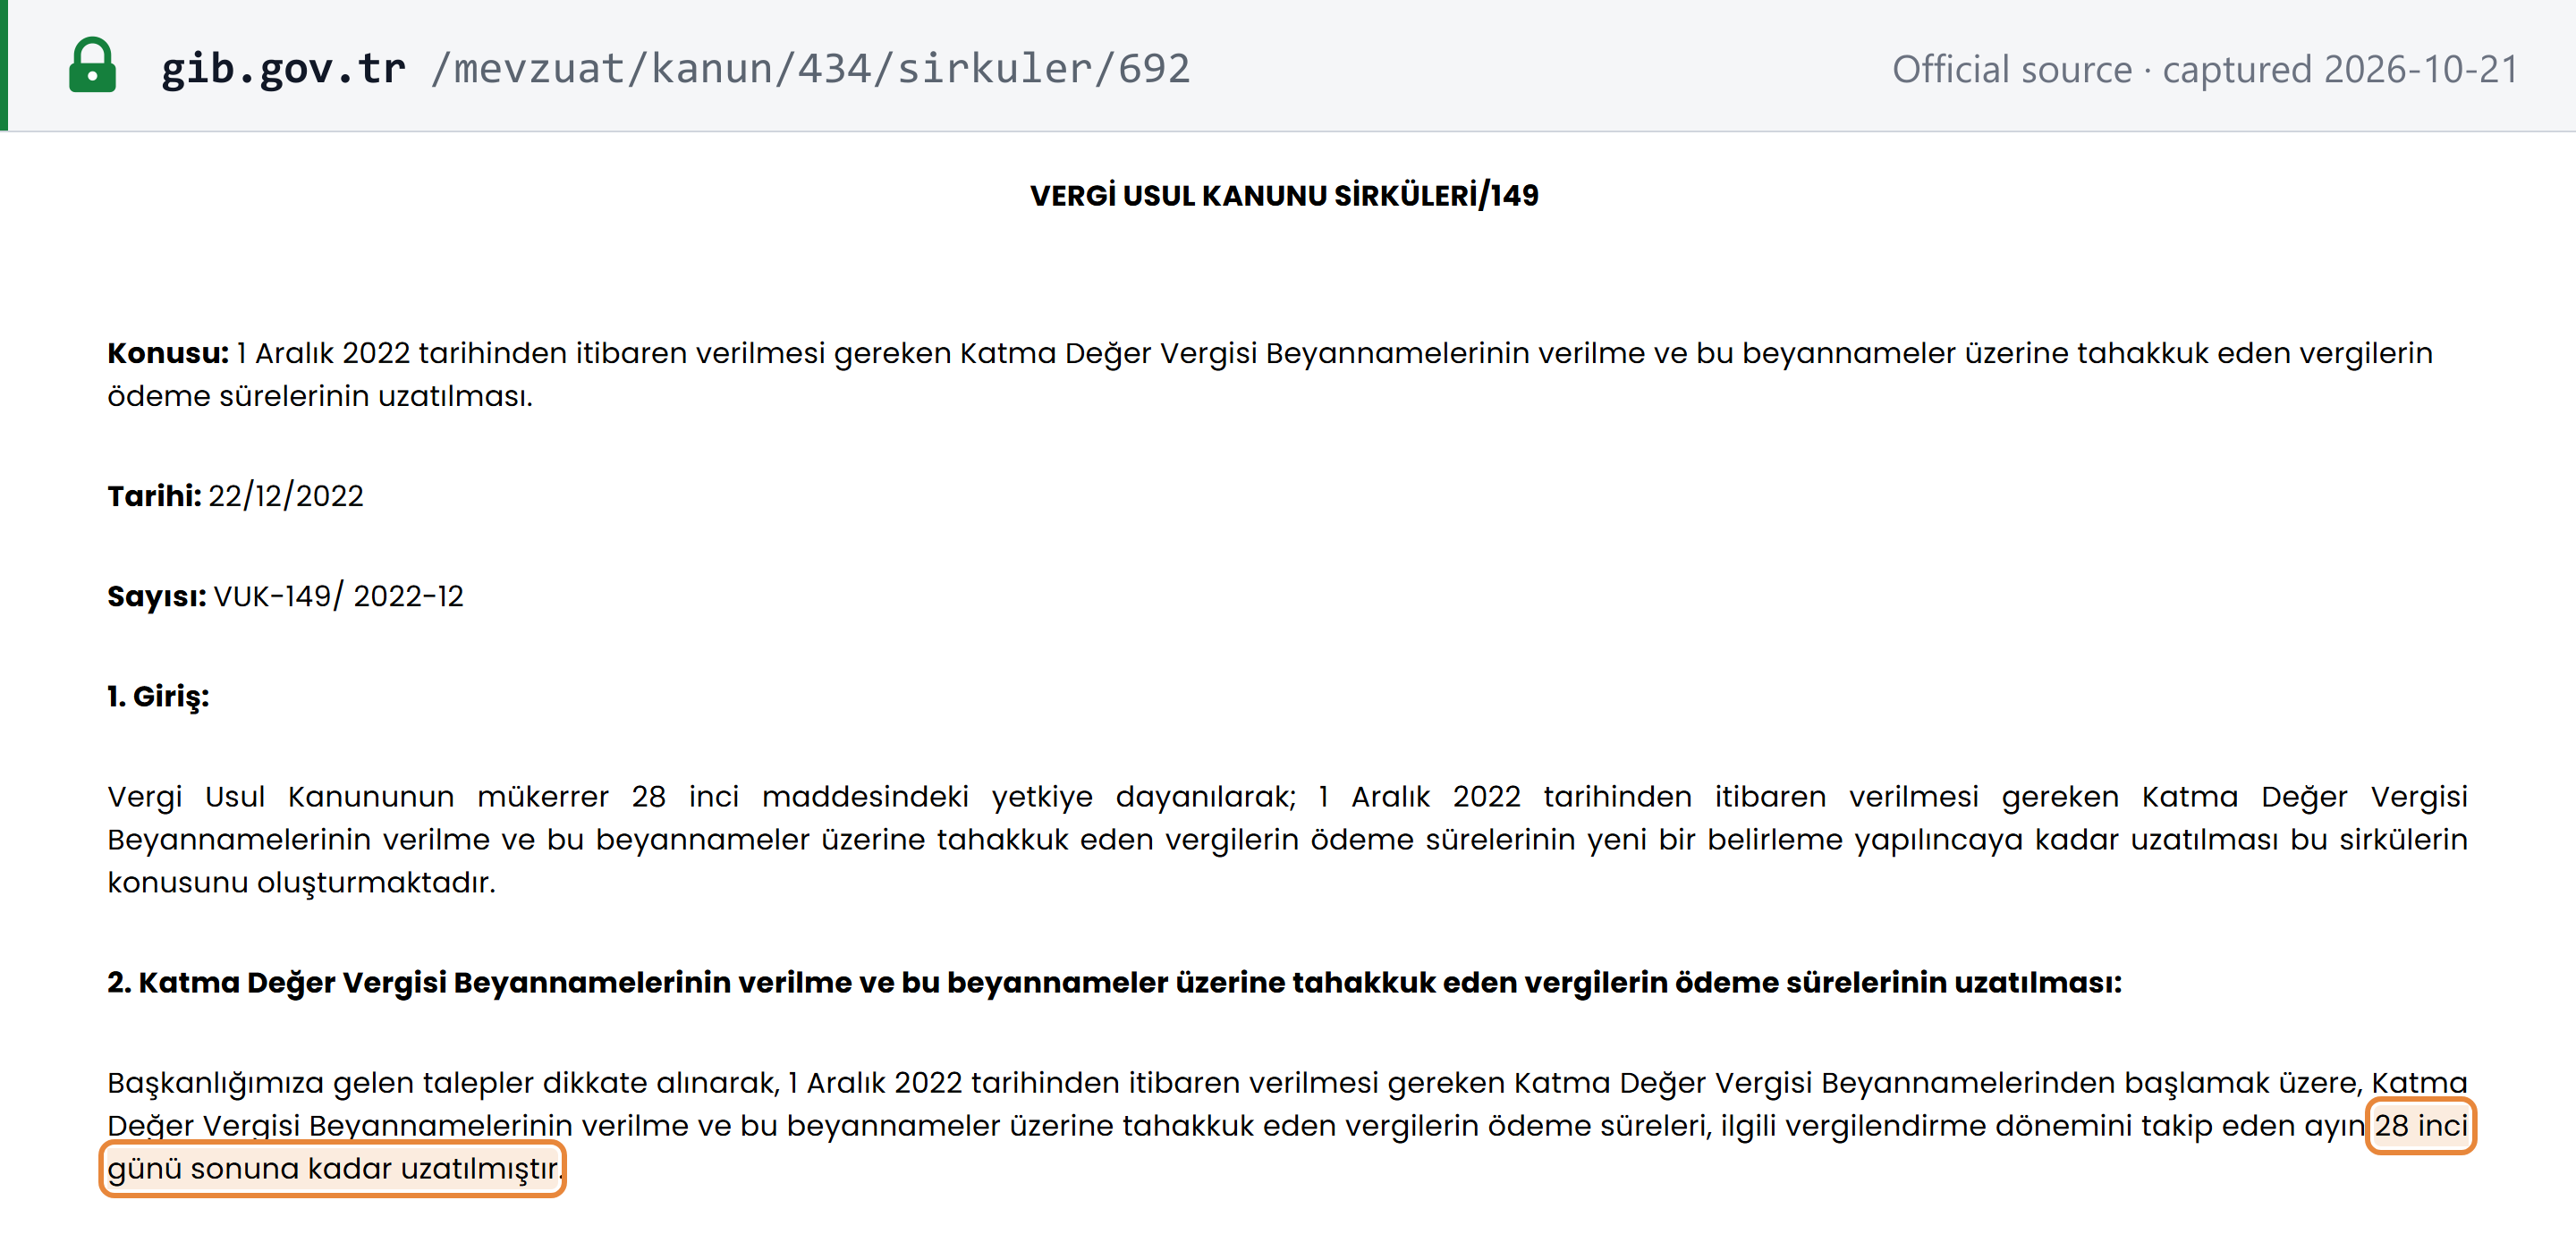
Screenshot of Gelir İdaresi Başkanlığı (GİB) showing the 1 No.lu KDV Beyannamesi (monthly) — return and payment deadline Open full size Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21
1 No.lu KDV Beyannamesi (quarterly) — return and payment

KDV (Katma Değer Vergisi — VAT) · Quarterly · return filing

28th of the month after the quarter ends Verified 2026-10-21
Who files
Housing-construction cooperatives; business-account-basis taxpayers whose only activity is international freight and passenger transport, intercity freight transport or urban freight transport; simplified-procedure (basit usul) taxpayers who have waived the KDV exemption
Notes
Three groups file on calendar quarters rather than monthly: housing-construction cooperatives (even in quarters with no activity), taxpayers on the business-account basis whose only activity is international freight or passenger transport, or intercity or urban freight transport (intercity and urban passenger carriers file monthly), and simplified-procedure taxpayers who have waived their KDV exemption. You must tell your tax office you belong to a quarterly group before the filing deadline. Return and payment are due on 28 January, 28 April, 28 July and 28 October, moved to the next working day where needed. Simplified-procedure taxpayers who keep the exemption file no KDV return at all.
Source
Vergi Usul Kanunu Sirküleri 149 (VUK-149/2022-12, 22/12/2022) — KDV return and payment deadline extended to the 28th Gelir İdaresi Başkanlığı (GİB)
See the source text
“1 Aralık 2022 tarihinden itibaren verilmesi gereken Katma Değer Vergisi Beyannamelerinden başlamak üzere, Katma Değer Vergisi Beyannamelerinin verilme ve bu beyannameler üzerine tahakkuk eden vergilerin ödeme süreleri, ilgili vergilendirme dönemini takip eden ayın 28 inci günü sonuna kadar uzatılmıştır.”
Screenshot of Gelir İdaresi Başkanlığı (GİB) showing the 1 No.lu KDV Beyannamesi (quarterly) — return and payment deadline Open full size Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21
2 No.lu KDV Beyannamesi (withholding and reverse charge) — return and payment

KDV (Katma Değer Vergisi — VAT) · Monthly · return filing

25th of the month after the month ends Verified 2026-10-21
Who files
Withholding agents (KDV tevkifatı) and Turkish recipients liable as tax-responsible persons (sorumlu sıfatıyla) on supplies by non-residents, in any month with something to declare
Notes
Withholding agents and businesses accounting for KDV on services bought from non-residents file the 2 No.lu return and pay by the 25th of the following month. Unlike the main return, nothing is filed for a month with no withholding. For the June period only, the July financial holiday under Law 5604 lets the payment run to the end of the working day after the filing deadline; GİB's calendar showed 28 July in both 2025 and 2026. The July date shown here is the filing deadline, which is also a safe day to pay.
Source
Vergi Usul Kanunu Sirküleri 164 (VUK-164/2024-2, 10/2/2024) — withholding agents’ KDV returns and payment by the 25th Gelir İdaresi Başkanlığı (GİB)
See the source text
“vergi kesintisi yapmakla sorumlu tutulanlar tarafından vergilendirme dönemini takibeden ayın 21 inci günü akşamına kadar verilip beyanname verecekleri ayın 23 üncü günü akşamına kadar ödenmesi gereken Katma Değer Vergisi Beyannamelerinin verilme ve bu beyannameler üzerine tahakkuk eden vergilerin ödeme süreleri, ilgili vergilendirme dönemini takip eden ayın 25 inci günü sonuna kadar uzatılmıştır.”
Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21
3 No.lu KDV Beyannamesi (non-resident electronic-service suppliers) — return and payment

KDV (Katma Değer Vergisi — VAT) · Monthly · return filing

28th of the month after the month ends Verified 2026-10-21
Who files
Suppliers with no residence, place of business or registered office in Türkiye that supply electronic services to Turkish consumers who are not KDV taxpayers
Notes
A supplier with no residence or business in Türkiye that sells electronic services to Turkish consumers files this return monthly in Turkish lira through the internet tax office, and pays on the same day. No return is needed for a month with nothing to declare. Before its first return the supplier must register using the form at digitalservice.gib.gov.tr; no number of days is set, only that registration comes first. Some official texts still show the 24th and the 26th, which the 28th has replaced.
Source
Vergi Usul Kanunu Sirküleri 149 (VUK-149/2022-12, 22/12/2022) — KDV return and payment deadline extended to the 28th Gelir İdaresi Başkanlığı (GİB)
See the source text
“Katma Değer Vergisi Beyannamelerinin verilme ve bu beyannameler üzerine tahakkuk eden vergilerin ödeme süreleri, ilgili vergilendirme dönemini takip eden ayın 28 inci günü sonuna kadar uzatılmıştır.”
Screenshot of Gelir İdaresi Başkanlığı (GİB) showing the 3 No.lu KDV Beyannamesi (non-resident electronic-service suppliers) — return and payment deadline Open full size Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21
4 No.lu KDV Beyannamesi (revenue-based taxation) — return and payment

KDV (Katma Değer Vergisi — VAT) · Monthly · return filing

28th of the month after the month ends Verified 2026-10-21
Who files
Taxpayers who have opted into revenue-based taxation (hasılat esaslı vergilendirme)
Notes
For taxpayers who have opted into revenue-based taxation (hasılat esaslı vergilendirme), the KDV worked out under that method is declared on the 4 No.lu return and paid by the 28th of the following month. The published guidance text still gives the 24th for filing and the 26th for payment; the tax administration's own deadline table applies the 28th to this return as well.
Source
Vergi Usul Kanunu Sirküleri 149 (VUK-149/2022-12, 22/12/2022) — KDV return and payment deadline extended to the 28th Gelir İdaresi Başkanlığı (GİB)
See the source text
“Katma Değer Vergisi Beyannamelerinin verilme ve bu beyannameler üzerine tahakkuk eden vergilerin ödeme süreleri, ilgili vergilendirme dönemini takip eden ayın 28 inci günü sonuna kadar uzatılmıştır.”
Screenshot of Gelir İdaresi Başkanlığı (GİB) showing the 4 No.lu KDV Beyannamesi (revenue-based taxation) — return and payment deadline Open full size Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21

ÖTV Beyannamesi, List (I) fuel products — second half-month (16th to month end)

ÖTV (Özel Tüketim Vergisi — special consumption tax) · Monthly · return filing

10th of the month after the month ends Verified 2026-10-21
Who files
Manufacturers and importers of the petroleum products and natural gas on ÖTV List (I), and other persons liable for ÖTV on those goods
Notes
Fuel products on List I have two ÖTV periods a month. This date is for the second half, the 16th to the end of the month, declared and paid by the 10th of the next month; a period shown as May 2026 means 16–31 May. The first half, the 1st to the 15th, is declared and paid by the 25th of the same month, moved to the next working day where needed, and is not shown as a separate date. ÖTV is not extended by the July financial holiday, and the President may shorten List I periods and deadlines.
Source
Özel Tüketim Vergisi Kanunu No. 4760, Madde 14 — Verginin beyanı, tarhı ve ödenmesi Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı)
See the source text
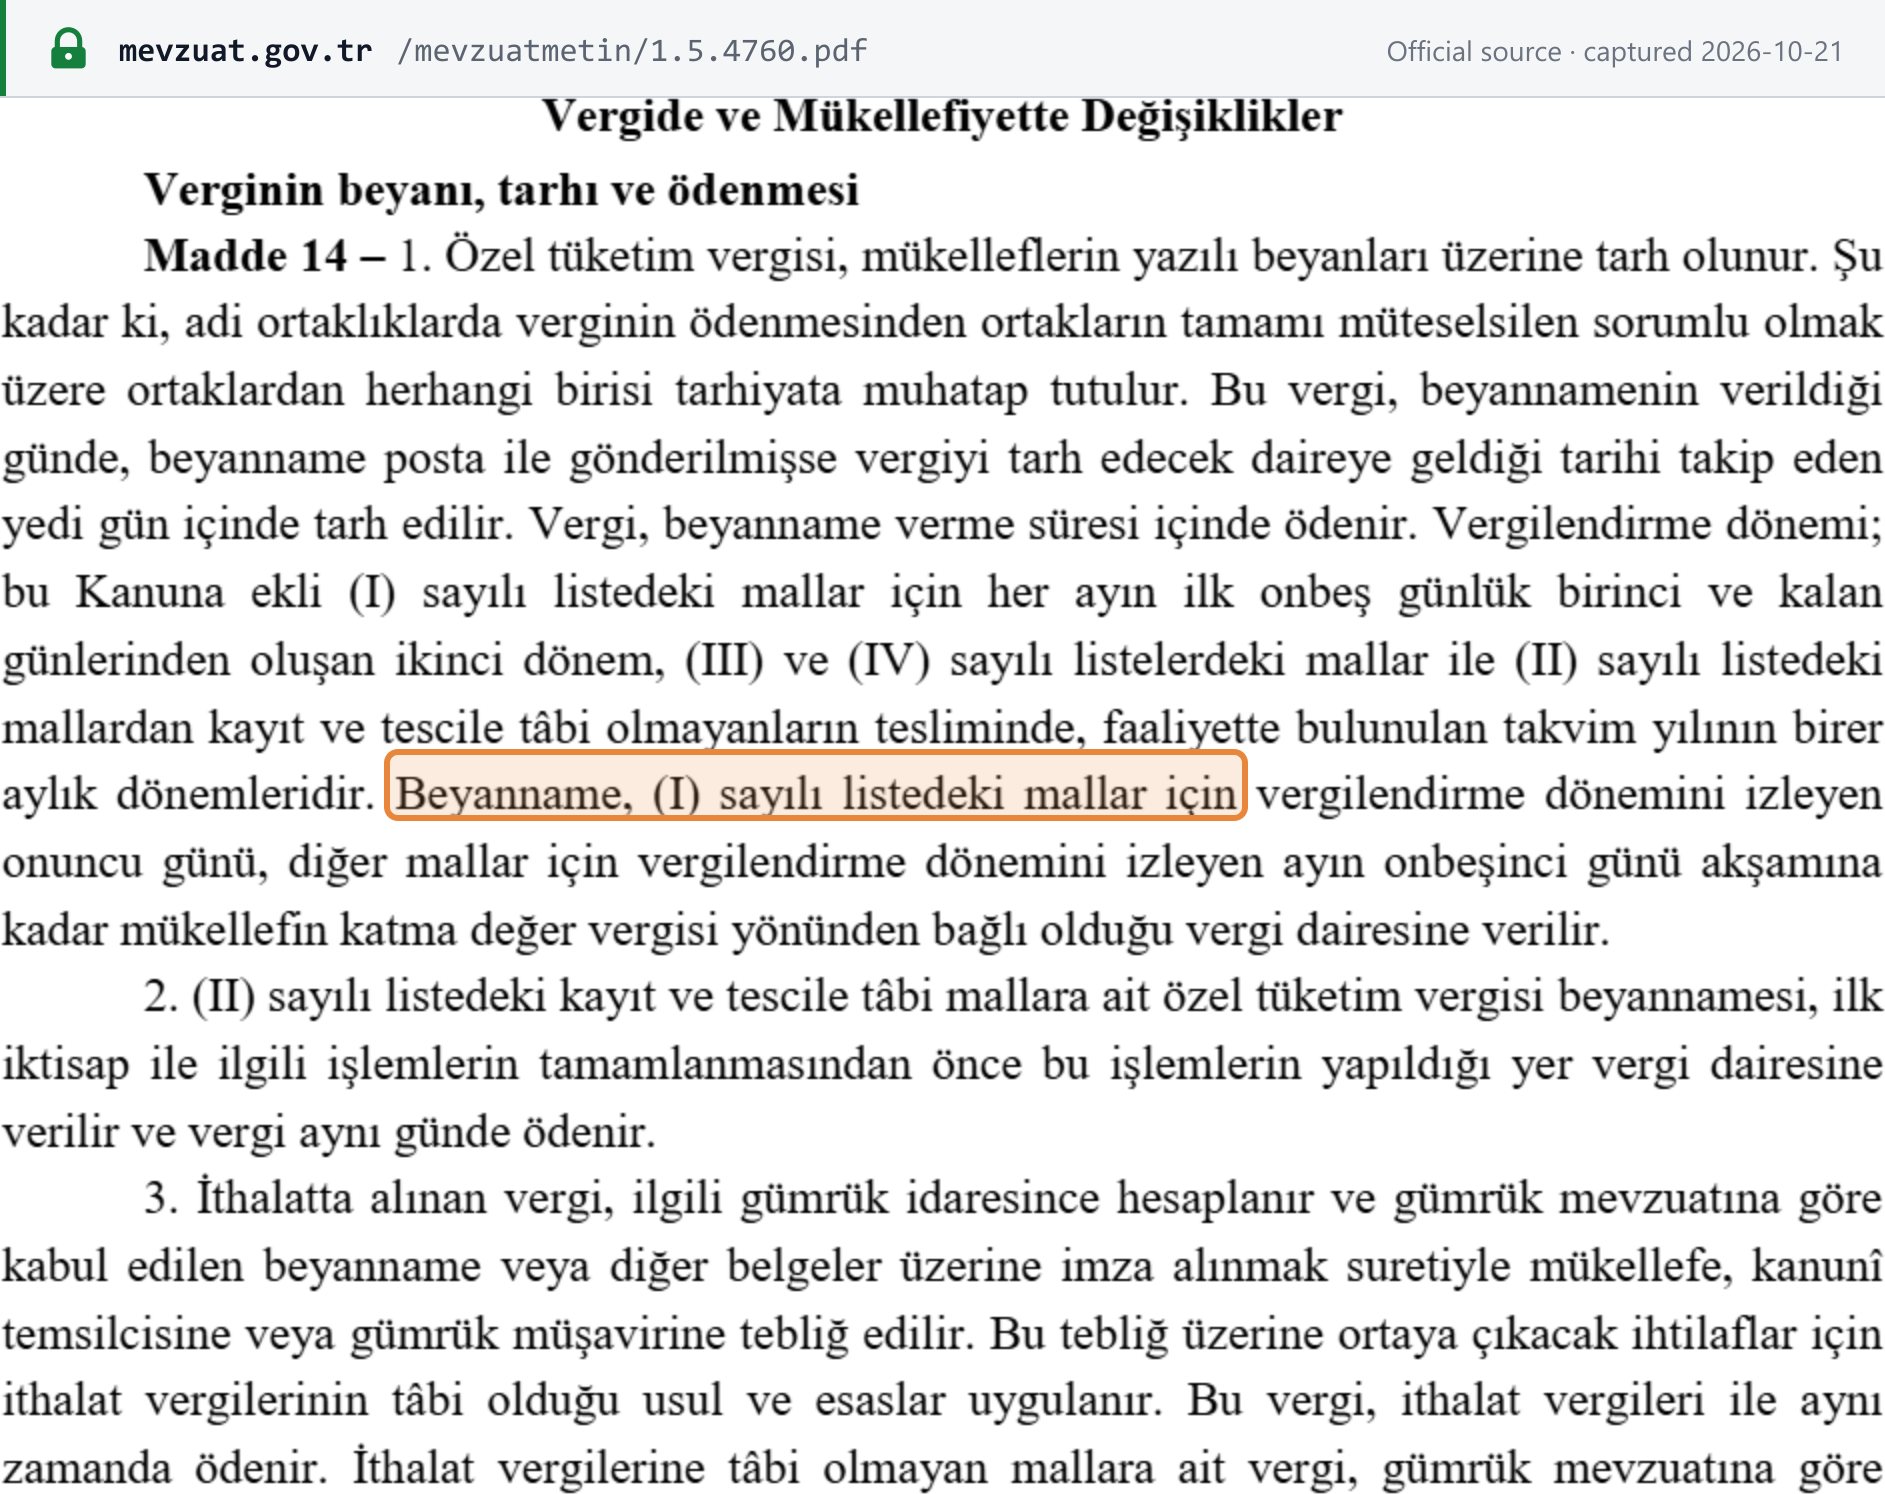
“Vergilendirme dönemi; bu Kanuna ekli (I) sayılı listedeki mallar için her ayın ilk onbeş günlük birinci ve kalan günlerinden oluşan ikinci dönem, (III) ve (IV) sayılı listelerdeki mallar ile (II) sayılı listedeki mallardan kayıt ve tescile tâbi olmayanların tesliminde, faaliyette bulunulan takvim yılının birer aylık dönemleridir. Beyanname, (I) sayılı listedeki mallar için vergilendirme dönemini izleyen onuncu günü, diğer mallar için vergilendirme dönemini izleyen ayın onbeşinci günü akşamına kadar mükellefin katma değer vergisi yönünden bağlı olduğu vergi dairesine verilir.”
Screenshot of Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) showing the ÖTV Beyannamesi, List (I) fuel products — second half-month (16th to month end) deadline Open full size Captured from Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) on 2026-10-21

ÖTV Beyannamesi, Lists (II) unregistered vehicles, (III) and (IV) — monthly return and payment

ÖTV (Özel Tüketim Vergisi — special consumption tax) · Monthly · return filing

15th of the month after the month ends Verified 2026-10-21
Who files
Manufacturers and importers of List (III) drinks and tobacco products, List (IV) durable consumer and other goods, and List (II) vehicles that are not subject to registration
Notes
One monthly date covers three lists: alcoholic and soft drinks and tobacco products (List III), durable consumer and other goods (List IV), and List II vehicles that are not subject to registration. File and pay by the 15th of the following month. In May 2027 the 15th is a Saturday followed by the Kurban Bayramı holiday and 19 May, so the deadline is Thursday 20 May 2027. Registered vehicles work differently: their ÖTV return goes to the tax office before the first-acquisition registration is completed, and the tax is paid that same day.
Source
Özel Tüketim Vergisi Kanunu No. 4760, Madde 14 — Verginin beyanı, tarhı ve ödenmesi Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı)
See the source text
“Beyanname, (I) sayılı listedeki mallar için vergilendirme dönemini izleyen onuncu günü, diğer mallar için vergilendirme dönemini izleyen ayın onbeşinci günü akşamına kadar mükellefin katma değer vergisi yönünden bağlı olduğu vergi dairesine verilir.”
Screenshot of Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) showing the ÖTV Beyannamesi, Lists (II) unregistered vehicles, (III) and (IV) — monthly return and payment deadline Open full size Captured from Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) on 2026-10-21

İşe başlama bildirimi — notification of starting business

KDV and all taxes administered under the Tax Procedure Law (VUK) · One-off · registration

within 10 days of starting business (işe başlama) Verified 2026-10-21
Who files
Every person starting a business; for companies the trade registry makes the notification at incorporation
Notes
An individual must notify the tax office within ten days of starting business, either personally or through a lawyer or licensed accountant. For a company, the trade registry sends the notification within ten days of incorporation, which discharges the company's own duty. There is no turnover threshold for KDV, so the clock starts when trading starts rather than when sales reach a set figure. Non-resident electronic-service suppliers register through a separate online form instead.
Source
Vergi Usul Kanunu No. 213, Madde 168 — Süre (bildirmeler) Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı)
See the source text
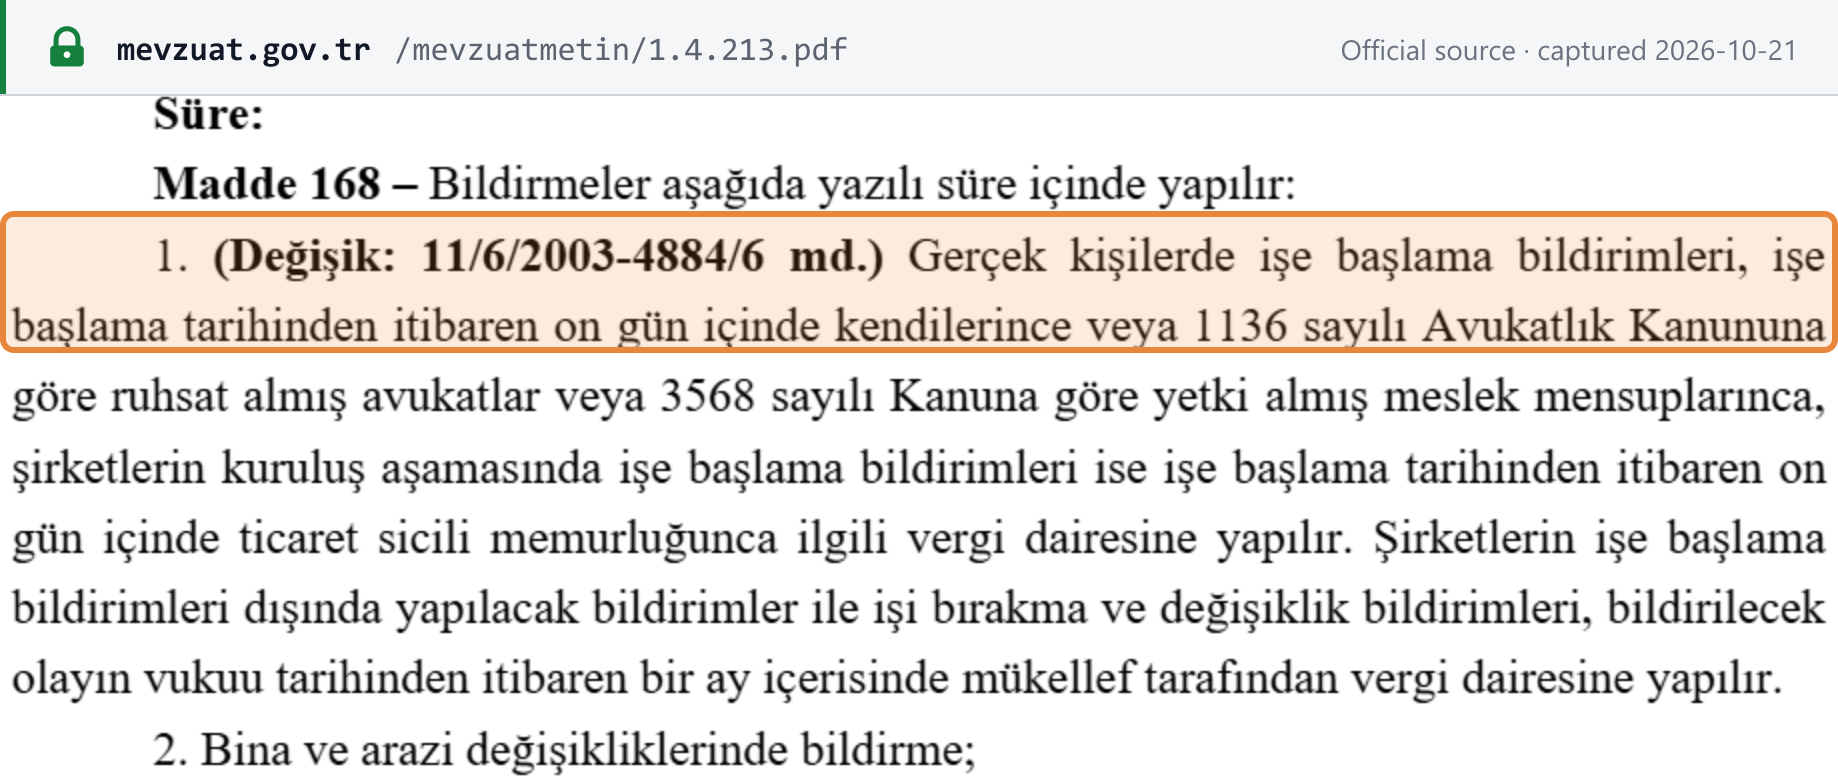
“Gerçek kişilerde işe başlama bildirimleri, işe başlama tarihinden itibaren on gün içinde kendilerince veya 1136 sayılı Avukatlık Kanununa göre ruhsat almış avukatlar veya 3568 sayılı Kanuna göre yetki almış meslek mensuplarınca, şirketlerin kuruluş aşamasında işe başlama bildirimleri ise işe başlama tarihinden itibaren on gün içinde ticaret sicili memurluğunca ilgili vergi dairesine yapılır.”
Screenshot of Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) showing the İşe başlama bildirimi — notification of starting business deadline Open full size Captured from Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) on 2026-10-21

İşi bırakma ve değişiklik bildirimi — notification of ceasing business or of changes

KDV and all taxes administered under the Tax Procedure Law (VUK) · One-off · registration

within 1 month of ceasing business or a change in registered particulars Verified 2026-10-21
Who files
Every registered taxpayer that ceases business or changes its registered particulars
Notes
Stopping business, and any change to the particulars the tax office holds, must be notified within one month of the event. Ceasing business also triggers a final KDV return covering the period up to the day trading stopped. The KDV Law sets the 24th of the following month; the general extension to the 28th is likely to apply, but filing by the 24th is the safe choice.
Source
Vergi Usul Kanunu No. 213, Madde 168 — Süre (bildirmeler) Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı)
See the source text
“Şirketlerin işe başlama bildirimleri dışında yapılacak bildirimler ile işi bırakma ve değişiklik bildirimleri, bildirilecek olayın vukuu tarihinden itibaren bir ay içerisinde mükellef tarafından vergi dairesine yapılır.”
Screenshot of Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) showing the İşi bırakma ve değişiklik bildirimi — notification of ceasing business or of changes deadline Open full size Captured from Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı) on 2026-10-21

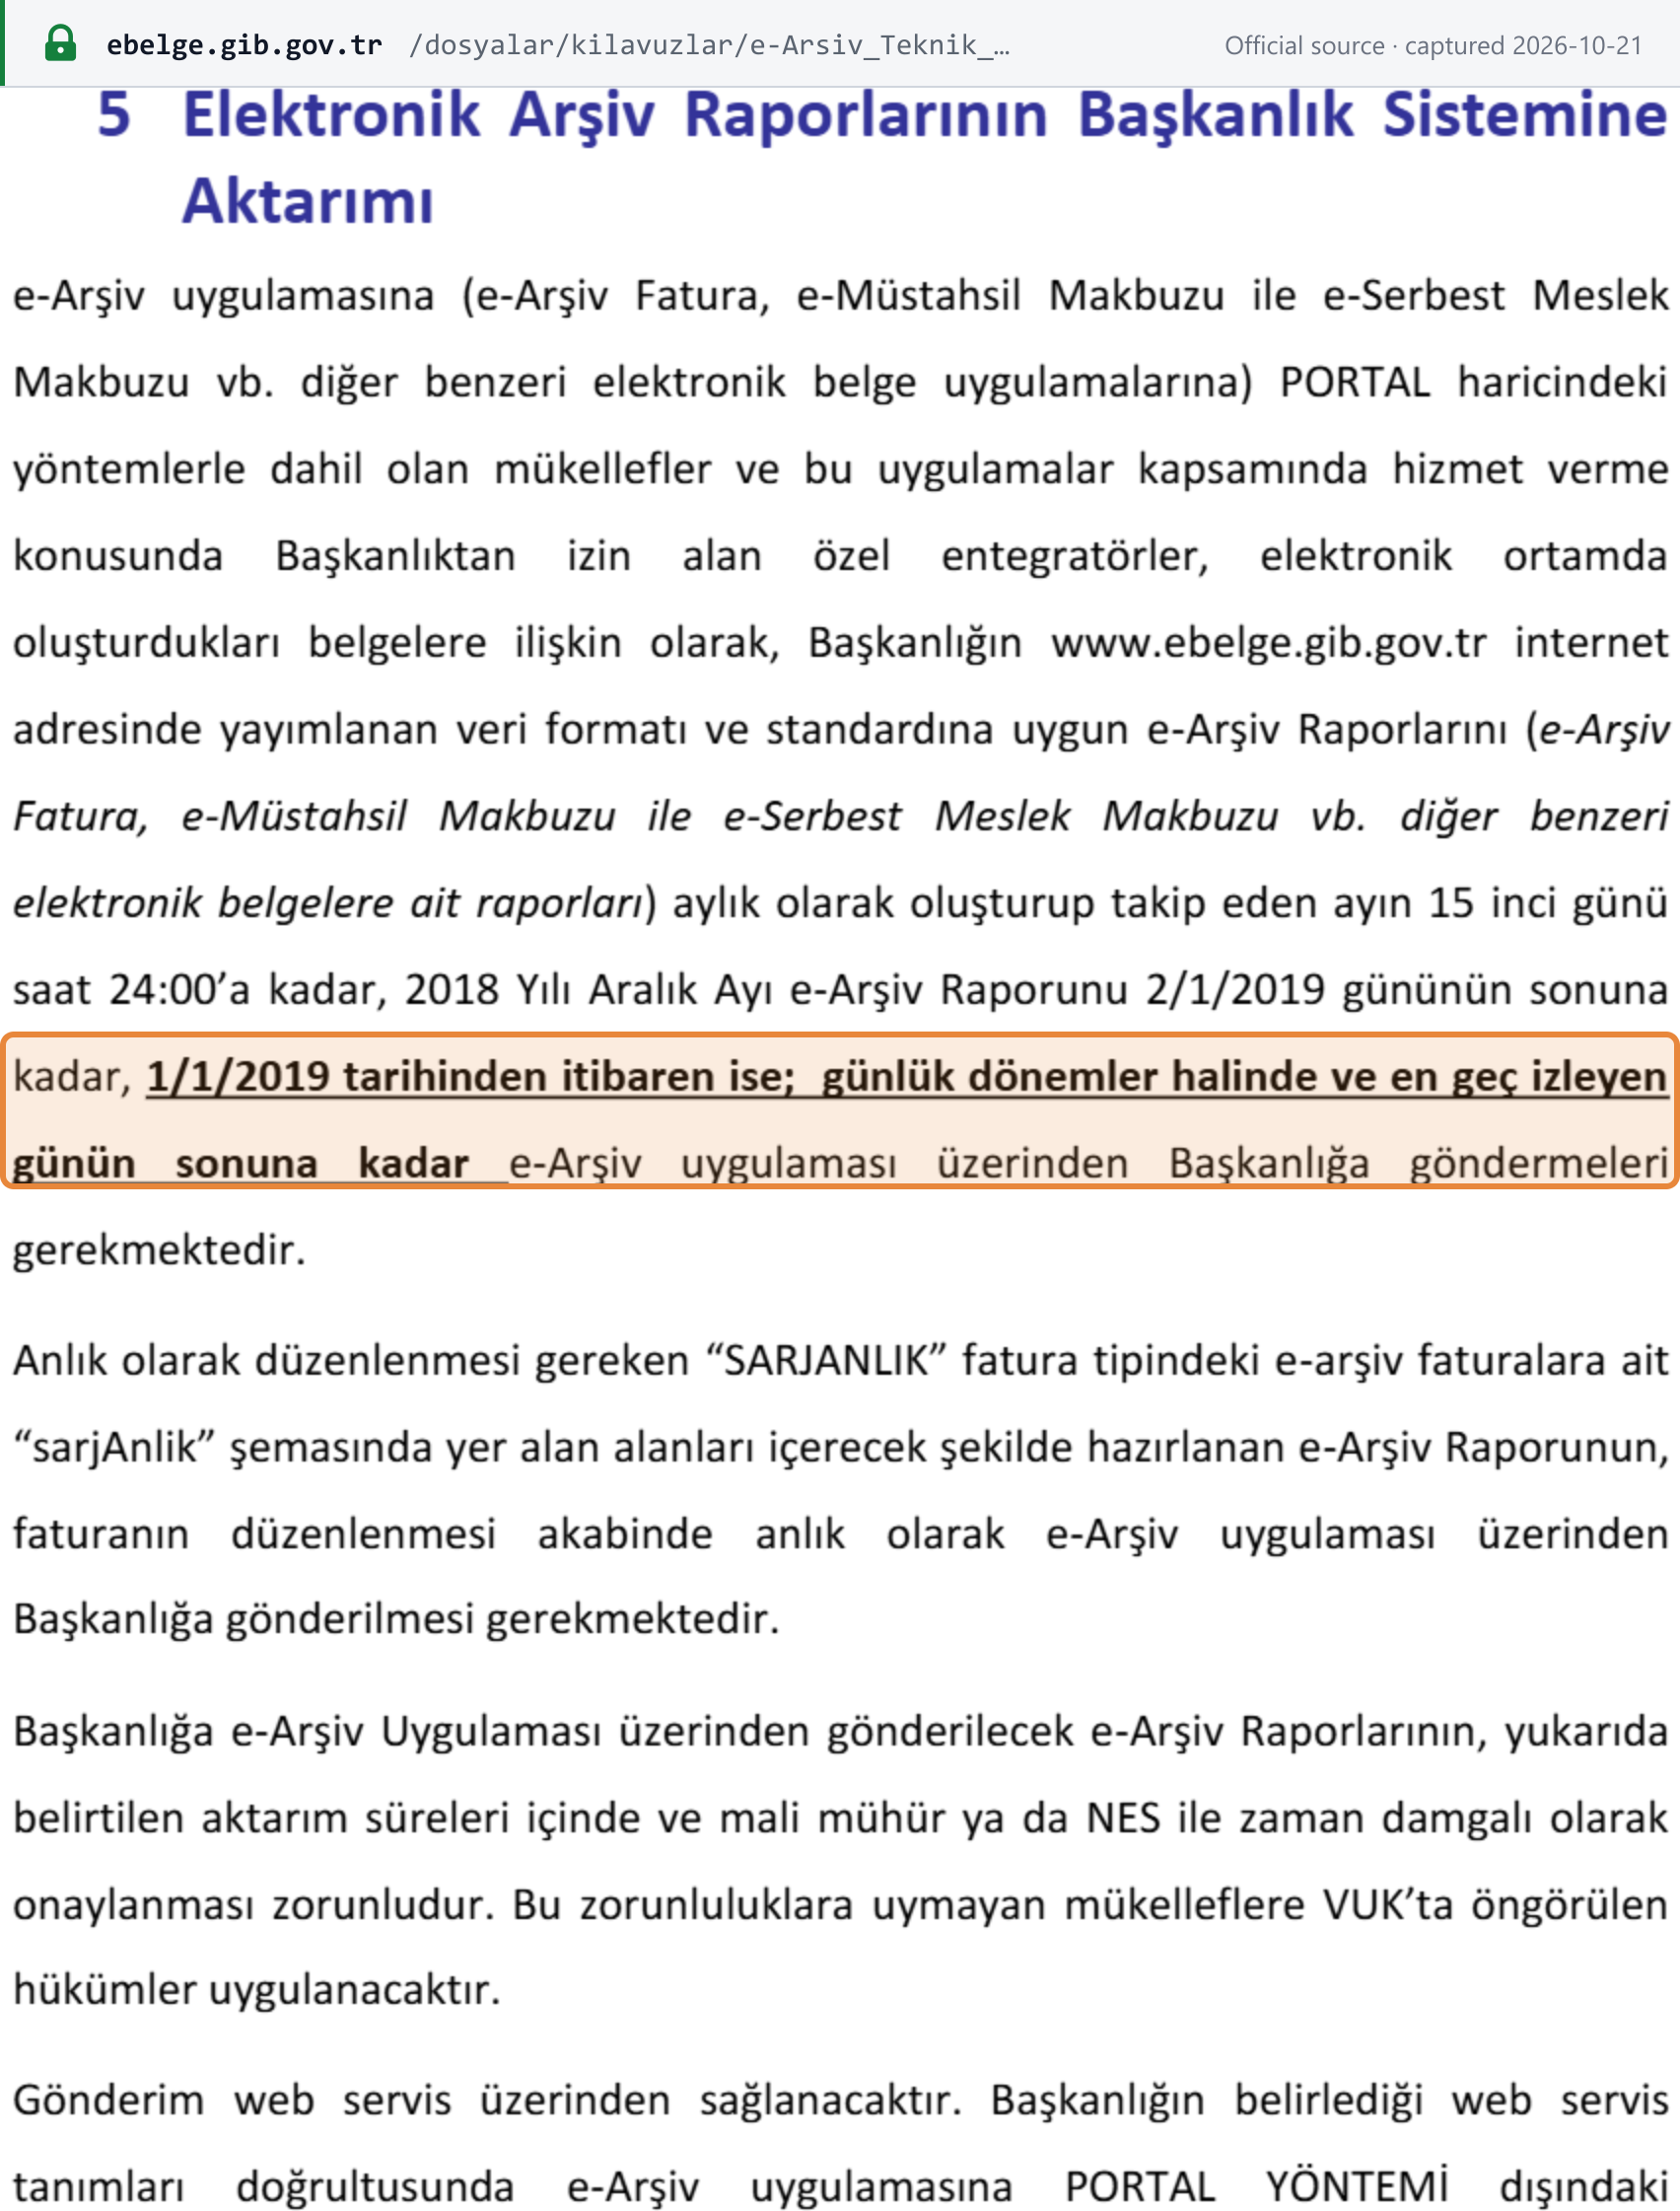
e-Arşiv Raporu — daily e-Arşiv report to GİB

e-Arşiv (electronic archive invoices) · One-off · other

within 1 days of the day the e-Arşiv documents were issued Verified 2026-10-21
Who files
Businesses on e-Arşiv through a private integrator (özel entegratör) or direct integration; GİB portal users are exempt
Notes
Businesses issuing e-Arşiv invoices through a private integrator or their own integration must send GİB a signed e-Arşiv report covering each day's documents by the end of the following day. Businesses using GİB's free portal have no reporting duty. e-Fatura invoices pass through GİB as they are issued, so they carry no separate reporting deadline.
Source
e-Arşiv Kılavuzu v1.19 (Ekim 2026), §5 — Elektronik Arşiv Raporlarının Başkanlık Sistemine Aktarımı Gelir İdaresi Başkanlığı (GİB)
See the source text
“1/1/2019 tarihinden itibaren ise; günlük dönemler halinde ve en geç izleyen günün sonuna kadar e-Arşiv uygulaması üzerinden Başkanlığa göndermeleri gerekmektedir.”
Screenshot of Gelir İdaresi Başkanlığı (GİB) showing the e-Arşiv Raporu — daily e-Arşiv report to GİB deadline Open full size Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21

Half-yearly confirmation of non-deductible import KDV (Presidential Decision 7846) — notification or special-purpose sworn-accountant report

KDV (Katma Değer Vergisi — VAT) · Bi-annually · report / listing

last day of the month after the half-year ends Verified 2026-10-21
Who files
Importers that paid import KDV on surveillance-price uplifts or on anti-dumping, countervailing or safeguard duties; a notification at or below the sworn-accountant certification threshold by import value, a special-purpose sworn-accountant report above it
Notes
Importers whose import KDV includes amounts that Presidential Decision 7846 makes non-deductible (on surveillance-price uplifts and on anti-dumping, countervailing and safeguard duties) must confirm for each calendar half-year that they did not deduct them. For imports whose value is at or below the sworn-accountant certification threshold a notification to the tax office is enough; for imports above it a special-purpose sworn-accountant report is needed, unless a full-certification (tam tasdik) report already covers them. Either is due by the end of the month after the half-year. The duty dates from KDV General Communiqué Serial 57 (31 January 2026); the first deadline was 31 July 2026.
Source
Katma Değer Vergisi Genel Uygulama Tebliği (GİB consolidated text, 2026), §III/C-2.6.2 — 7846 sayılı Cumhurbaşkanı Kararı Gelir İdaresi Başkanlığı (GİB)
See the source text
“işlemin yapıldığı döneme ait KDV beyannamesinde mezkur Karar kapsamında doğru bir şekilde indirim konusu yapılıp yapılmadığını altışar aylık dönemleri izleyen ayın sonuna kadar bağlı oldukları vergi dairesine bildirirler.”
Captured from Gelir İdaresi Başkanlığı (GİB) on 2026-10-21

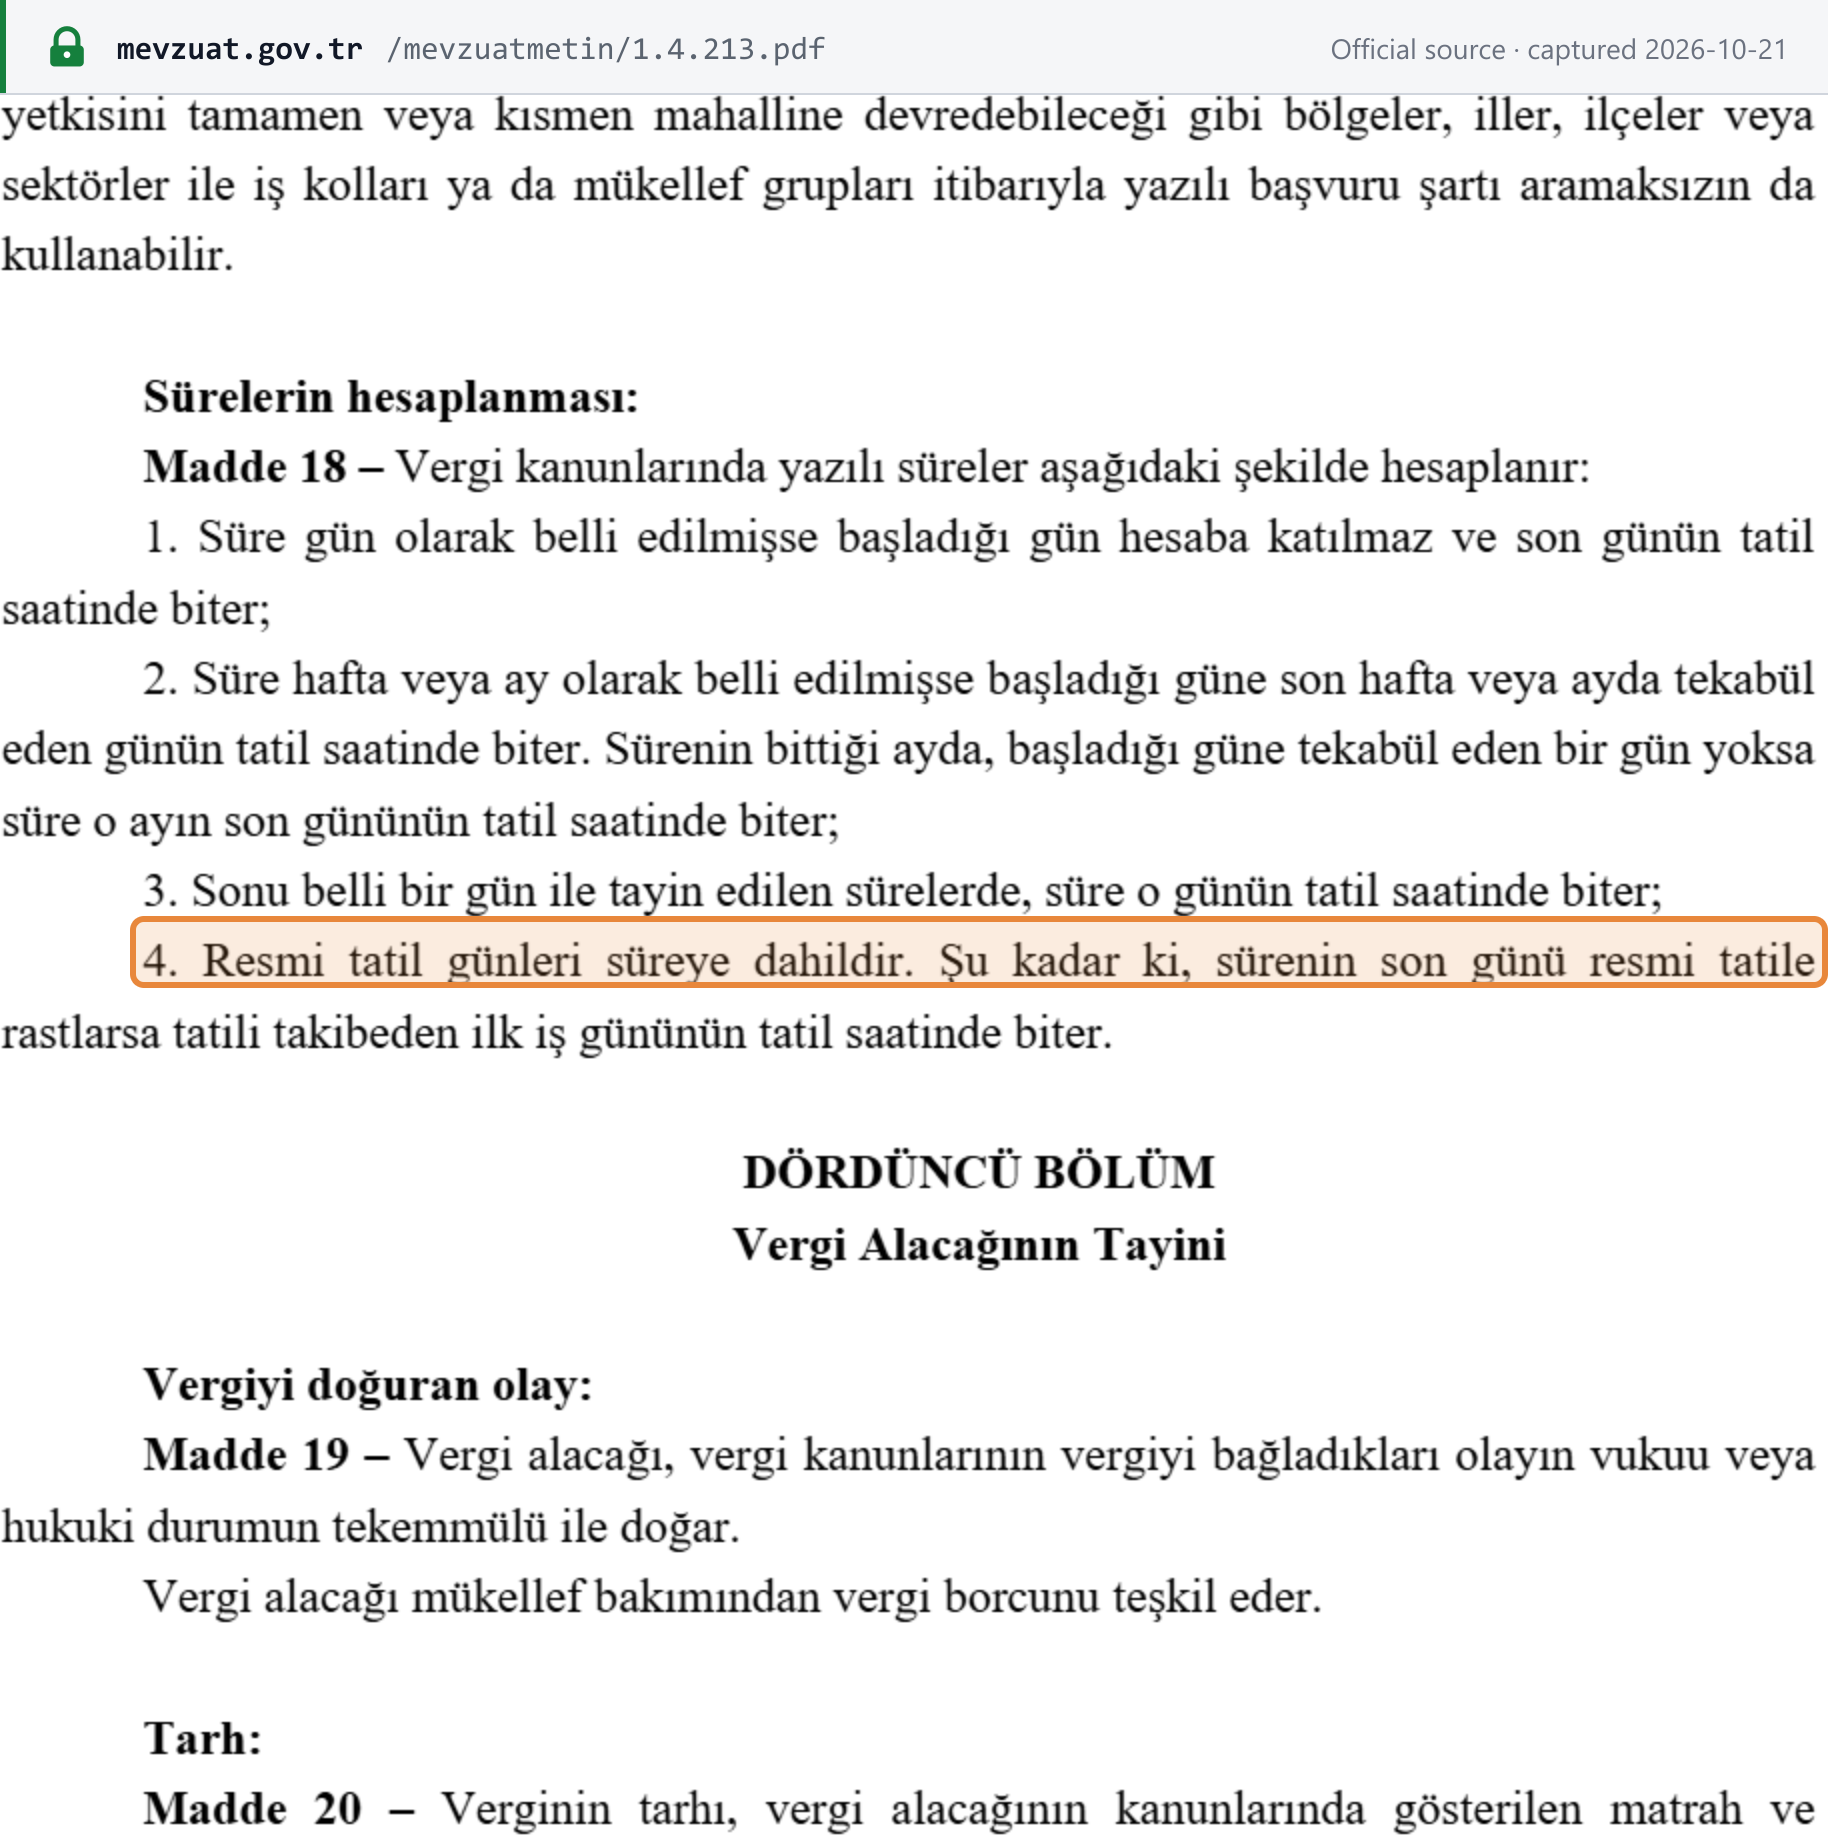
Turkish VAT (KDV) and special consumption tax (ÖTV) are filed and paid on the same day, so each date below is both the filing and the payment deadline. The days in force come from tax administration circulars that extended the statutory dates until further notice: the 28th for ordinary KDV returns and the 25th for withholding returns. A deadline that falls on a Saturday, a Sunday or a full-day public holiday moves to the next working day. The afternoon-only holidays, 28 October and the eves of the two religious festivals, do not move a deadline. The tax administration sometimes extends a single month by circular; those one-off extensions are not shown here. There is no annual KDV return, and the monthly Form Ba and Form Bs purchase and sales listings were abolished from the September 2024 period. ÖTV on imports is collected by customs with import duties. Accommodation tax, banking and insurance transactions tax, special communication tax, games of chance tax, digital service tax and e-ledger (e-Defter) uploads have their own deadlines and are not covered here.

“4. Resmi tatil günleri süreye dahildir. Şu kadar ki, sürenin son günü resmi tatile rastlarsa tatili takibeden ilk iş gününün tatil saatinde biter.”
Screenshot of the official source stating the rule that governs Türkiye's deadlines
Vergi Usul Kanunu No. 213, Madde 18 — Sürelerin hesaplanması — Mevzuat Bilgi Sistemi (T.C. Cumhurbaşkanlığı), captured 2026-10-21

What this calendar does not list

  • Not applicable Annual or reconciliation return — Türkiye has no annual KDV or ÖTV return. KDV Law 3065 arts. 39–41 provide only monthly or quarterly periods (a calendar-year period exists solely for lump-sum götürü-usul taxpayers, assessed through income tax) and returns at customs, and GİB's return-deadline table (Beyanname Verme ve Ödeme Süreleri) lists only periodic and event returns. Checked 21 October 2026.
  • Not applicable Recapitulative listing — The monthly Form Ba and Form Bs purchase and sales listings were abolished from the September 2024 period by VUK General Communiqué 565 (Resmî Gazete 25 September 2024, no. 32673): "Eylül 2024 dönemi ve bu dönemi izleyen dönemlere ilişkin olarak Form Ba ve Form Bs bildirimi verilmeyecektir." Türkiye has no EC Sales List or SAF-T listing; e-Defter is a bookkeeping duty and VUK 595 platform reporting is an intermediary information duty, not a KDV listing. Checked 21 October 2026.

About this calendar

Which Türkiye tax deadlines does this calendar cover?

11 recurring indirect-tax obligations — KDV (Katma Değer Vergisi, ÖTV (Özel Tüketim Vergisi, KDV and all taxes administered under the Tax Procedure Law (VUK) and e-Arşiv (electronic archive invoices) returns, payments and related filings — each with the due-date rule, who must file, and the official source that states the deadline. Direct-tax, payroll and company-registry deadlines are out of scope.

How current are these due dates?

Every obligation carries the date it was last verified against its official source (newest: 2026-10-21). Law-change dates come from the weekly Last Week in Taxes scan and link to their full change records.

Do the dates account for weekends and public holidays?

No — the calendar shows the statutory due date. Where the authority shifts deadlines falling on non-working days, the obligation notes say so. Confirm against the linked official source before relying on a date.

Validate tax IDs in 100+ countries

Put these rules into practice — verify VAT, GST, and EIN numbers in real time with the Lookuptax API.