Isle of Man VAT guidelines
| FACTSHEET | |
|---|---|
| Country code | IM |
| Tax name | Value Added Tax (VAT) |
| Tax Authority | Customs and Excise Division of the Treasury |
Overview
The Isle of Man levies Value Added Tax (VAT) under its own law, the Value Added Tax Act 1996 (an Act of Tynwald), with Orders and Regulations made under it. In the Customs and Excise Division's words, VAT "is a consumption tax charged on goods and services", and VAT-registered businesses "collect and account for the tax and pass the tax collected to the Customs and Excise Division of the Treasury." [1]
One VAT area with the UK. The Isle of Man is not part of the UK, but for VAT it is treated as if it were. HMRC VAT Notice 700 §4.7.1: "For VAT purposes the Isle of Man is treated as part of the UK. If you have customers or suppliers in the Isle of Man, the VAT rules are the same as if they were in the UK. Goods sent from Great Britain to the Isle of Man or vice versa do not count as imports or exports for VAT purposes." §4.7.2 adds that VAT "is chargeable in the Isle of Man under Manx law which generally matches UK legislation", and that references in the notice to the UK also apply to the Isle of Man, except for two Isle of Man-only 5% rates (see Rates). [2] The Treasury applies changes "in alignment with the Customs and Excise Agreement 1979" with the UK. [3]
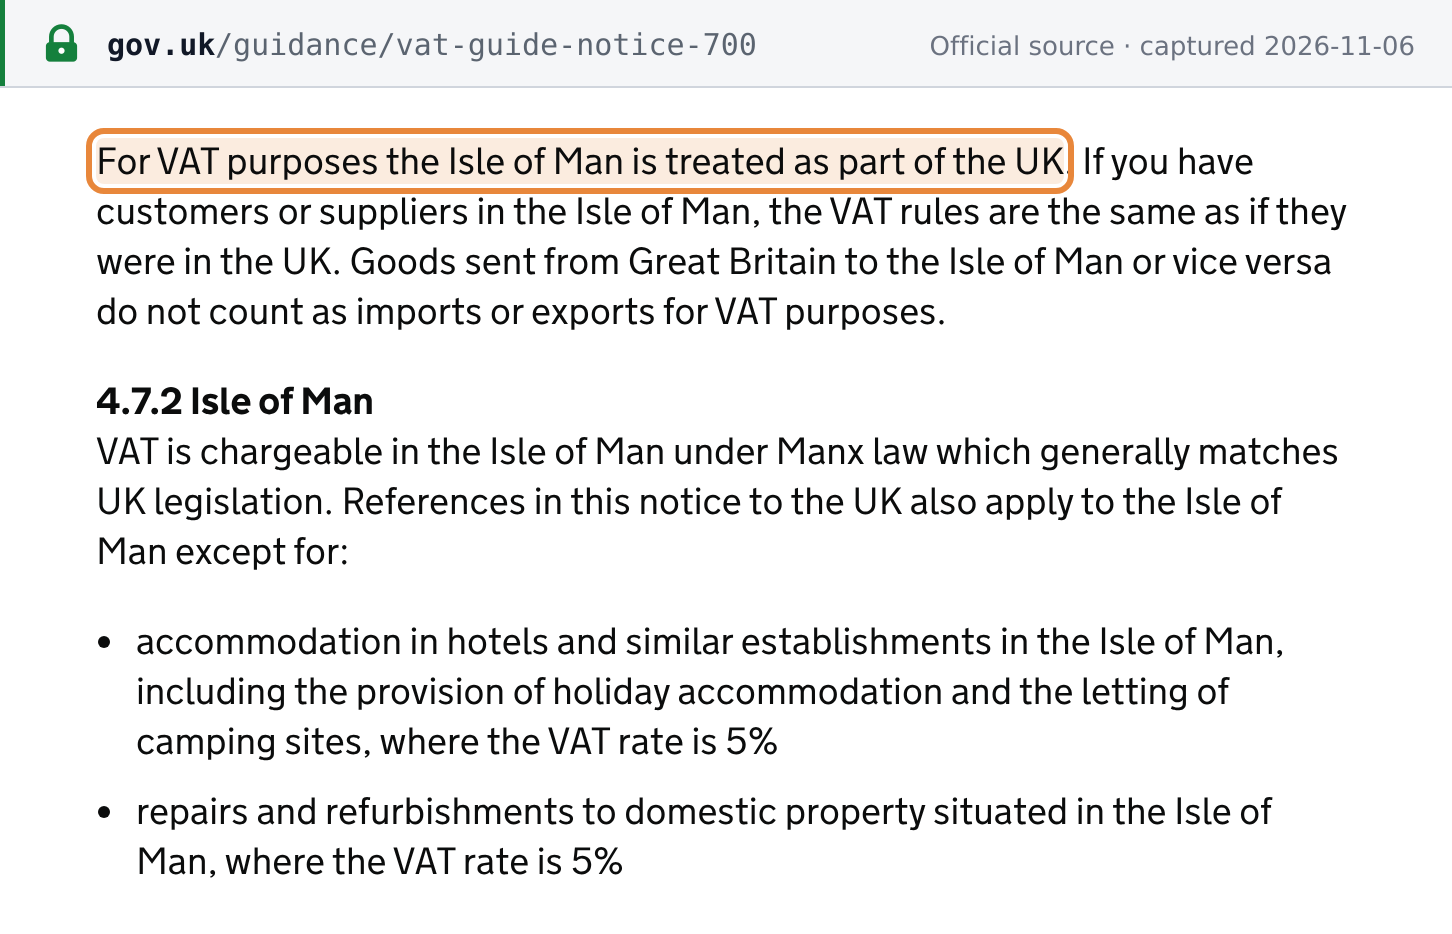 Source snapshot captured 2026-11-06 — original
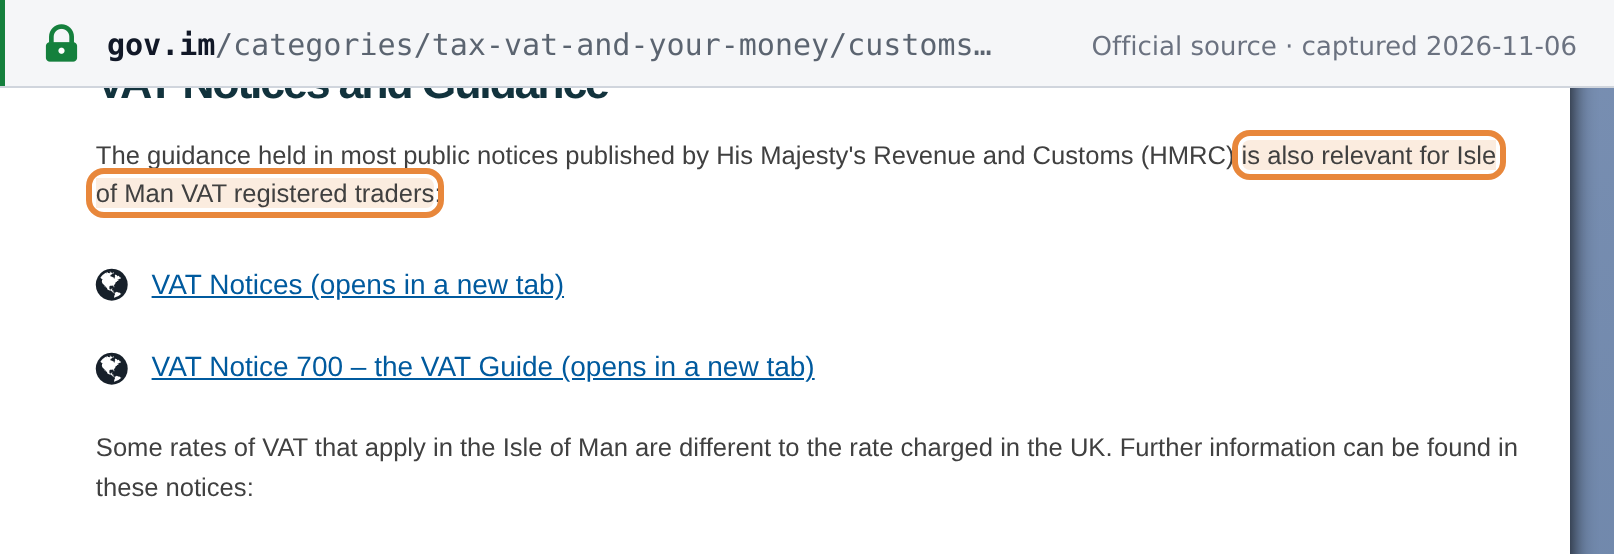
Where HMRC guidance applies. The Customs and Excise VAT page tells Manx traders that "The guidance held in most public notices published by His Majesty's Revenue and Customs (HMRC) is also relevant for Isle of Man VAT registered traders", and links VAT Notice 700. It then lists the Isle of Man notices that apply instead where "Some rates of VAT that apply in the Isle of Man are different to the rate charged in the UK": the Domestic Reverse Charge notice, the reduced-rate notices for construction services and for hotel accommodation, and the Isle of Man Tour Operators' Margin Scheme. [1] This page follows that split: HMRC notices for the general rules (invoices, records, place of supply), Isle of Man notices wherever Customs has published its own.
Authority. VAT is administered by the Customs and Excise Division of the Treasury in Douglas, not by HMRC. Older notices and forms still use the division's earlier name, "Customs and Immigration".
Currency. Pound sterling (GBP, "£"). The VAT total on an invoice must be expressed in sterling (Notice 700 §16.3.1; see Invoice requirements).
Tax period. VAT is accounted for by return period (quarterly, monthly or annual; see Filing and payment). There is no separate VAT year.
Layering. None. VAT is a single Island-wide tax; there is no sub-national VAT or sales tax.
For the UK rules the Isle of Man mirrors, see the United Kingdom VAT guide. For a Crown Dependency with no VAT at all, compare Guernsey.
Registration
Who should register
Customs' Registering for VAT page sets out the liability rule: "You are required to register for VAT if: At the end of any month the total value of your taxable supplies you have made in the preceding 12 months, on a rolling 12-month basis, exceeds £90,000 or At any time you expect that the value of your taxable supplies in the next 30 days period alone will be more than £90,000". Other triggers on the same page are a change in the legal status of a VAT-registered business, taking over a VAT-registered business as a going concern, and a new lease that continues a VAT-registered tenant's trade. [4]
"Taxable supplies" are supplies at the standard, reduced or zero rate. A business that makes only exempt supplies cannot register. [1]
Registration threshold
£90,000 of taxable supplies, measured at each month end over the preceding 12 months on a rolling basis, or expected in the next 30 days alone (as at 2026-11-06). [4] It is the same figure as the UK threshold.
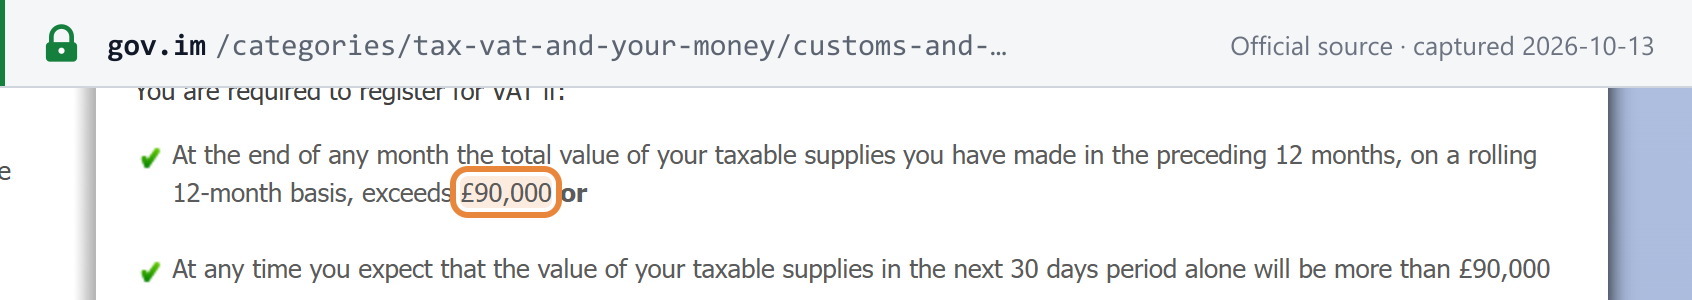 Source snapshot captured 2026-10-13 — original
See also VAT registration thresholds worldwide.
UK or Isle of Man — never both
Because the two form one VAT area, a business registers in one of them only. HMRC's VAT Registration Manual: "Persons may only be registered in either the UK or the IoM at any one time". A person with an establishment only in the UK registers in the UK; one with an establishment only in the Isle of Man registers in the Isle of Man; one with establishments in both, or in neither, is registered in the country "decided by the Commissioners in consultation with the IoM service." [5]
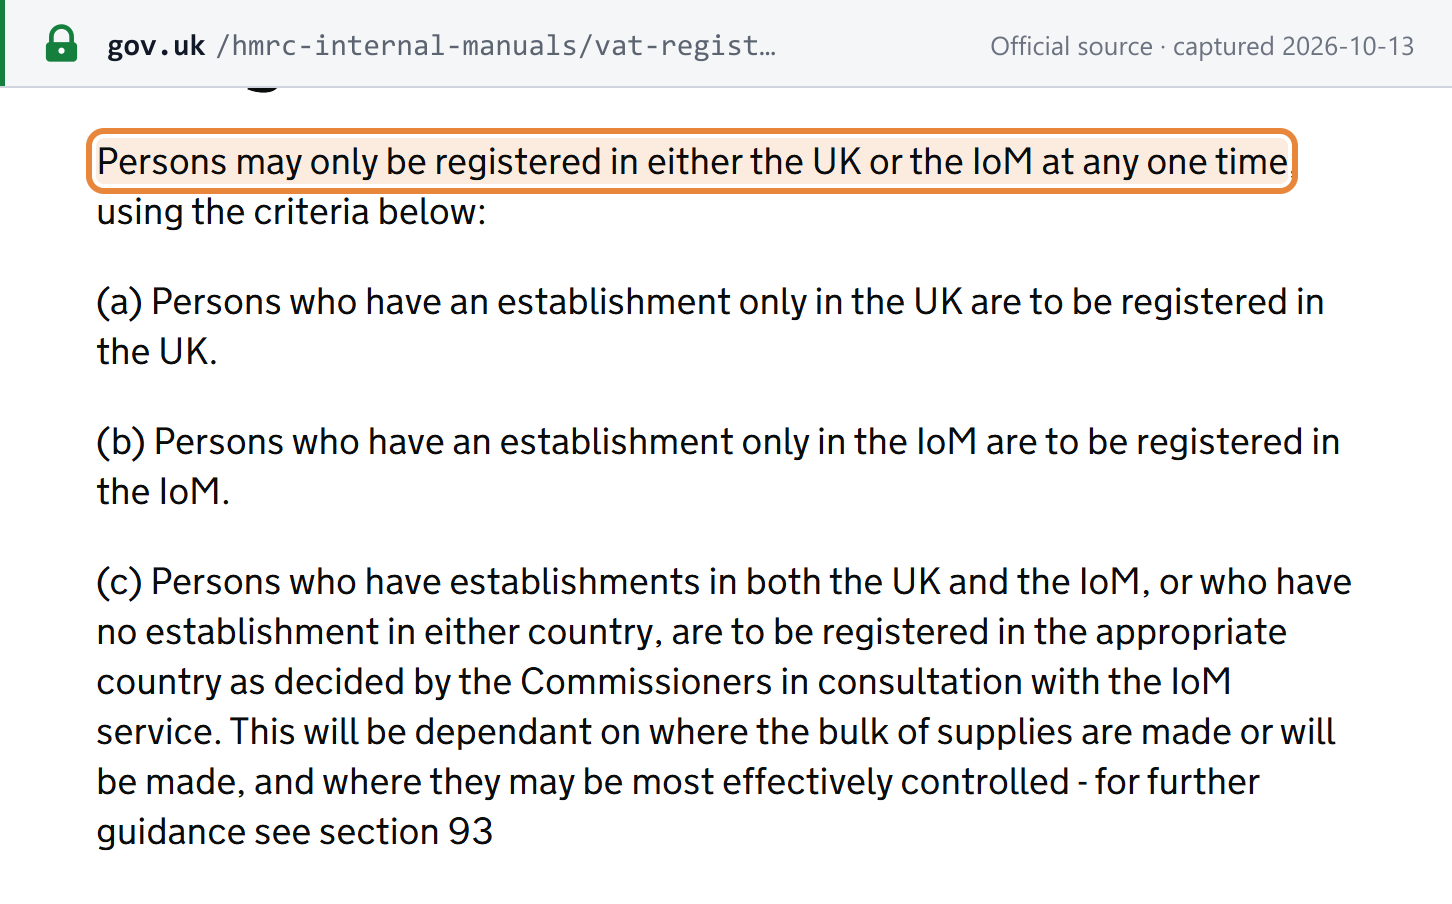 Source snapshot captured 2026-10-13 — original
Non-resident registration
There is no threshold for a business established outside both the UK and the Isle of Man. GOV.UK: "You must also register (regardless of taxable turnover) if all of the following are true:" you're based outside the UK; your business is based outside the UK; and you "supply any goods or services to the UK (or expect to in the next 30 days)". [6] Customs adds: "In most cases businesses who belong outside the Isle of Man ['IOM'] and UK, who are required to VAT register in the IOM/UK should contact HMRC's non-established taxable persons unit." Where Isle of Man registration is more appropriate, the business may have to appoint a tax representative (form VAT 1 TRMAN), and "both parties are jointly and severally liable for any debts incurred in respect of the VAT registration." [4]
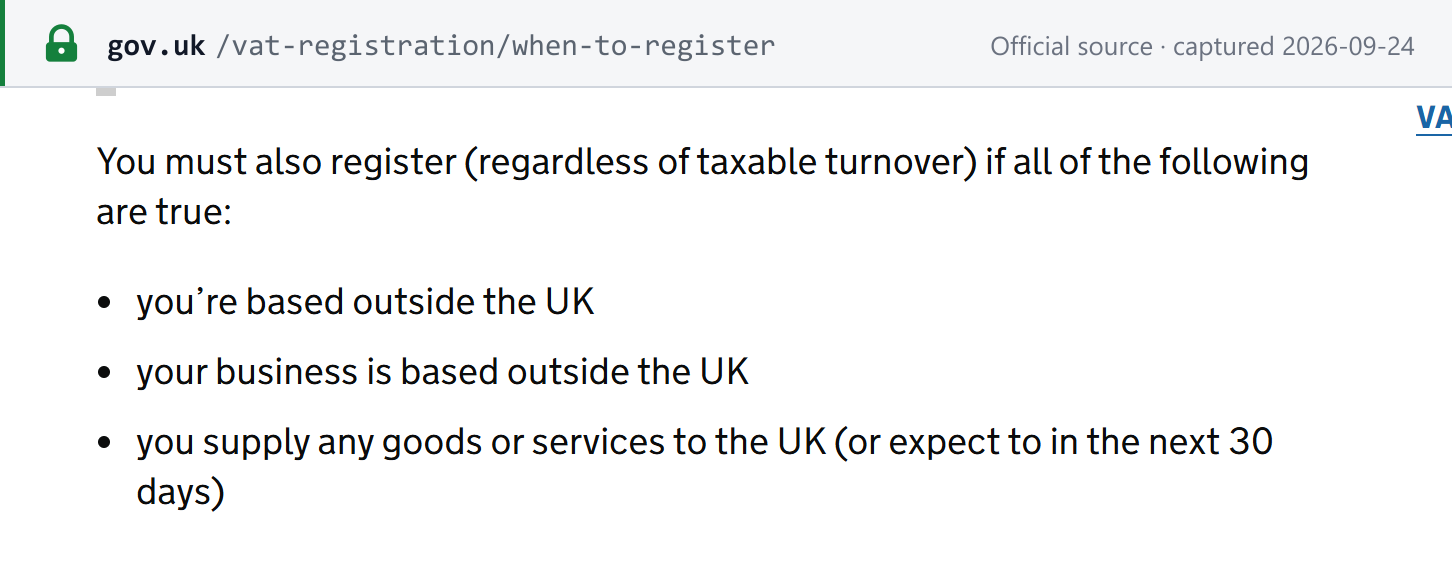 Source snapshot captured 2026-09-24 — original
Tax identification number
Isle of Man VAT numbers are UK-format numbers with the GB prefix and nine digits. HMRC: "Numbers on the Isle of Man register are in the same nine-digit series as UK registration numbers, but are identified by the first two digits being '00'." [7] The format is therefore GB 00X XXXX XX. They are checked with HMRC's Check a UK VAT number service, which gov.im links; VIES does not cover them. On registration Customs issues a VAT registration certificate and a Tax Identification Number (TIN). [4]
For the check-digit method, the Tax Reference Number and company numbers, see the Isle of Man tax ID guide. For how the HMRC checker works, see how to verify a UK VAT number.
How to register
"You can register for VAT: Online, using gov.im online services or By completing the registration form (VAT 1 MAN) and sending to the VAT registration team" (registration.customs@gov.im). VAT groups and partnerships use the form. Supporting forms include the REG 5 MAN turnover sheet and, for digital-service and intellectual-property businesses, the REG 9 MAN questionnaire (October 2026). Customs aims "to process applications within 10 working days." [4]
Until the number arrives: "You cannot include VAT on your invoices until you get your VAT number, but you can increase your prices to account for the VAT you will need to pay". [4]
Voluntary registration
Available. A business "making taxable supplies below the VAT threshold" may register voluntarily, using the same route. [4] Registration lets a business recover input tax; a business making only exempt supplies cannot register.
Deregistration
- Compulsory. When taxable supplies stop or the business is sold, "you must inform Customs and Immigration within 30 days that your circumstances have changed and that your registration should be cancelled".
- Voluntary. When "your taxable turnover in the next 12 months will not exceed £88,000".
- Final return. "You must submit your final return within one month of the cancellation date, unless you are on the Cash Accounting Scheme." Form VAT 7 MAN. [8]
Group registration
Available. "VAT grouping is a facilitation measure by which 2 or more eligible persons can be treated as a single taxable person for VAT purposes. Eligible persons are corporate bodies, individuals and partnerships, provided that certain conditions are met." [4] See VAT grouping explained.
Rates
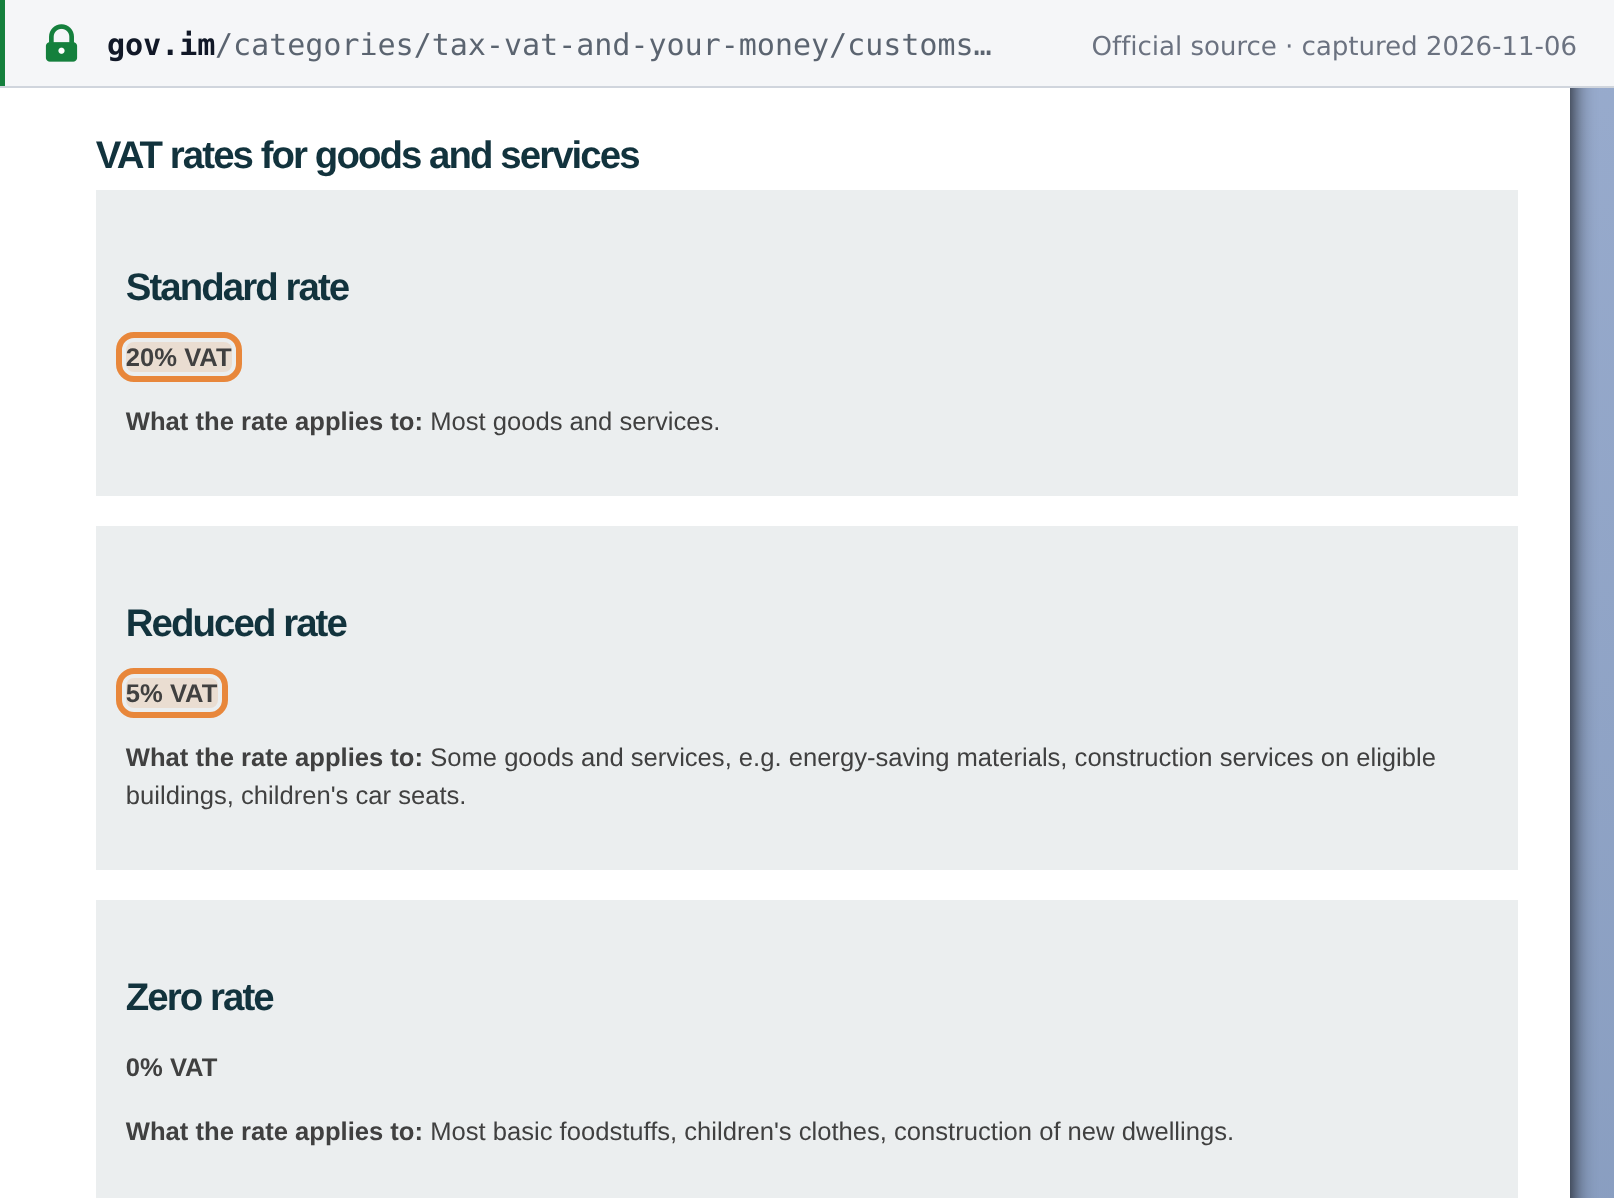
The Customs and Excise VAT page lists three rates (as at 2026-11-06): [1]
| Rate | Applies to (gov.im wording) |
|---|---|
| 20% standard | "Most goods and services." |
| 5% reduced | "Some goods and services, e.g. energy-saving materials, construction services on eligible buildings, children's car seats." |
| 0% zero | "Most basic foodstuffs, children's clothes, construction of new dwellings." |
 Source snapshot captured 2026-11-06 — original
Customs points to HMRC's VAT rates on different goods and services for the detailed rate of each item, except where an Isle of Man notice sets a different rate.
Isle of Man-only 5% rates
Two reduced rates apply in the Isle of Man but not in the UK. Both appear in HMRC Notice 700 §4.7.2 (see the snapshot in Overview).
- Hotel and holiday accommodation. VAT Notice 709/3A MAN (July 2024): "If you provide a person with accommodation in a hotel or similar establishment, your supply is liable to a reduced rate of VAT. This also includes the provision of holiday accommodation and the letting of camping sites and caravan parks (including the pitch rental). It does not however include the provision of timeshare accommodation." The legal basis is section 2(4) of, and Schedule 1 to, the Value Added Tax Act 1996. [9] The 5% covers the accommodation element: under the notice, catering in a half- or full-board tariff is standard-rated. Tour operators bring reduced-rate Isle of Man accommodation into the margin scheme under VAT Notice 709/5 MAN. [10]
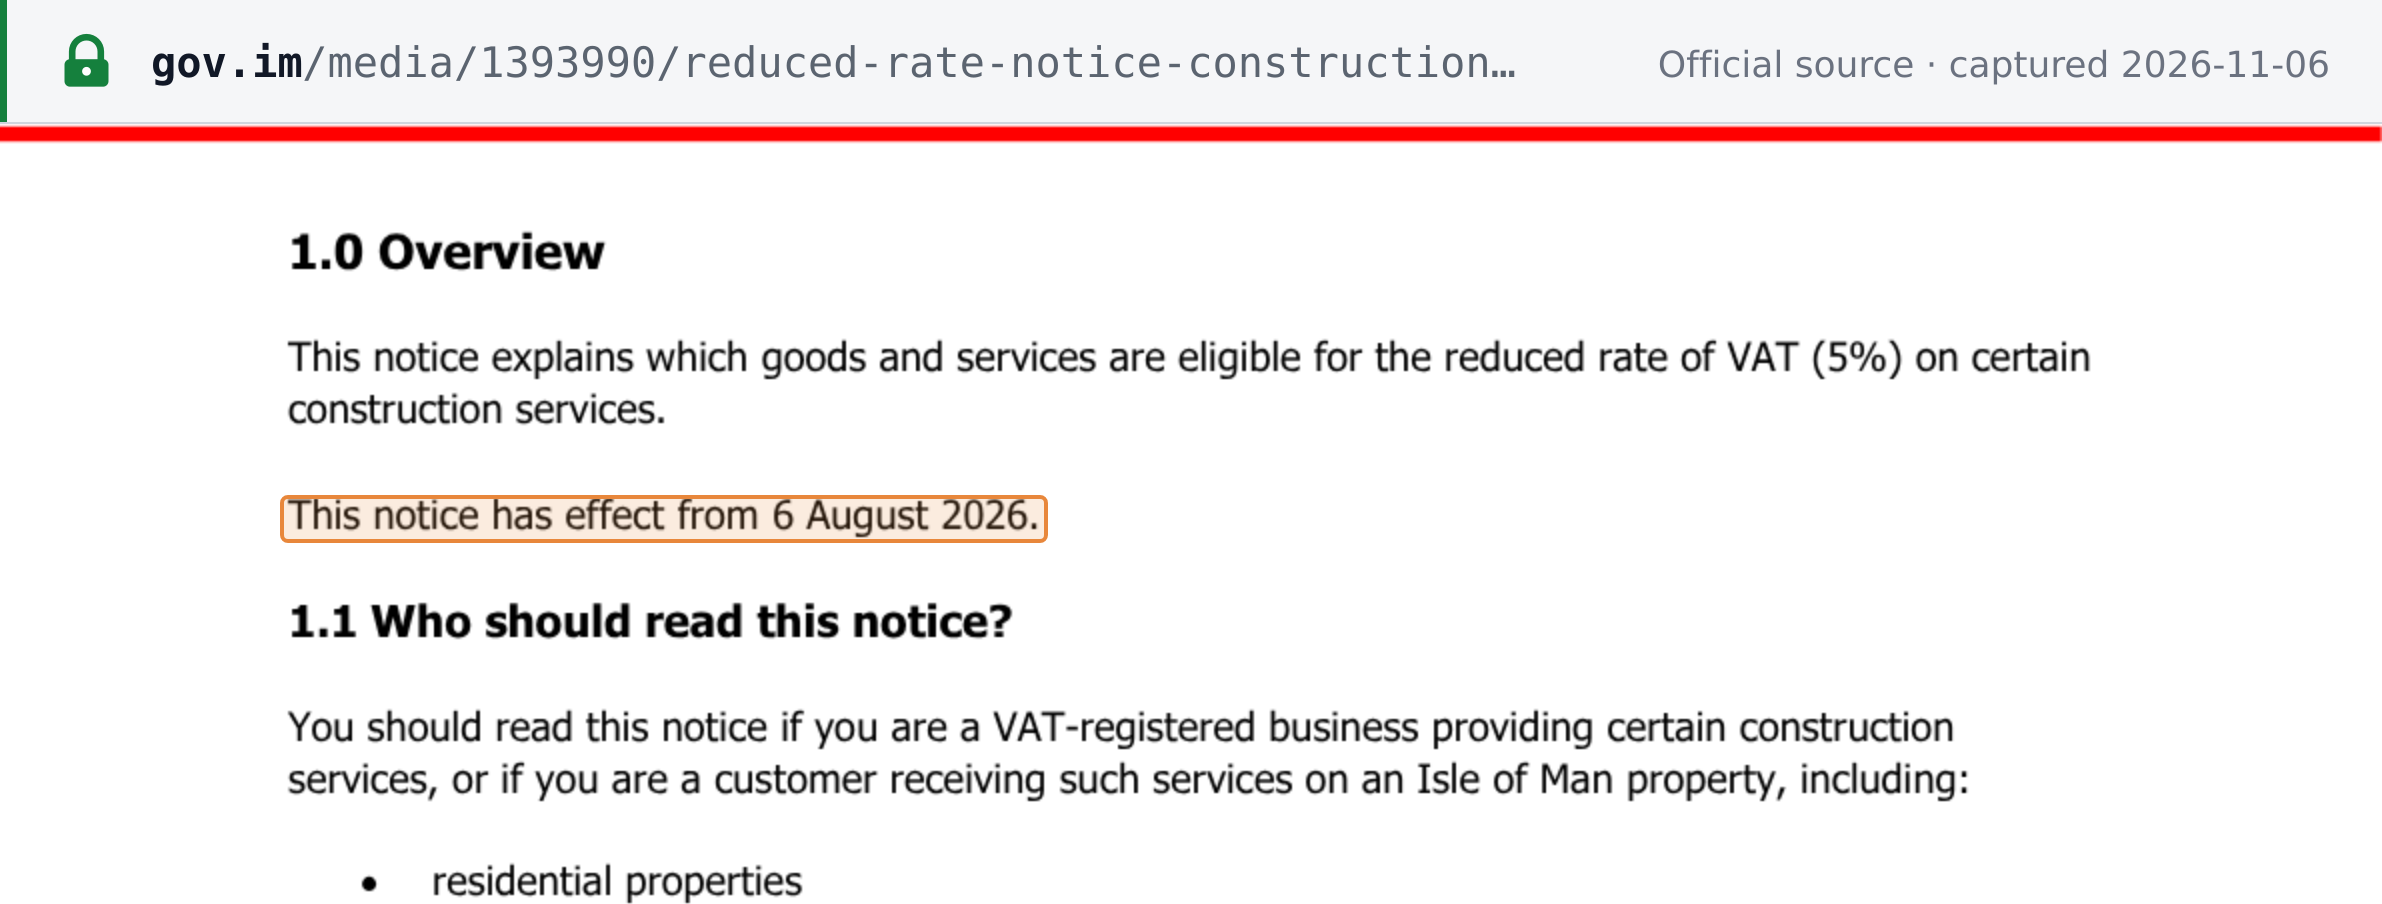
- Construction services on eligible buildings. VAT Notice 708 MAN: "This notice explains which goods and services are eligible for the reduced rate of VAT (5%) on certain construction services. This notice has effect from 6 August 2026." The relief covers "The supply by a taxable person of eligible services, including the supply of any necessary building materials at the same time, carried out on an eligible building in the Isle of Man" (Schedule 1, Group 14 to the Act). Eligible buildings are dwellings, relevant residential or charitable buildings and places of worship; eligible services include alterations, extensions, repairs, and the installation, repair or maintenance of building materials. "The person providing the services must be VAT-registered in either the Isle of Man or the United Kingdom". [11] The August 2026 version added manual blinds and electric vehicle charging points at eligible properties and removed artificial grass; the rate stayed at 5%. [12]
 Source snapshot captured 2026-11-06 — original
Temporary rates
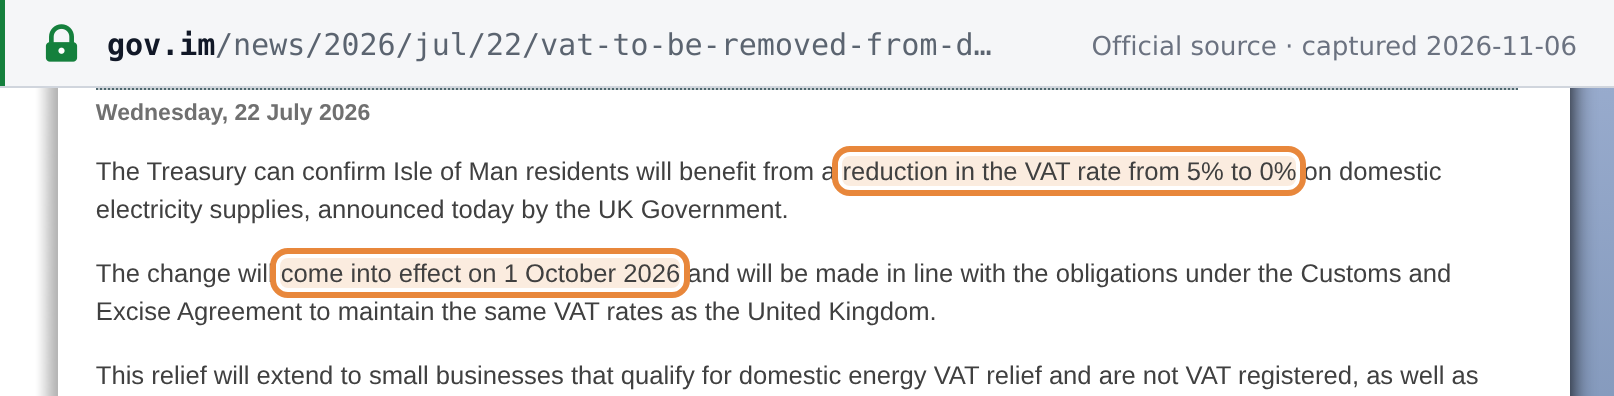
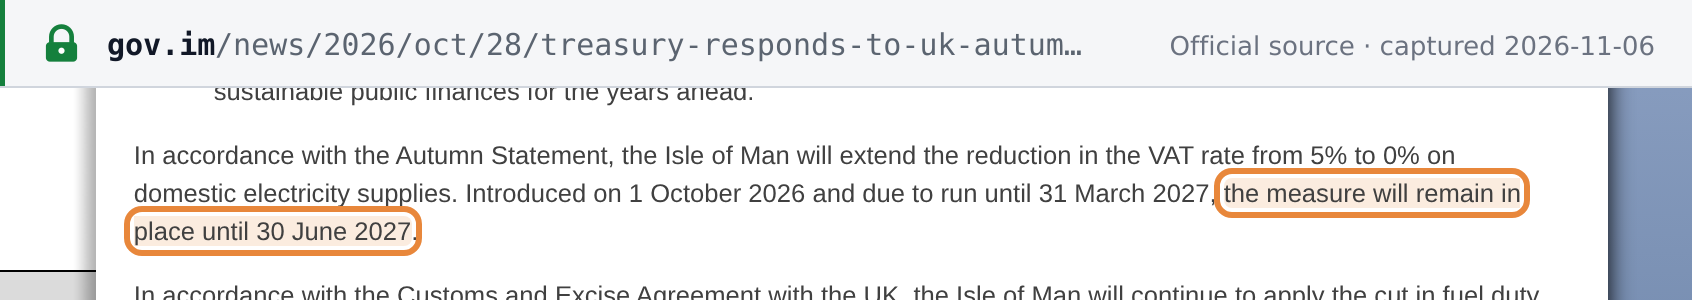
- Domestic electricity: 0% from 1 October 2026 to 30 June 2027. The Treasury cut the rate on domestic electricity supplies from 5% to 0% from 1 October 2026, "in line with the obligations under the Customs and Excise Agreement to maintain the same VAT rates as the United Kingdom". The relief also covers small businesses that are not VAT-registered and use below an average of 1,000 kWh a month, eligible charities and residential care homes. [13] On 28 October 2026 the Treasury announced: "Introduced on 1 October 2026 and due to run until 31 March 2027, the measure will remain in place until 30 June 2027." [14]
 Source snapshot captured 2026-11-06 — original
 Source snapshot captured 2026-11-06 — original
- Children's meals and family attractions: 5% from 25 June to 1 September 2026 (ended). VAT "on children's meals in restaurants, family tickets to cinemas, theatres and shows, and admission to attractions" fell "from 20% to 5% until 1 September 2026". [15] These supplies are back at the 20% standard rate.
Announced future rates. None beyond the end of the electricity relief on 30 June 2027. See the Isle of Man tax-changes chronology.
Cross-border rules
Imports and exports
- Great Britain ↔ Isle of Man. Not imports or exports. Customs: the Island "is treated as part of the UK for Customs, Excise and Value Added Tax (VAT) purposes. This means that most goods moving between the UK and the Island are not subject to customs formalities, and these goods are not considered to be imports or exports under customs law." [16] Charge VAT as on a sale within the UK.
- From outside the UK. "Goods brought directly to the Island from outside the UK are subject to customs controls", with import VAT. "Postponed VAT Accounting (PVAT) is available for use by Isle of Man VAT Registered traders." Moving goods needs "A valid Economic Operator Registration and Identification Number (EORI) that starts with 'GB'", and declarations go through the UK Customs Declaration Service. [16]
- Channel Islands. HMRC Notice 700 §4.7.3: "There's no VAT in the Channel Islands. Goods passing between the Channel Islands and the UK or the Isle of Man are imported or exported for VAT purposes." [2]
Place of supply of services
Customs sends traders to HMRC Notice 741A: "Find out how to determine the place of supply of your services and how to deal with supplies of services which you receive from outside the UK/Isle of Man: VAT Notice 741A – Place of supply of services guidance". [1] The UK and the Isle of Man are one territory for this purpose, so a service between the two is a domestic supply: HMRC Notice 700 §4.7.1 says that if you have customers or suppliers in the Isle of Man, "the VAT rules are the same as if they were in the UK". [2]
Reverse charge on imported services
An Isle of Man business that buys business services from outside the UK and the Isle of Man accounts for the VAT itself under the reverse charge. Customs' REG 9 MAN registration questionnaire (October 2026) asks applicants: "Do you expect to receive B2B services from outside the UK/IOM that you will need to account for under the reverse charge rules?" [17] See the reverse charge explained.
Domestic reverse charge — construction
Construction services within the Island can also be reverse-charged. Customs' Domestic Reverse Charge notice (July 2024): "The domestic Reverse Charge for the construction industry is an anti-avoidance measure which requires the customer who receives the services to account for the VAT due on these services on their VAT return rather than the supplier of the services." It applies where the services are reportable under the Construction Industry Scheme, are "subject to 20% or 5% VAT", and are not supplied to an end user. [18] Invoice wording is under Invoice requirements.
Foreign companies selling in — B2B and B2C
- B2B services. The Isle of Man business customer accounts for the VAT by reverse charge (above); under the general B2B place-of-supply rule (HMRC Notice 741A), the foreign supplier does not charge Manx VAT on those services.
- B2C, including digital services to Isle of Man consumers. A business based outside the UK that supplies goods or services to the UK, which here includes the Isle of Man, must register "regardless of taxable turnover" [6], normally with HMRC's non-established taxable persons unit rather than in the Isle of Man [4]. See VAT on digital services by non-resident suppliers.
Digital products and services
Customs reviews digital-service and intellectual-property businesses at registration with REG 9 MAN. The questionnaire asks whether services go "exclusively to UK/IOM customers", whether they are B2B or B2C, and about gambling exposure. [17] Customs publishes no separate Isle of Man threshold for digital services: the £90,000 threshold applies to Isle of Man-established businesses, and the no-threshold rule above to non-established ones.
Marketplace / platform deemed-supplier liability
Customs publishes no Isle of Man guidance on online marketplaces or low-value consignments. The UK's marketplace and £135 import rules are in the UK VAT Act 1994, which does not itself apply in the Island. Ask Customs before relying on the UK treatment for Isle of Man supplies.
Invoice requirements
Which rules apply. Customs states that most HMRC public notices are "also relevant for Isle of Man VAT registered traders" and links VAT Notice 700. [1] The invoice rules below therefore come from Notice 700 §16, plus three rules found only in Isle of Man notices.
 Source snapshot captured 2026-11-06 — original
Mandatory content
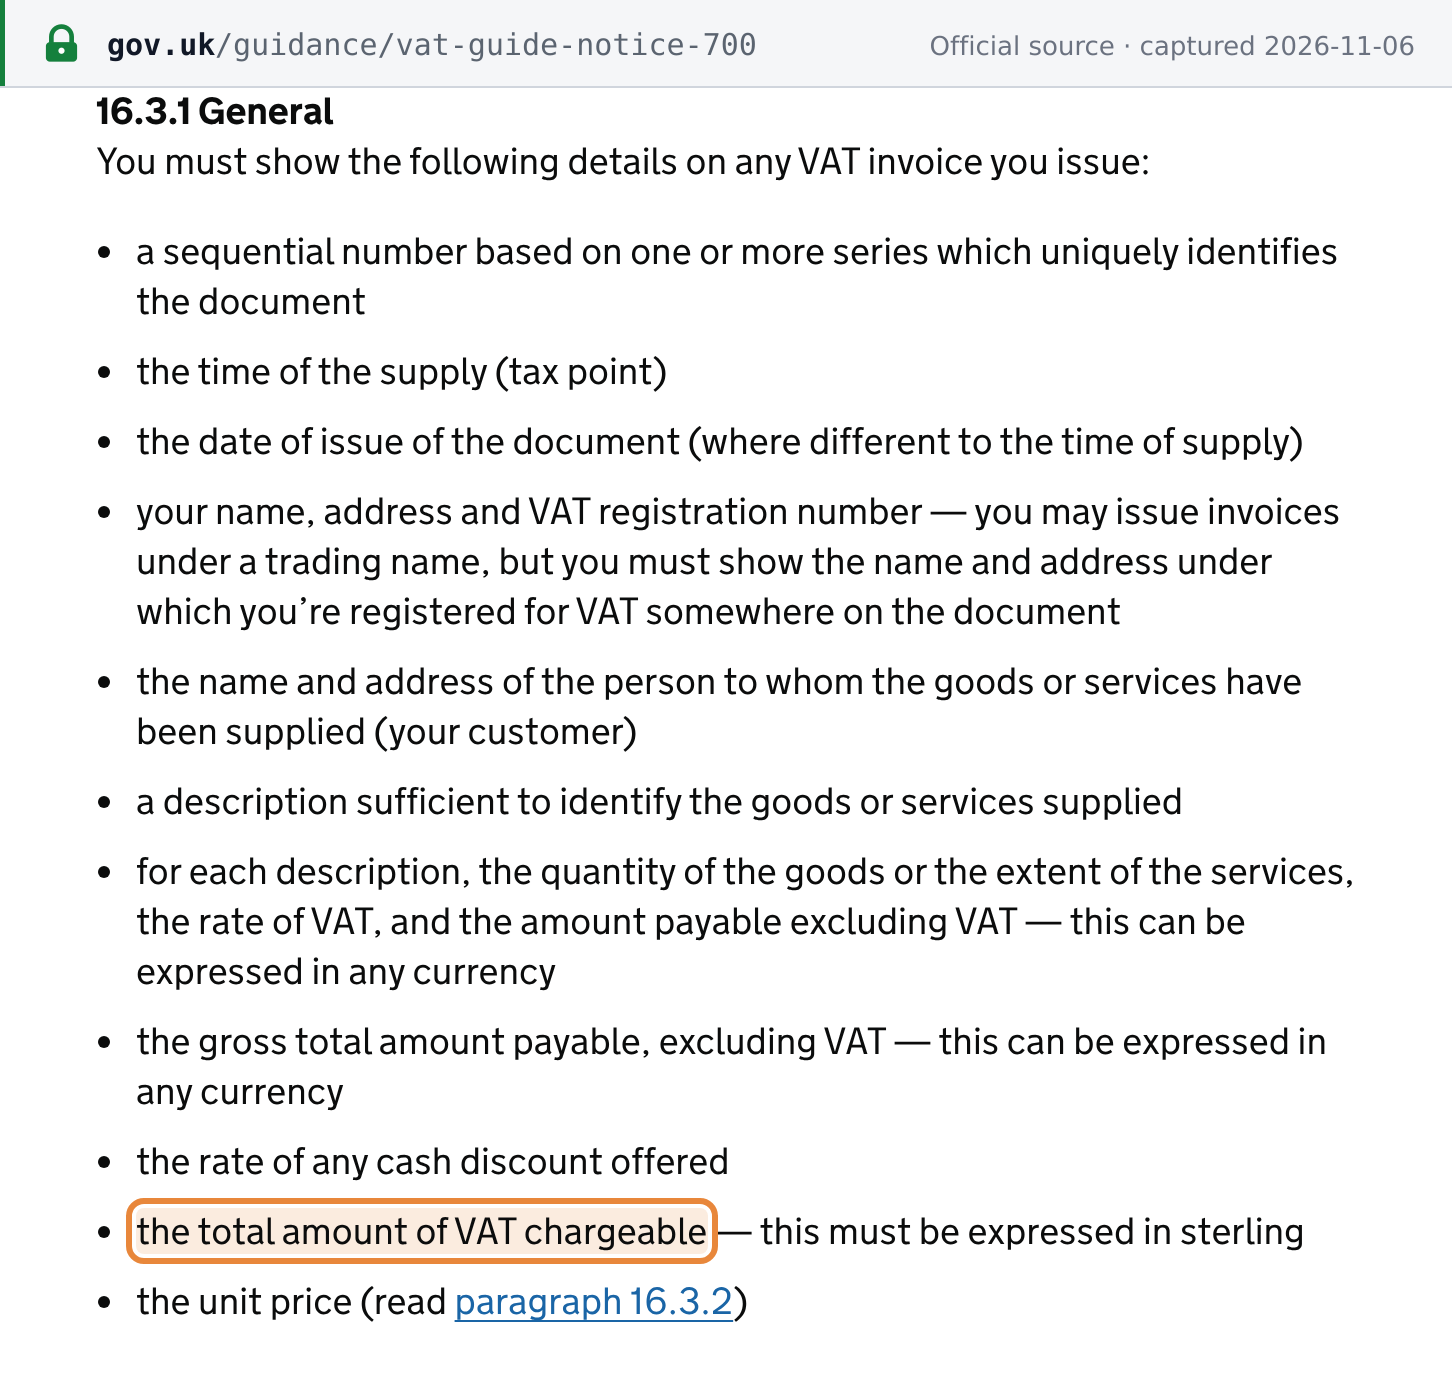
HMRC Notice 700 §16.3.1: "You must show the following details on any VAT invoice you issue": [2]
- A sequential number "based on one or more series which uniquely identifies the document".
- The time of the supply (tax point).
- The date of issue, "where different to the time of supply".
- Your name, address and VAT registration number. You may trade under another name, but the registered name and address must appear somewhere on the document.
- The customer's name and address.
- "a description sufficient to identify the goods or services supplied".
- For each description: the quantity or extent, the rate of VAT, and the amount payable excluding VAT (any currency).
- The gross total payable, excluding VAT (any currency).
- The rate of any cash discount offered.
- The total VAT chargeable, which "must be expressed in sterling".
- The unit price.
 Source snapshot captured 2026-11-06 — original
When an invoice is required, and the deadline
"Whenever you supply standard-rated or reduced-rated goods or services to another VAT-registered person, you must give that person a VAT invoice." Invoices are not required for zero-rated supplies, or for supplies to customers who are not VAT-registered. Issue the invoice within 30 days of the tax point (Notice 700 §16.2.1, §16.2.3). [2]
Isle of Man-only invoice rules
- Hotels and holiday accommodation at 5%. VAT Notice 709/3A MAN §4: "The total VAT actually charged must be shown on all tax invoices and the invoice must state clearly that the VAT rate is at the reduced rate on the qualifying element of the charge". It goes on: "The use of less detailed and modified tax invoices as detailed in HMRC VAT Notice 700, Section 16 is not permitted." [9] The £250 simplified invoice (below) is therefore not available for reduced-rate accommodation.
 Source snapshot captured 2026-11-06 — original
- Domestic reverse charge invoices. The Domestic Reverse Charge notice §7.1: "The Value Added Tax Regulations 1996 say invoices for services subject to the reverse charge must include the reference 'reverse charge'." Its examples of compliant wording are "VAT Act 1996 Section 55A applies", "S55A VATA 96 applies" and "Customer to pay the VAT to Customs and Immigration". [18] The supplier shows the rate but does not charge the VAT.
- Construction at 5%: itemise the 20% items. VAT Notice 708 MAN: white goods "must therefore be separately itemised on the VAT invoice and charged VAT at 20%", and "if you charge separately for the hire of scaffolding or a skip, these charges must be itemised separately on the VAT invoice and charged VAT at 20%." [11]
Numbering and sequencing
One or more series, each number unique to the document (Notice 700 §16.3.1). [2]
Credit and debit notes
When VAT is adjusted after a credit or contingent discount, "You should issue a credit note to your customer and keep a copy." (Notice 700 §18.2.1). [2]
Currency and language
- Currency. Line and total amounts excluding VAT may be in any currency; the VAT total must be in sterling. For foreign-currency invoices, "you must convert the total amount of VAT payable into sterling" (Notice 700 §16.4).
- Language. "You may write your invoices in a language other than English. You must be able to provide English translations of specific invoices within 30 days" when asked (§16.2.4). [2]
Document types
- Full VAT invoice: the particulars above.
- Simplified invoice: allowed when "the value of the supply you are making is £250 or less" and "your customer agrees" (Notice 700 §16.6.1). [2] It is not allowed for Isle of Man reduced-rate accommodation (709/3A MAN §4).
- Reverse charge invoice: construction services under the domestic reverse charge (above).
Self-billing
Permitted under the conditions in HMRC Notice 700/62, which Notice 700 §16.2.2 points to. [2]
Retention and audit trail
"Generally, you must keep all your business records for VAT purposes for at least 6 years." (HMRC Notice 700/21). [19] Customs may ask for records in a compliance check, and returns can be corrected online for up to four years back (see Filing and payment). Customs publishes no Isle of Man requirement for tamper-evident software, invoice hashes or digital links, and Making Tax Digital does not apply (see E-invoicing status).
A specimen of a compliant invoice
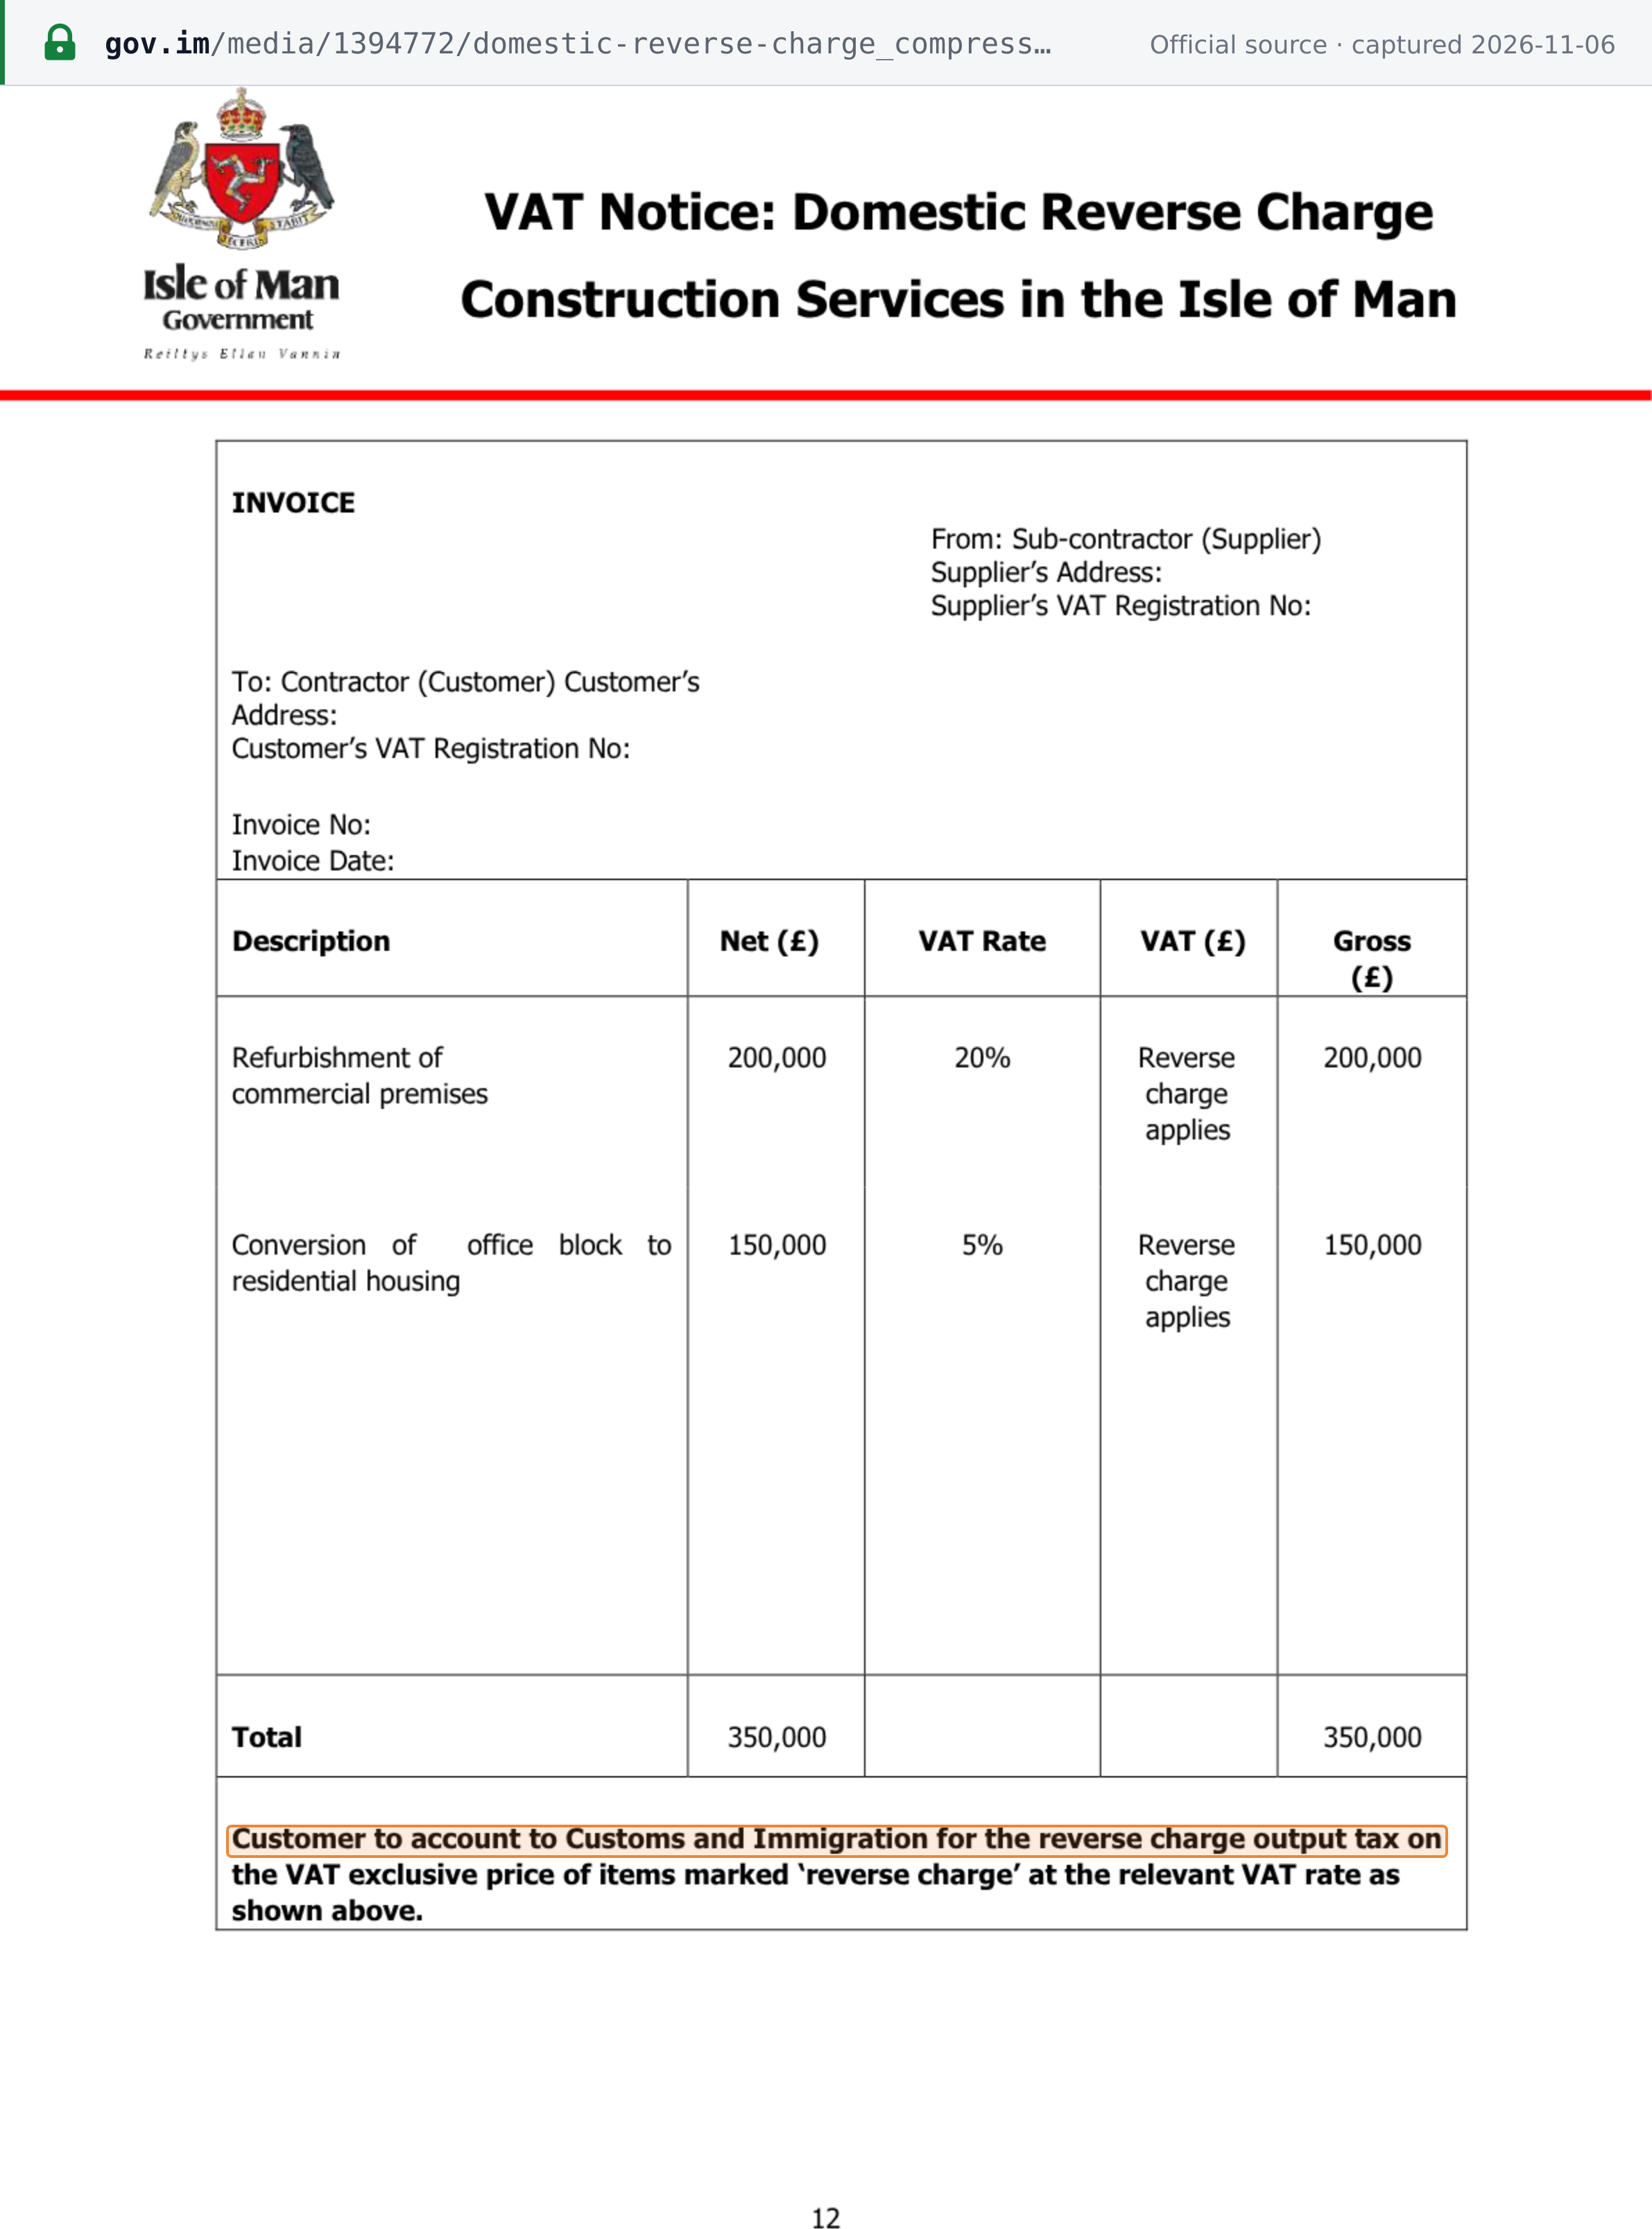
The authority's own model. Customs' Domestic Reverse Charge notice prints, as Annex C, an "Example of a reverse charge invoice": a sub-contractor's B2B invoice for construction work at 20% and 5% with "Reverse charge applies" in the VAT column and the customer-accounts note at the foot. [18] It is a specialised reverse-charge invoice, not a general one.
 Source snapshot captured 2026-11-06 — original
An ordinary VAT invoice. Customs publishes no specimen of an ordinary invoice. Below, Lookuptax lays out the Notice 700 §16.3.1 particulars for an Isle of Man guest house charging dinner, bed and breakfast, where the accommodation element is at 5% and the meals and drinks at 20%. Every name, number and amount is fictional:
VAT invoice — illustrative
| Descriptiondescription | Qtyquantity or extent | Amount excl. VATper line | VAT rateper line |
|---|---|---|---|
| Accommodation element of dinner, bed & breakfast tariff — reduced rate | 2 nights | £247.62 | 5% |
| Catering element (dinner and breakfast) of dinner, bed & breakfast tariff | 2 nights | £116.67 | 20% |
| Bar and drinks | 1 | £24.00 | 20% |
- Total excl. VATgross total excluding VAT
- £388.29
- VAT at 5% on £247.62
- £12.38
- VAT at 20% on £140.67
- £28.13
- Total VATmust be in sterling
- £40.51
- Total payable
- £428.80
- The reduced rate applies to the accommodation element only; the invoice must say so — VAT Notice 709/3A MAN §4.
- Less detailed (simplified) and modified invoices may not be used for reduced-rate accommodation — VAT Notice 709/3A MAN §4.
- Issue within 30 days of the tax point — Notice 700 §16.2.3.
- Keep for at least 6 years — Notice 700/21.
E-invoicing status
None as at 2026-11-06. Customs and Excise publishes no e-invoicing, clearance (CTC) or Peppol requirement, and names no e-invoicing system, network, format or phase timeline. No B2B, B2G or B2C mandate applies. VAT returns are filed through the gov.im VAT Online Portal, not HMRC's Making Tax Digital service. Customs has said nothing about whether the Island will follow the UK's own e-invoicing plans; for the UK position, see e-invoicing in the United Kingdom.
Filing and payment
Filing and payment online
Returns and payments are online by default: "All VAT registered customers are required to submit their VAT returns and make any payments due to the Isle of Man Treasury, Customs & Immigration Division electronically." Exemptions are available on application, for example during insolvency, on religious grounds, or where age, disability or location make online filing impractical. [20] The filing channel is the Customs and Excise Online Services "VAT Online Portal, where registered taxpayers can file a VAT return and make payments." [1]
Filing frequency
VAT 1 MAN guidance notes §14: "Most VAT registered businesses choose quarterly VAT returns and often prefer to align this with the business year end". "Quarterly returns follow one of 3 frequencies, ending of the last day of – • January, April, July, October; February, May, August, November; or • March, June, September, December. Monthly VAT returns may help if your business is always in a VAT repayment position." Annual returns are available under the Annual Accounting Scheme (Notice 732). [21]
Return due date
Customs does not publish a general due-date rule. Each return in the VAT Online Portal shows its own due date; file and pay by that date.
Payment due date and method
Payment must reach Customs' bank account by the deadline. "If the deadline falls on a weekend or bank holiday, your payment must arrive in Customs bank account on the last working day before the deadline", and electronic receipts after 5:30pm are dated the next working day. Methods are "'Faster Payments' using online banking", CHAPS, debit or credit card through Online Services, BACS credit transfer, and standing order for time-to-pay, annual accounting or payments on account. "Important: please remember to use your TIN or VAT number as the payment reference." [22]
Corrections
Since June 2026, "VAT returns can be amended up to a maximum of four years prior to the current date" online; otherwise use form VAT 652 MAN. [23]
Additional listings
None published: Customs requires no listing alongside the VAT return.
Input-tax recovery and blocked items
As in the UK, under Notice 700 as applied by gov.im; motoring and fuel scale charges follow HMRC Notice 700/64, which gov.im links. [1]
Capital Goods Scheme. Simplified from 29 July 2026: "Computers and any computer equipment will no longer be covered by the CGS, regardless of value The expenditure threshold for land, buildings and civil engineering works will increase from £250,000 to £600,000 (excluding VAT)". "The new rules apply where capital expenditure is incurred on or after 29 July 2026." [3]
Refunds
- Repayments to registered businesses. By cheque or BACS to an account in the business's name. "Repayments cannot be made to overseas bank accounts." [22] The bank account given at registration "Must be a UK clearing bank" (VAT 1 MAN guidance §15). [21]
- Bodies that cannot register. Local authorities, public bodies and eligible charities claim on form VAT 126 MAN. [1]
- Non-resident refunds. Customs publishes no refund route for overseas businesses that are not VAT-registered.
Exemptions
Exempt supplies
"Some things are exempt from VAT such as health services, financial services, property transactions and postage stamps. These are known as 'exempt supplies'. If you only make exempt supplies you cannot register for VAT." [1]
Exempt is not zero-rated. Zero-rated supplies are taxable supplies at 0%: they count towards the £90,000 threshold, and VAT on the costs of making them is recoverable. Exempt supplies are outside that: they do not count as taxable supplies, and the input tax on them is not recoverable. See zero-rated vs exempt.
Special regimes
- Flat Rate Scheme (VAT 600 FRS MAN), Annual Accounting Scheme (VAT 600 AA MAN) and Cash Accounting Scheme (no application needed). [4]
- Tour Operators' Margin Scheme, with Isle of Man reduced-rate accommodation, under VAT Notice 709/5 MAN. [10]
- Domestic reverse charge for construction services (see Cross-border rules). It cannot be combined with cash accounting. [18]
Offences and penalties
Offences
Customs' Compliance, Powers and Appeals page lists factsheets on penalties for VAT and excise wrongdoing, VAT dishonest conduct and transactions connected with VAT fraud. [24] The criminal offences and their sentences are in the Value Added Tax Act 1996 and are not summarised here.
Penalties
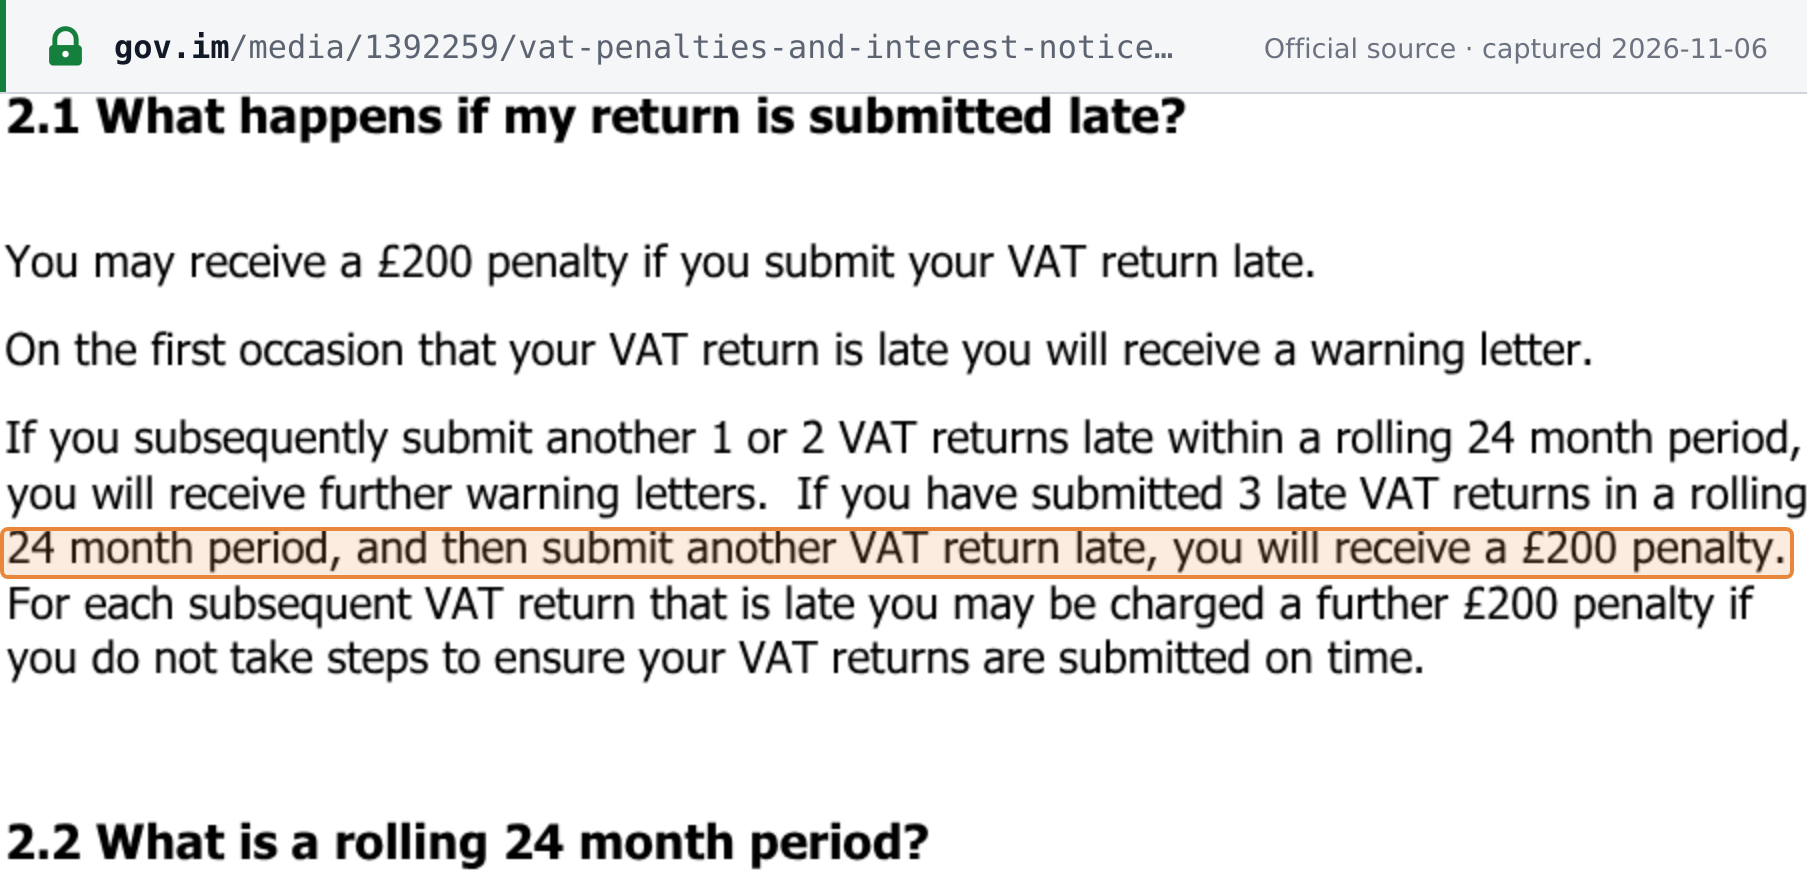
- Late returns (accounting periods starting on or after 1 January 2023). "On the first occasion that your VAT return is late you will receive a warning letter. If you subsequently submit another 1 or 2 VAT returns late within a rolling 24 month period, you will receive further warning letters. If you have submitted 3 late VAT returns in a rolling 24 month period, and then submit another VAT return late, you will receive a £200 penalty." Each later late return may bring a further £200. The law is in sections 59ZA, 59ZB and 75 of, and Schedules 15B to 15F to, the Value Added Tax Act 1996. [25] This is a warning-letter system, not the UK's points system.
 Source snapshot captured 2026-11-06 — original
- Late payment. "On day 16 a penalty of 3% of any unpaid VAT will be incurred." If VAT is still unpaid after 30 days and there is no Time to Pay agreement, the penalty is 3% of the VAT due on day 16 plus 3% of the VAT outstanding at day 31. "From day 31 you will begin to incur an additional penalty accruing on a daily basis at a rate of 10% per annum of the VAT outstanding at day 31 until the amount is fully paid." [25]
- Interest. Late payment interest is 7.75% a year from 1 May 2026, rising to 8% from 24 November 2026. Repayment interest is 2.75% a year from 8 January 2026, rising to 3% from 24 November 2026. [26] [22]
- Inaccuracies and failure to notify. Customs factsheets 7a (inaccuracies in returns and documents), 7b (failure to tell Customs about an under-assessment), 10 (suspending penalties for careless inaccuracies) and 11 (failure to notify) set these penalties. [24]
- Appeals. "A VAT registered person can challenge a penalty relating to late VAT returns or late payments through both an internal review process and an appeal to the VAT and Duties Tribunal." [25]
Frequently asked questions
We are VAT-registered in the UK. Do we also need to register for VAT in the Isle of Man?
No. The UK and the Isle of Man form a single area for VAT, and HMRC's VAT Registration Manual (VATREG45200) states that persons may only be registered in either the UK or the Isle of Man at any one time. A person with an establishment only in the UK registers in the UK; one with an establishment only in the Isle of Man registers in the Isle of Man; where there are establishments in both, or in neither, HMRC decides the country in consultation with the Isle of Man service.
Why does our Isle of Man supplier's VAT number start with GB 00?
Isle of Man VAT numbers are in the same nine-digit series as UK VAT registration numbers but are held on a separate Isle of Man register, identified by the first two digits being 00 (HMRC VATREG45100). They are shown with the GB prefix and can be checked with HMRC's Check a UK VAT number service. They are not EU VAT numbers, so VIES does not apply.
Can a UK builder charge 5% VAT on repairs to a house in the Isle of Man?
Yes, if the work is an eligible service carried out on an eligible building in the Isle of Man. VAT Notice 708 MAN (effective 6 August 2026) says the person providing the services must be VAT-registered in either the Isle of Man or the United Kingdom. The same repair work on a property in Great Britain is normally standard-rated at 20%, because this 5% construction rate is an Isle of Man-only rate.
Can an Isle of Man hotel give a simplified VAT invoice for a room charged at 5%?
No. VAT Notice 709/3A MAN section 4 requires the total VAT actually charged to be shown on all tax invoices, and the invoice must state clearly that the VAT rate is the reduced rate on the qualifying element of the charge. It adds that the use of less detailed and modified tax invoices as detailed in HMRC VAT Notice 700, Section 16 is not permitted.
Do sales of goods from Great Britain to the Isle of Man need export evidence for zero-rating?
No. HMRC VAT Notice 700 paragraph 4.7.1 says that for VAT purposes the Isle of Man is treated as part of the UK, and that goods sent from Great Britain to the Isle of Man or vice versa do not count as imports or exports for VAT purposes. Charge VAT as you would on a sale within the UK. Goods moving between the Isle of Man and the Channel Islands are different: they are imported or exported for VAT purposes.
Can Isle of Man Customs pay a VAT repayment into a non-UK bank account?
No. The Customs and Excise Payments page states that repayments cannot be made to overseas bank accounts. Repayments go by cheque or BACS to an account in the business's name, and the VAT 1 MAN guidance notes say the bank account given at registration must be a UK clearing bank.
Important websites
| Site | Purpose |
|---|---|
| Customs and Excise — VAT | VAT hub: rates, notices, forms |
| Registering for VAT | Register online or with VAT 1 MAN (registration.customs@gov.im) |
| Customs and Excise Online Services | VAT Online Portal: file returns and pay |
| Payments | Payment methods, deadlines, interest rates |
| Correcting a VAT return error | Amend a return |
| De-registering for VAT | Cancel a registration (VAT 7 MAN) |
| Check a UK VAT number | Verify GB00 Isle of Man VAT numbers (HMRC) |
| VAT rates on different goods and services | Item-by-item rate lookup, shared with the UK except the Isle of Man-only rates |
| Imports and exports | EORI, customs declarations, postponed VAT accounting |
| E-invoicing portal | None (no mandate) |
Recent changes
- 2026-11-05 — The Treasury announces that late payment interest rises to 8% and repayment interest to 3% from 24 November 2026. (Isle of Man Treasury, 5 November 2026)
- 2026-10-28 — The 0% rate on domestic electricity, due to end on 31 March 2027, is extended to 30 June 2027. (Isle of Man Treasury)
- 2026-10-01 — VAT on domestic electricity falls from 5% to 0%. (Isle of Man Treasury) — see event
- 2026-08-06 — Updated VAT Notice 708 MAN: manual blinds and EV charging points added to the 5% construction rate, artificial grass removed. (Isle of Man Treasury)
- 2026-07-29 — Capital Goods Scheme simplified: computers removed, land and buildings threshold raised to £600,000. (Isle of Man Treasury)
- 2026-06-25 — Temporary 5% on children's meals, family tickets and attractions, until 1 September 2026. (Isle of Man Treasury) — see event
For the full chronology, see Isle of Man tax changes on Lookuptax.
Reference links
- Isle of Man Government — Customs and Excise, VAT
- HMRC — VAT Notice 700: the VAT guide
- Isle of Man Treasury — Simplification of the Capital Goods Scheme (29 July 2026)
- Isle of Man Government — Registering for VAT
- HMRC VAT Registration Manual — VATREG45200
- GOV.UK — When to register for VAT
- HMRC VAT Registration Manual — VATREG45100
- Isle of Man Government — De-registering for VAT
- VAT Notice 709/3A MAN — Reduced Rate: Hotel Accommodation and Similar Establishments (July 2024)
- VAT Notice 709/5 MAN — Tour Operators' Margin Scheme
- VAT Notice 708 MAN — Reduced Rate: Construction Services (6 August 2026)
- Isle of Man Treasury — Updated VAT guidance for construction services (7 August 2026)
- Isle of Man Treasury — VAT to be removed from domestic electricity supplies from 1 October 2026 (22 July 2026)
- Isle of Man Treasury — Treasury responds to UK Autumn Statement (28 October 2026)
- Isle of Man Treasury — Fun and fuel VAT boost (26 May 2026)
- Isle of Man Government — Imports and exports
- REG 9 MAN — VAT digital services registration questionnaire (October 2026)
- VAT Notice — Domestic Reverse Charge: Construction Services in the Isle of Man (July 2024)
- HMRC — Record keeping for VAT (Notice 700/21)
- Customs — VAT online exemption guidance (July 2026)
- VAT 1 MAN guidance notes (April 2026)
- Isle of Man Government — Customs and Excise payments
- Isle of Man Treasury — Online VAT return corrections (June 2026)
- Isle of Man Government — Compliance, powers and appeals
- Customs — VAT Penalties and Interest (March 2026)
- Isle of Man Treasury — Increase in interest rates for VAT and other indirect taxes (5 November 2026)
Related on Lookuptax: