E-invoicing in Bulgaria: consent-based today, a mandate proposed for July 2028
Overview
Bulgaria has no B2B or B2C e-invoicing mandate and no clearance or real-time reporting system in force. Under the VAT Act (Закон за данък върху добавената стойност, ЗДДС) an electronic invoice is optional: supplies may be documented by e-invoices "при условие че това документиране се приема от получателя с писмено или мълчаливо съгласие" (provided the recipient accepts this by written or tacit consent) (art. 114(9)). The consolidated VAT Act, current to State Gazette 115/2025, contains no e-invoicing obligation and no clearance system. (ЗДДС, consolidated text hosted by ДАМТН, checked 2026-09-30)
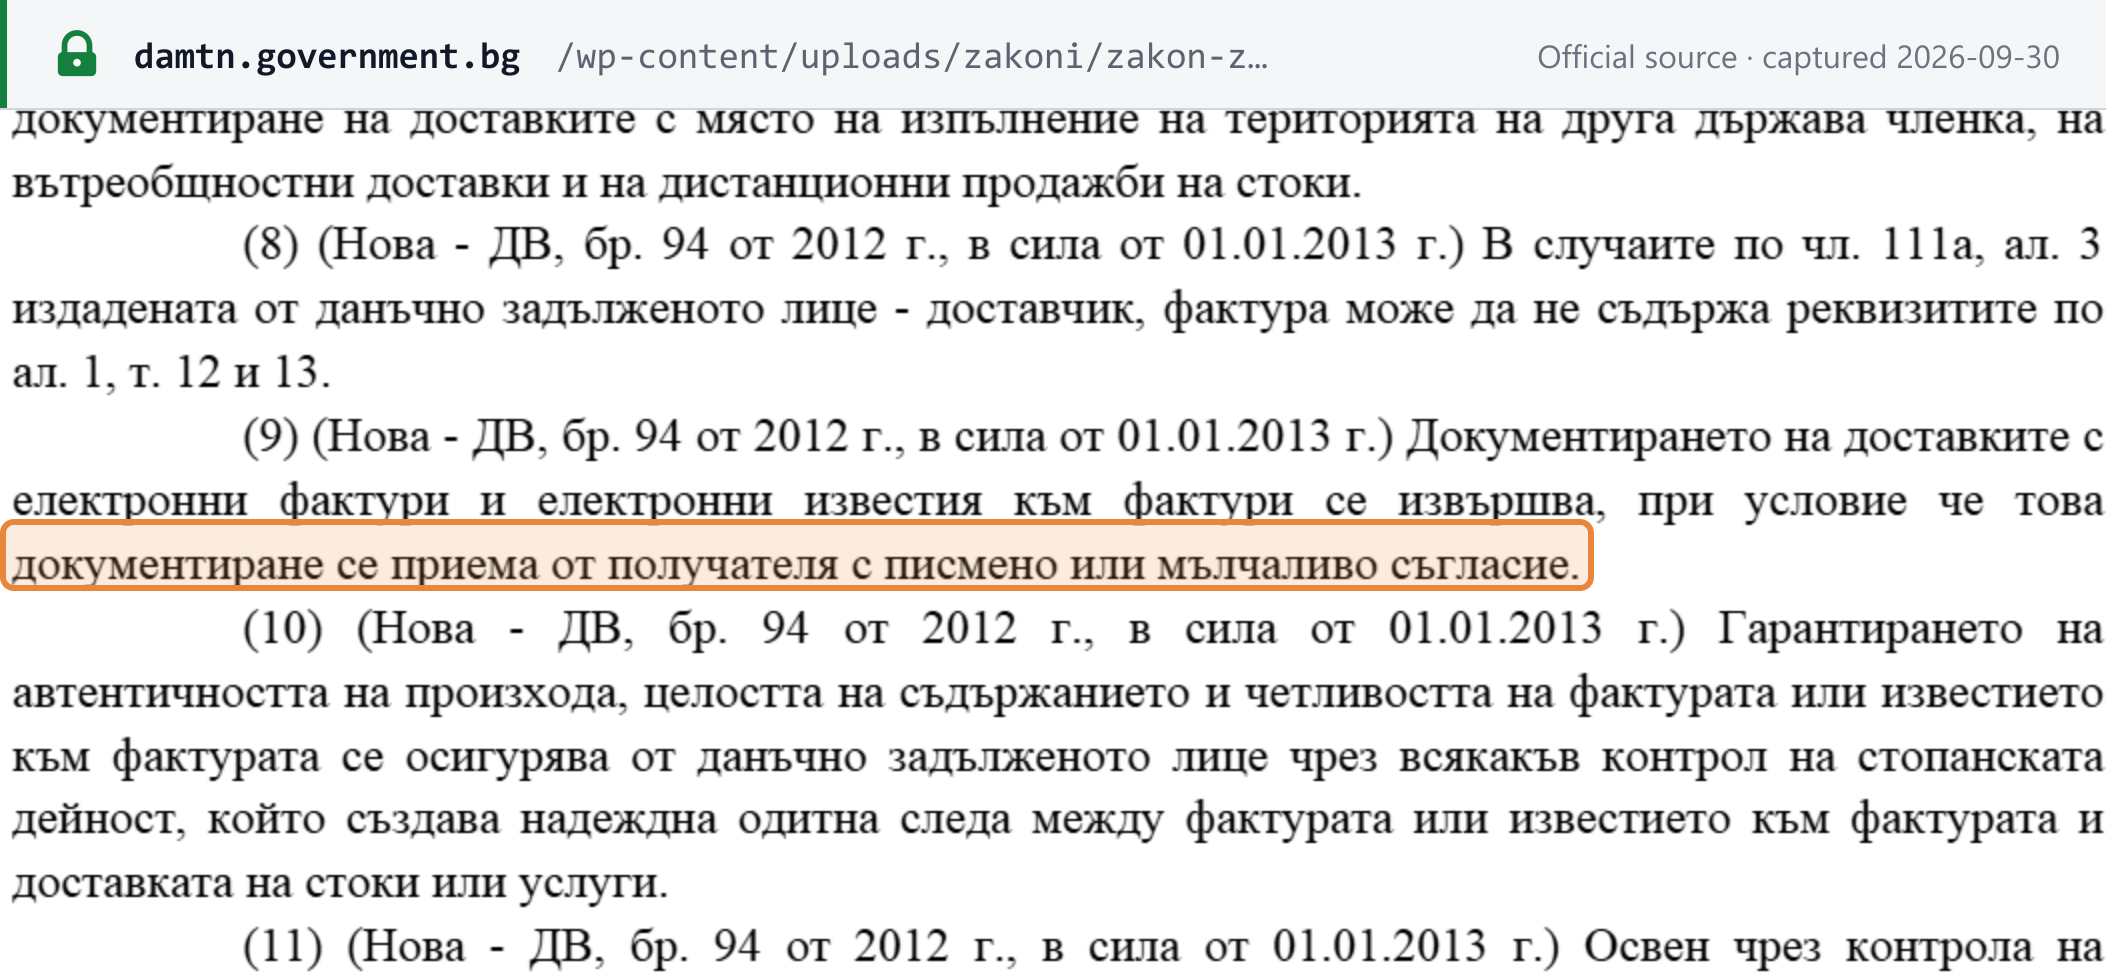 Source snapshot captured 2026-09-30 from the consolidated text (Ciela export of 09.07.2026) — original
Two layers sit on top of that baseline:
- B2G, in force. Since 1 November 2019 contracting authorities must accept and process e-invoices that meet the European standard EN 16931 (Public Procurement Act, Закон за обществените поръчки, ЗОП, art. 115a). The duty falls on the public buyer. Suppliers are not obliged to send e-invoices.
- B2B and B2G supplier mandate, proposed. On 5 November 2026 the government submitted to the National Assembly (Народно събрание) a bill amending the VAT Act (ЗИД на ЗДДС, reference 52-602-01-60), approved by Council of Ministers Decision No. 843 of 2026. It proposes that VAT-registered suppliers established in Bulgaria issue structured e-invoices to EN 16931, exchanged over a decentralised network with invoice data reported to the National Revenue Agency (Национална агенция за приходите, НАП/NRA) at the moment of issue. The NRA's national data-submission system and national structured e-invoicing portal would go live "в реална среда от 1 юли 2028 г." (in a live environment from 1 July 2028), after a test period from 1 January to 30 June 2028. The National Assembly adopted the bill at first reading on 12 November 2026; proposals for second reading were due by 18 November 2026. It is not law until adopted at second reading and promulgated in the State Gazette. Every date, figure and rule of the bill on this page is a proposal.
The bill replaces the Ministry of Finance consultation draft of 23 September 2026, which proposed centralised clearance with an NRA "unique compliance code" from 1 January 2028. Its explanatory memorandum says that, after the public consultation, "първоначално предложеният задължителен централизиран модел на валидиране и обмен (clearance) беше заменен с децентрализиран модел на оперативна съвместимост" (the originally proposed mandatory centralised validation and exchange model (clearance) was replaced with a decentralised interoperability model). The NRA, together with the Ministry of Innovation and Digital Transformation, would run a public national register of e-invoice receiving addresses. No portal, register or sandbox is published yet. (Bill 52-602-01-60 with explanatory memorandum, National Assembly; bill page, checked 2026-11-18)
| Bulgaria (as at 2026-11-18) | |
|---|---|
| B2B (domestic) | No mandate. E-invoices only with the buyer's written or tacit consent (ЗДДС art. 114(9)). Proposed: mandatory structured e-invoices from 1 July 2028 (bill 52-602-01-60) |
| B2G | Contracting authorities must accept and process EN 16931 e-invoices since 1 November 2019 (ЗОП art. 115a); no supplier-side duty. Proposed: supplier-side duty from 1 July 2028, including for unregistered established suppliers |
| B2C | No mandate. Proposed: supplies to individuals stay outside the mandate |
| Non-residents | No mandate. Proposed: VAT-registered suppliers not established in Bulgaria are excluded |
| Model | Today: none (consent-based exchange). Proposed: decentralised exchange (4- or 5-corner) through accredited providers, own software or the NRA portal, with invoice data reported to the NRA at issue |
| Format | B2G: EN 16931 (Implementing Decision (EU) 2017/1870) "or an equivalent standard". Proposed: EN 16931, full automatic exchange in XML UBL 2.1 and CII |
| Network | Not Peppol. B2G: optional central platform CAIS EOP (ЦАИС ЕОП) or each authority's own system. Proposed: a standardised secure exchange network on CEF eDelivery with the AS4 profile; delivery only to the address in the national register |
| Authority | B2G: Public Procurement Agency (АОП) runs CAIS EOP. Proposed B2B/B2G: National Revenue Agency (portal, register, data), policy by the Ministry of Finance |
| Legislation | ЗДДС art. 113(12), 114(6)–(11), 121; ЗОП art. 36(3), 39a and 115a (State Gazette 86/2018, 107/2020). Bill ЗИД на ЗДДС 52-602-01-60 (5 November 2026) |
Mandate status & timeline
Status (as at 2026-11-18): no B2B or B2C mandate in force. B2G receive-and-process duty in force since 1 November 2019. Supplier-side structured e-invoicing proposed from 1 July 2028 in a bill before the National Assembly; not law.
| Date | Scope | What | Status | Legal basis |
|---|---|---|---|---|
| 1 January 2013 | B2B, B2C, all | E-invoices allowed with the recipient's written or tacit consent; authenticity and integrity by business controls | in force | ЗДДС art. 114(9)–(11), State Gazette 94/2012 [1] |
| 1 March 2019 | B2G | Public Procurement Act definition of "electronic invoice": a structured format that allows automatic processing | in force | ЗОП § 2 item 10a, State Gazette 86/2018 [2] |
| 1 November 2019 | B2G, all contracting authorities | Authorities must accept and process EN 16931 e-invoices; suppliers are not obliged to send them | in force (passed) | ЗОП art. 115a; State Gazette 86/2018 § 65, § 141 [2] |
| 1 January 2021 | B2G | CAIS EOP mandatory for tendering; submitting and receiving e-invoices through it optional | in force | ЗОП art. 39a(4)–(5), State Gazette 107/2020 [3] |
| 23 September – 23 October 2026 | — | Ministry of Finance consultation draft (clearance model, 1 January 2028) | superseded by the bill | strategy.bg [4] |
| 5 November 2026 | — | Government bill 52-602-01-60 submitted to the National Assembly | passed first reading 12 November 2026; second reading pending | National Assembly [5] |
| 12 November 2026 | — | Bill adopted at first reading by the National Assembly | passed first reading | National Assembly [5] |
| 1 January 2027 | VAT registration | National registration threshold EUR 60,000 (replacing EUR 51,130); EUR 70,000 from 1 January 2028; EUR 75,000 from 1 January 2029 | proposed | bill § 25 (new art. 96(7)) [6] |
| By 1 July 2027 | — | Joint ordinance on technical standards, exchange and digital reporting (art. 120a(9)) | proposed | bill § 106 [6] |
| 1 January – 30 June 2028 | VAT-registered persons | Test environment for the national data-submission system and portal; national register of receiving addresses runs from 1 January 2028 | proposed | bill § 105(1)–(2) [6] |
| By 30 June 2028 | Persons VAT-registered at 1 January 2028 | Declare an electronic address for receiving structured e-invoices in the national register | proposed | bill § 104 [6] |
| 1 July 2028 | Bulgaria-established VAT-registered suppliers, domestic supplies to established taxable persons, non-taxable legal persons and public bodies; unregistered established suppliers for supplies to public bodies | Mandatory structured e-invoice; data reported to the NRA at issue; input VAT tied to a structured e-invoice; purchase and sales ledgers abolished; prefilled VAT returns; software-maker penalty | proposed | bill §§ 7, 33, 40, 43–44, 97, 109(1) [6] |
| 1 January 2029 | Issuers | Penalty for not issuing a structured e-invoice (new art. 182a) | proposed | bill § 84, § 109(2) [6] |
| 1 July 2030 | Intra-EU supplies | EU cross-border e-invoicing and digital reporting under ViDA | not transposed by this bill | Directive (EU) 2025/516 |
Latest development: the bill of 5 November 2026
The government submitted the bill amending the VAT Act to the National Assembly on 5 November 2026 (incoming reference 52-602-01-60), with the Council of Ministers' approval (Decision No. 843 of 2026). The lead Budget and Finance Committee reported on it on 10 November 2026 and the National Assembly adopted it at first reading on 12 November 2026 (122 for, 49 against, 18 abstentions), shortening the deadline for amendments to 18 November 2026. Next come the committee's second-reading report, the second reading and promulgation in the State Gazette (Държавен вестник). Any point of the bill can still change. (National Assembly — bill page, checked 2026-11-18)
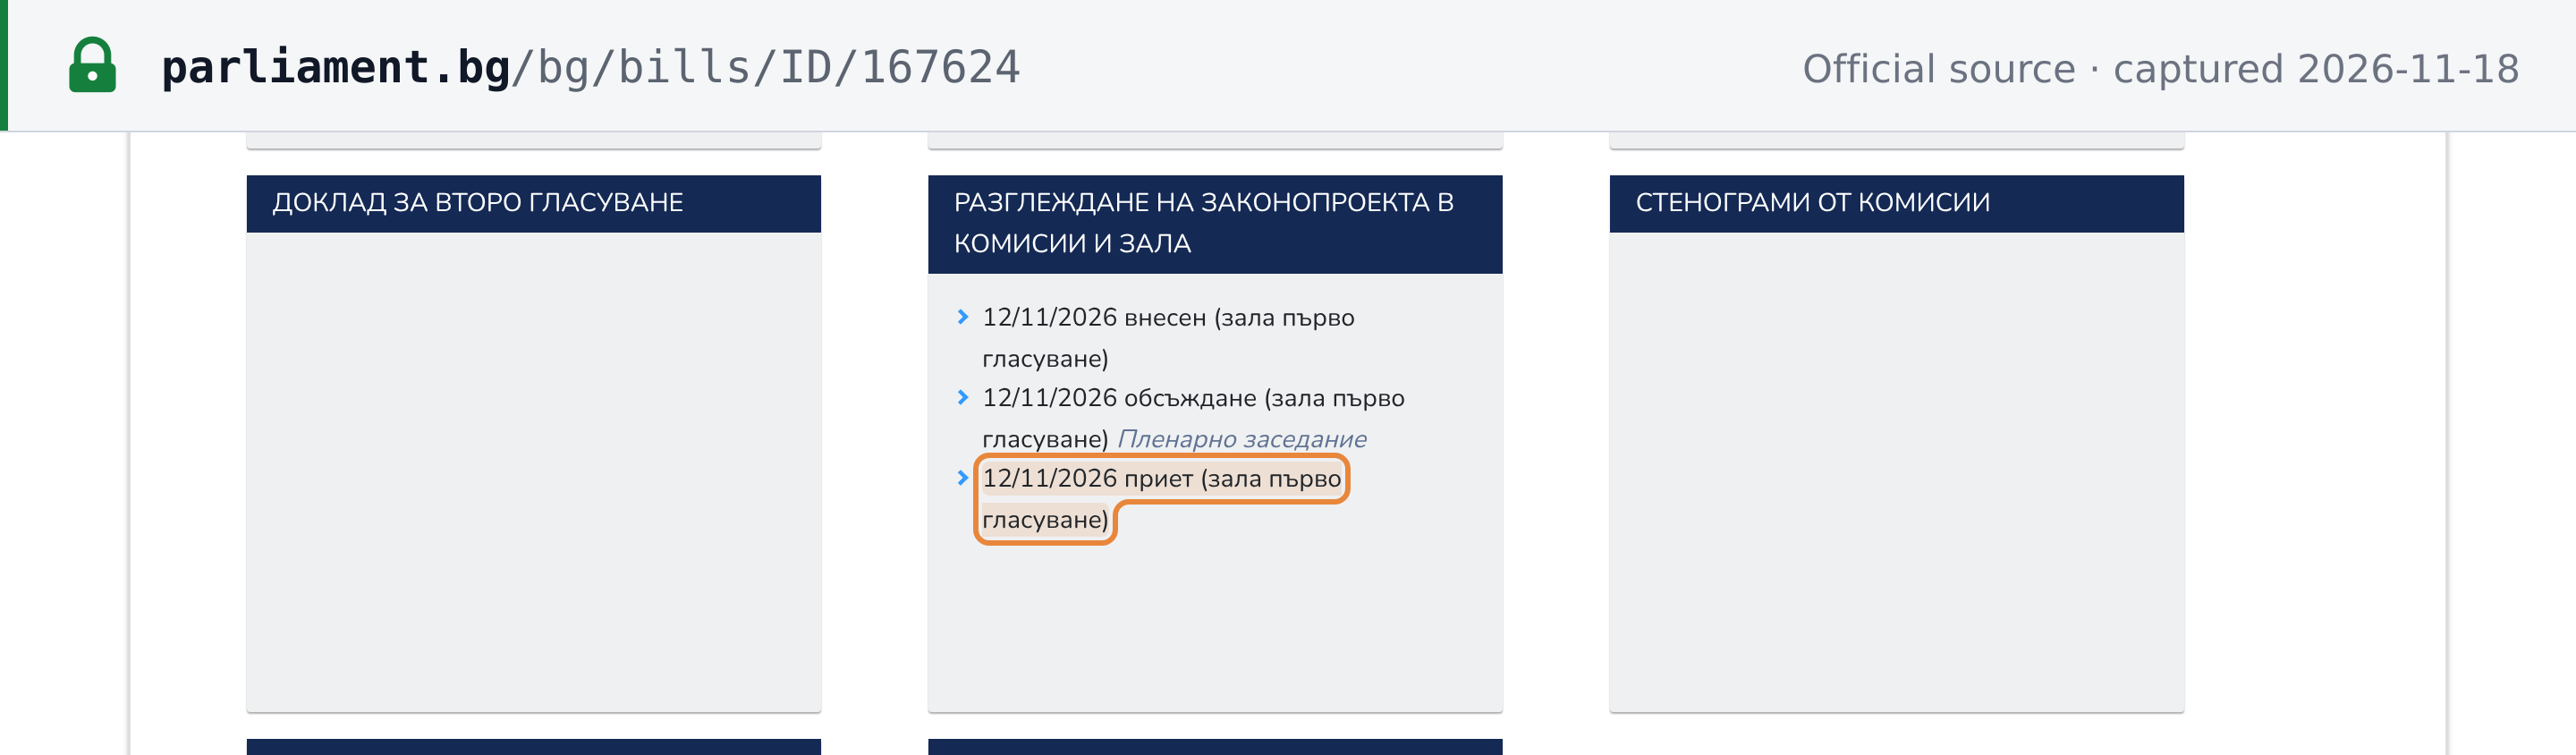 Source snapshot captured 2026-11-18 from the National Assembly bill page — original
The bill's commencement clause brings the Act into force on 1 January 2027 for other measures, among them the phased national registration threshold (see below). It holds back the e-invoicing block, including the new chapter 11a (arts 120a–120d), art. 113(16)–(22) and the repeal of the ledgers in art. 124(1)–(6), until 1 July 2028, and the issuer penalty in art. 182a until 1 January 2029. Transitional § 105(3) reads: "Националната информационна система за подаване на данни и националният портал за структурирано електронно фактуриране започват да функционират в реална среда от 1 юли 2028 г." (The national data-submission system and the national structured e-invoicing portal start operating in a live environment from 1 July 2028.) The bill applies one start date to everyone in scope: there is no phasing by size or turnover.
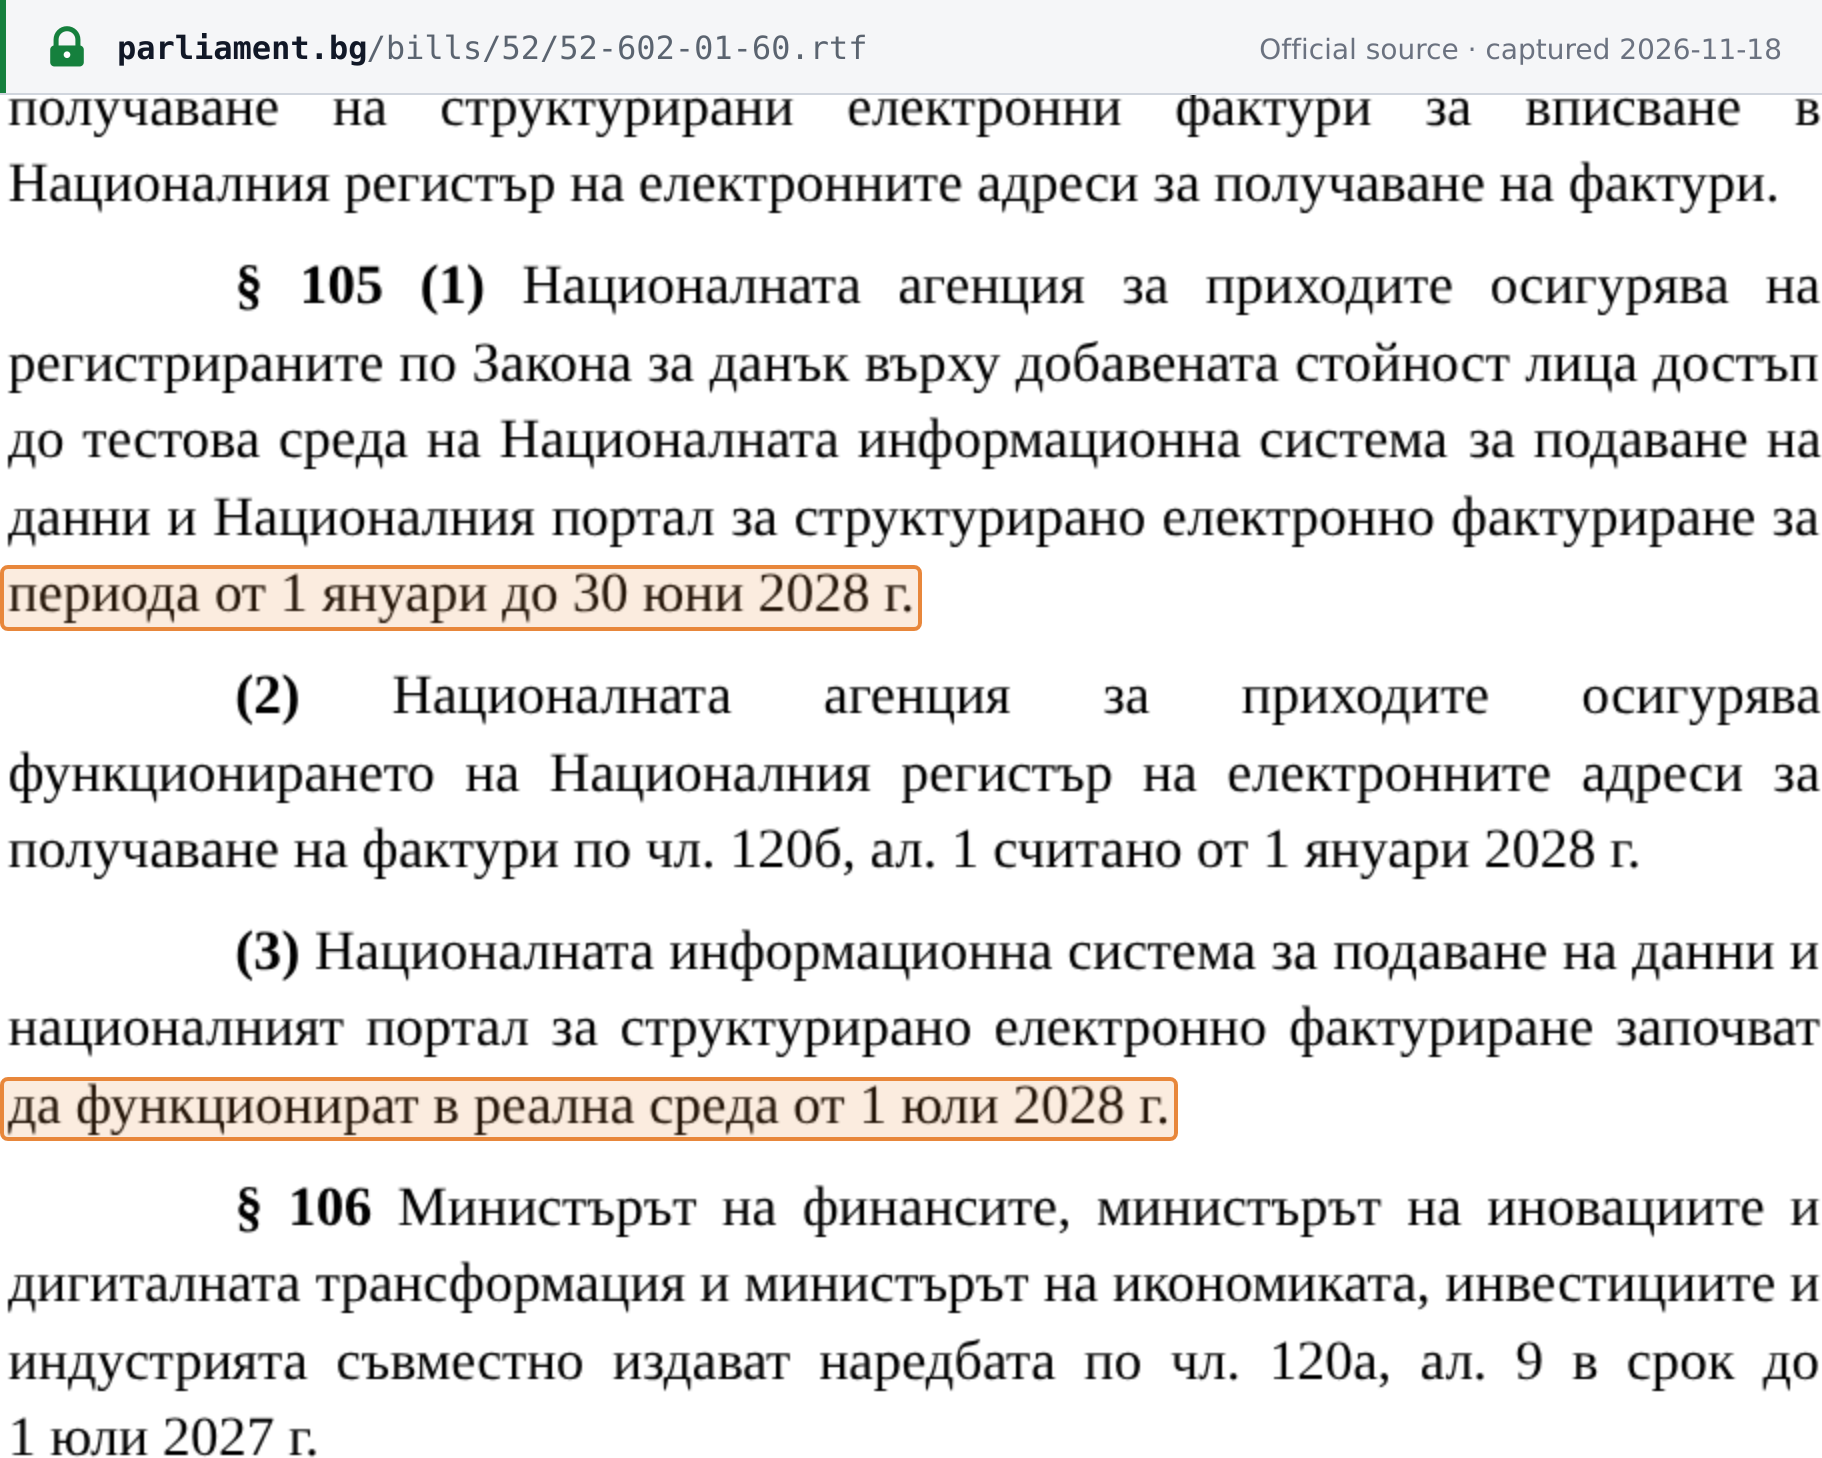 Source snapshot captured 2026-11-18 from bill 52-602-01-60 (transitional and final provisions) — original
Registration threshold (proposed). The bill deletes the EUR 51,130 figure from art. 96 and sets a national threshold for annual domestic turnover of EUR 60,000 from 1 January 2027, EUR 70,000 from 1 January 2028 and EUR 75,000 from 1 January 2029 (new art. 96(7)). The consultation draft had proposed a single EUR 75,000 threshold from 1 January 2027. See the Bulgaria VAT guide for the threshold in force.
Transitional rules (proposed, bill §§ 102–105). The VAT return, VIES declaration and ledgers for June 2028 are filed under the old rules. Where the chargeable event falls on or before 30 June 2028 but the invoice is issued after 1 July 2028, a structured e-invoice must be issued. An advance received before 1 July 2028 for a supply chargeable after that date is invoiced with a structured e-invoice for the full taxable amount, and the earlier invoice is cancelled. Persons VAT-registered at 1 January 2028 must declare their e-invoice receiving address to the NRA by 30 June 2028; the NRA gives test-environment access from 1 January to 30 June 2028. (Bill 52-602-01-60, transitional and final provisions, checked 2026-11-18)
Postponements
None of enacted law. No e-invoicing date was ever enacted in Bulgaria. The bill moves the proposed start from the consultation draft's 1 January 2028 to 1 July 2028, and the issuer penalty from 1 July 2028 to 1 January 2029; both earlier dates were proposals only. Some secondary sources describe a phased roll-out by company size. That phasing belongs to SAF-T (Standard Audit File for Tax), a separate obligation already in law and phased in from 2026 to 2030 (see the SAF-T explainer and the Bulgaria VAT guide). The e-invoicing bill has a single date.
Legal basis
In force
- VAT Act (ЗДДС), consolidated to State Gazette 115/2025. The provisions that govern
e-invoices today:
- art. 113(12): an e-invoice is deemed issued on the date the supplier, or a person acting for it, makes it available so that the customer can receive it;
- art. 114(9): e-invoices only with the recipient's written or tacit consent (in force since 1 January 2013, State Gazette 94/2012);
- art. 114(6), (10) and (11): authenticity of origin, integrity of content and legibility, by business controls with a reliable audit trail; a qualified electronic signature and EDI are example technologies;
- art. 121–122: retention and online access for the NRA. [1]
- Public Procurement Act (ЗОП), as last amended by State Gazette 71/2026 (7 August 2026).
- art. 115a: contracting authorities must accept and process e-invoices whose content meets ЗДДС art. 114(1) and which conform to the European standard approved by Commission Implementing Decision (EU) 2017/1870, "или еквивалентен стандарт, с който е въведен" (or an equivalent standard by which it is introduced);
- § 2 item 10a (supplementary provisions): an "electronic invoice" is one "issued, provided and received in a structured electronic format that allows its automatic electronic processing";
- art. 36(3) and art. 39a: the central e-procurement platform (CAIS EOP), maintained by the Public Procurement Agency (art. 36(3)), and the uses it is mandatory or optional for (art. 39a). [3]
- State Gazette 86 of 18 October 2018, the act amending the Public Procurement Act that transposed Directive 2014/55/EU. Its § 65 inserted art. 115a, and its § 141 brought § 65 into force on 1 November 2019. The gazette date is not the start of the obligation. [2]
- State Gazette 107/2020, which inserted art. 39a(4)–(5) of the Public Procurement Act from 1 January 2021.
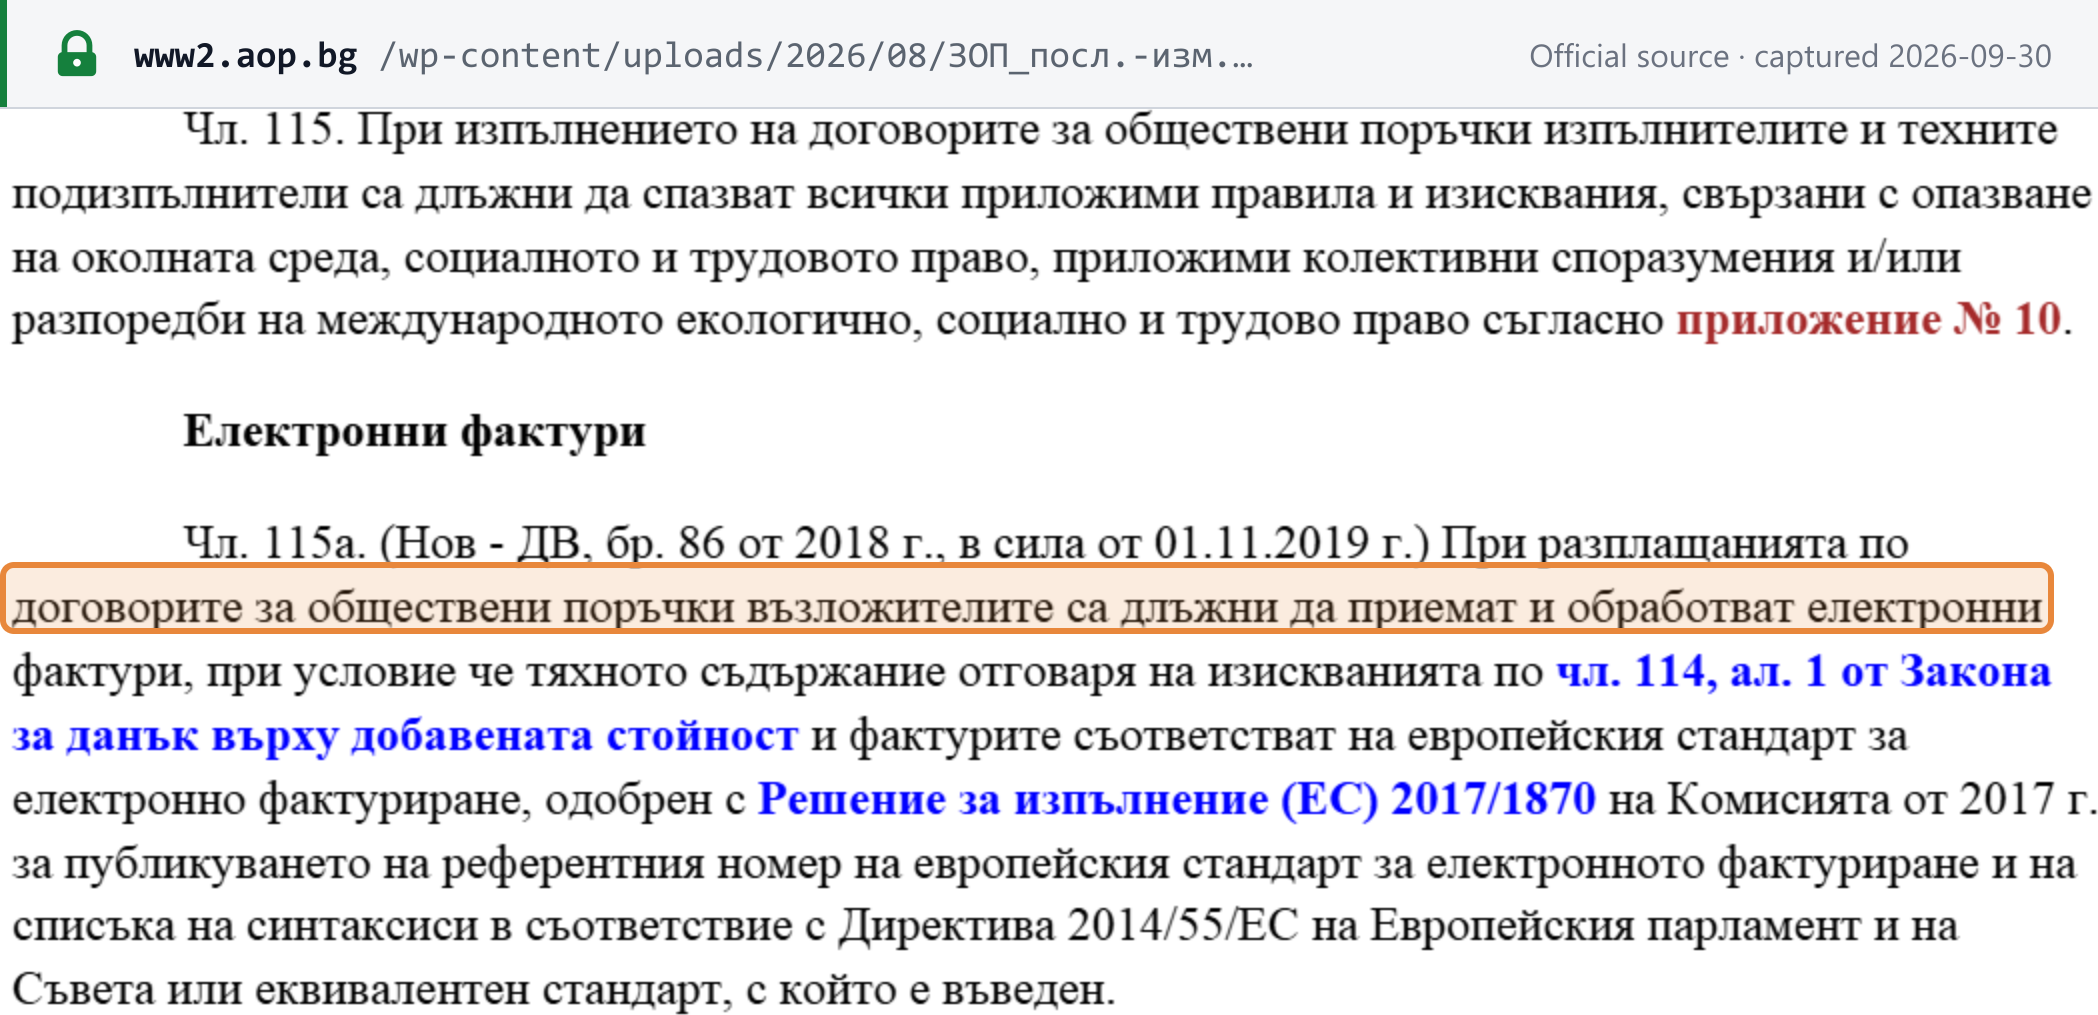 Source snapshot captured 2026-09-30 from the consolidated text published by the Public Procurement Agency (Ciela export of 07.08.2026) — original
Proposed
- Bill amending the VAT Act (ЗИД на ЗДДС), National Assembly reference 52-602-01-60, submitted 5 November 2026, with its explanatory memorandum (мотиви). As submitted, it would insert art. 113(16)–(22) (the e-invoicing duty, its exceptions and an offline procedure for outages), a new chapter 11a (arts 120a–120d: structured e-invoice, national register of receiving addresses, national portal, exchange and digital reporting), art. 182a and art. 192b, tie the input-VAT credit to an issued art. 120a document (art. 71, item 1), repeal art. 124(1)–(6), and rewrite art. 125 on the VAT return. [6]
- Legal base claimed. The memorandum presents the reform as aligned with Directive 2014/55/EU and as preparing for the EU's VAT in the Digital Age package, Directive (EU) 2025/516. It explains the move away from clearance by the ViDA rule that Member States may offer a tax authority platform or portal but may not make it the mandatory, sole channel.
- Technical ordinance. The Ministers of Finance, of Innovation and Digital Transformation, and of Economy, Investment and Industry would jointly issue an ordinance on technical standards, exchange and digital reporting of e-invoices (art. 120a(9)) by 1 July 2027 (bill § 106). It would set the technical requirements under BDS EN 16931, the data elements sent to the NRA, API security and interoperability requirements, the portal's rules, and the conditions for accrediting service providers (art. 120a(10)).
- Earlier draft. The Ministry of Finance consultation draft of 23 September 2026 (consultation 12733, closed 23 October 2026) proposed a centralised clearance model from 1 January 2028. It is superseded by the bill. (strategy.bg — consultation 12733)
- ViDA. The bill does not transpose the EU cross-border e-invoicing and digital reporting regime due from 1 July 2030. The memorandum cites the risk of a centralised system conflicting with "новите правила за дигитално отчитане (DRR)" (the new digital reporting rules) that apply from 1 July 2030. See the ViDA explainer.
Retention (in force). Every taxable person keeps the tax documents it issues and receives "до 5 години след изтичане на давностния срок" (until 5 years after the limitation period expires) for the public liability they evidence, in their original form (ЗДДС art. 121(1)). For documents stored electronically, the data that ensure authenticity and integrity are kept for the same period (art. 121(2)). Where storage gives online access, the NRA must have electronic online access (art. 122). The total number of years depends on the limitation period under the Tax and Social Insurance Procedure Code, which this page does not restate. The bill's reporting rules do not lift the taxpayer's own art. 121 duty.
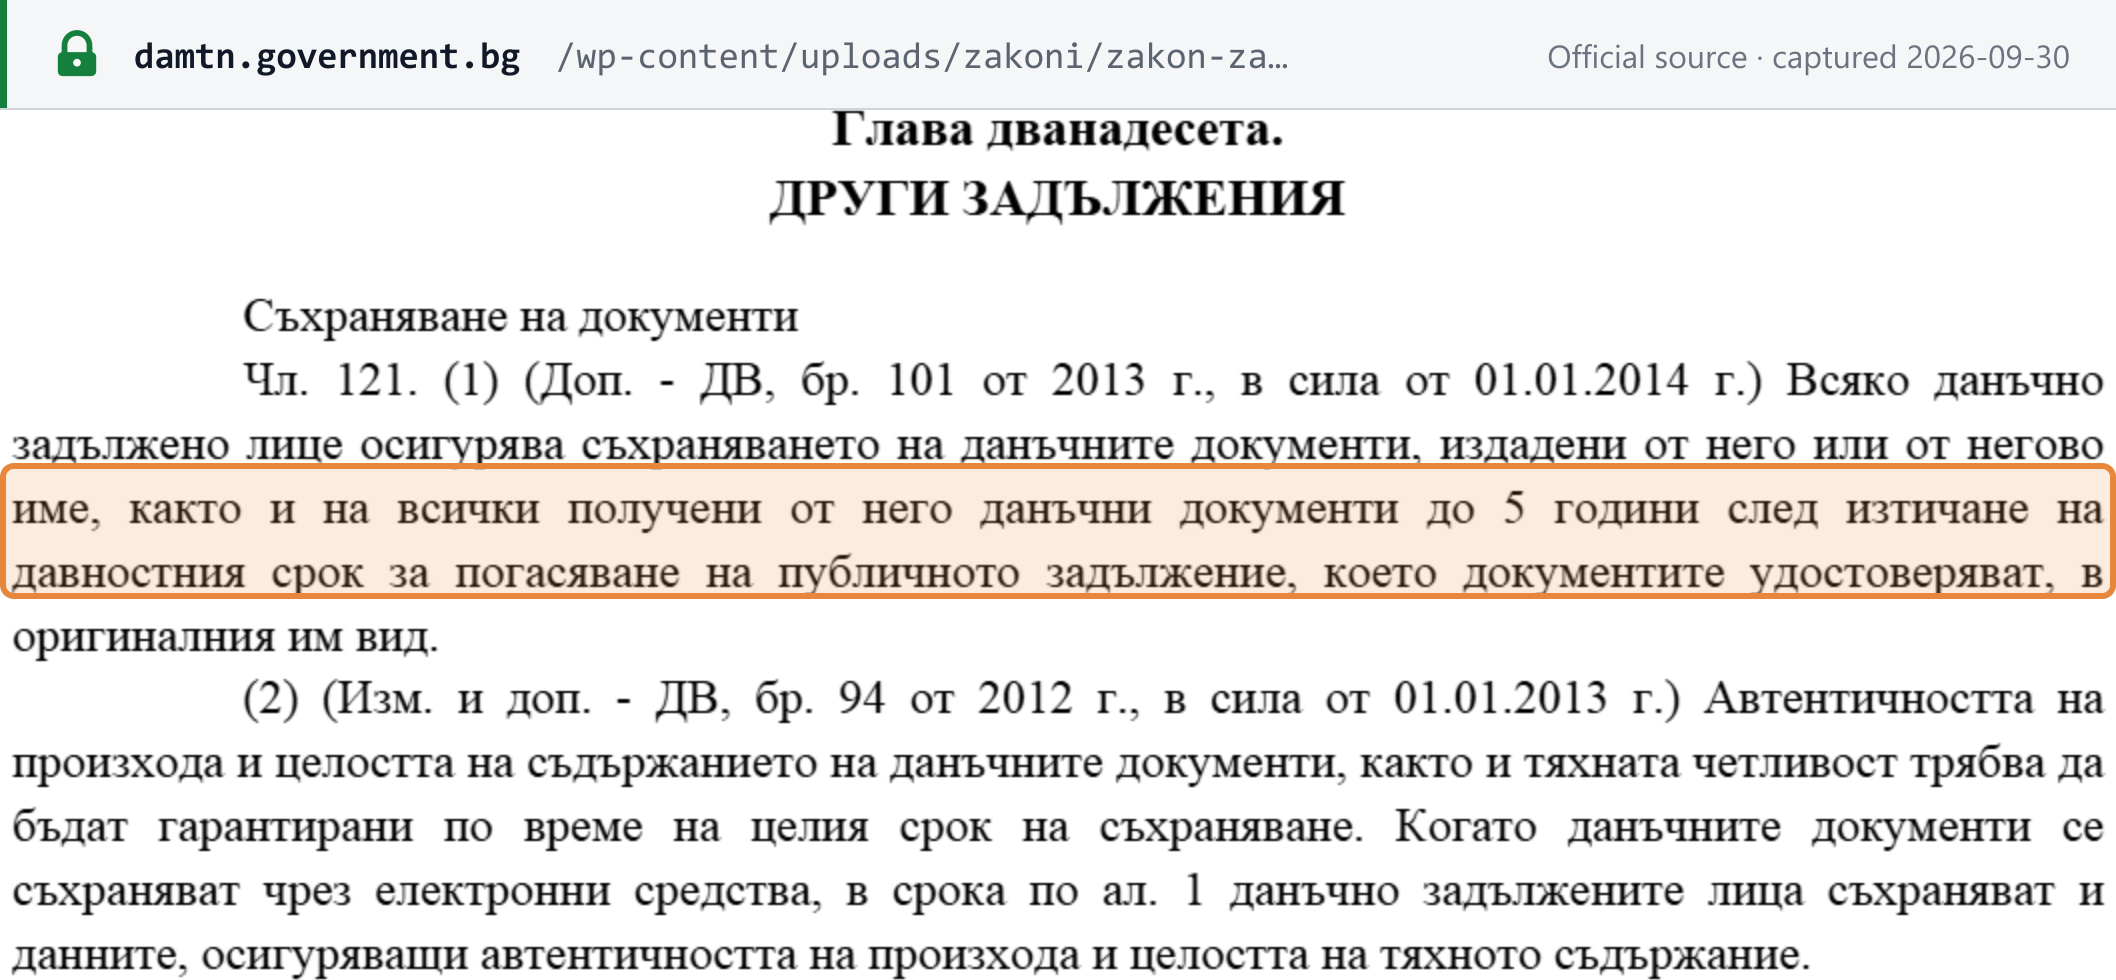 Source snapshot captured 2026-09-30 from the consolidated text (Ciela export of 09.07.2026) — original
Scope
B2B
Today: no mandate. A business may send e-invoices, including a PDF by email, only if the buyer accepts them in writing or tacitly (ЗДДС art. 114(9)). Paper invoices remain valid.
Proposed from 1 July 2028. Bill art. 113(16) says a supplier that is registered under the VAT Act and established in Bulgaria "издава задължително" (must issue) a tax document under art. 120a, a structured e-invoice, when all of these hold:
- the supply has its place of supply in Bulgaria, including advance payments for such a supply;
- the recipient is established in Bulgaria; and
- the recipient is a taxable person, a non-taxable legal person, or the state or a state or local body.
For intra-Community supplies, supplies as intermediary in a triangular transaction and services under art. 21(2) with a place of supply in another Member State, and their advances, the supplier may issue a document other than a structured e-invoice. Issuing a structured e-invoice "не е обвързано с изискване за приемане от страна на получателя" (is not conditional on acceptance by the recipient) (art. 120a(6)), so consent under art. 114(9) would survive only for invoices outside the mandate. (Bill 52-602-01-60, §§ 33 and 40, checked 2026-11-18)
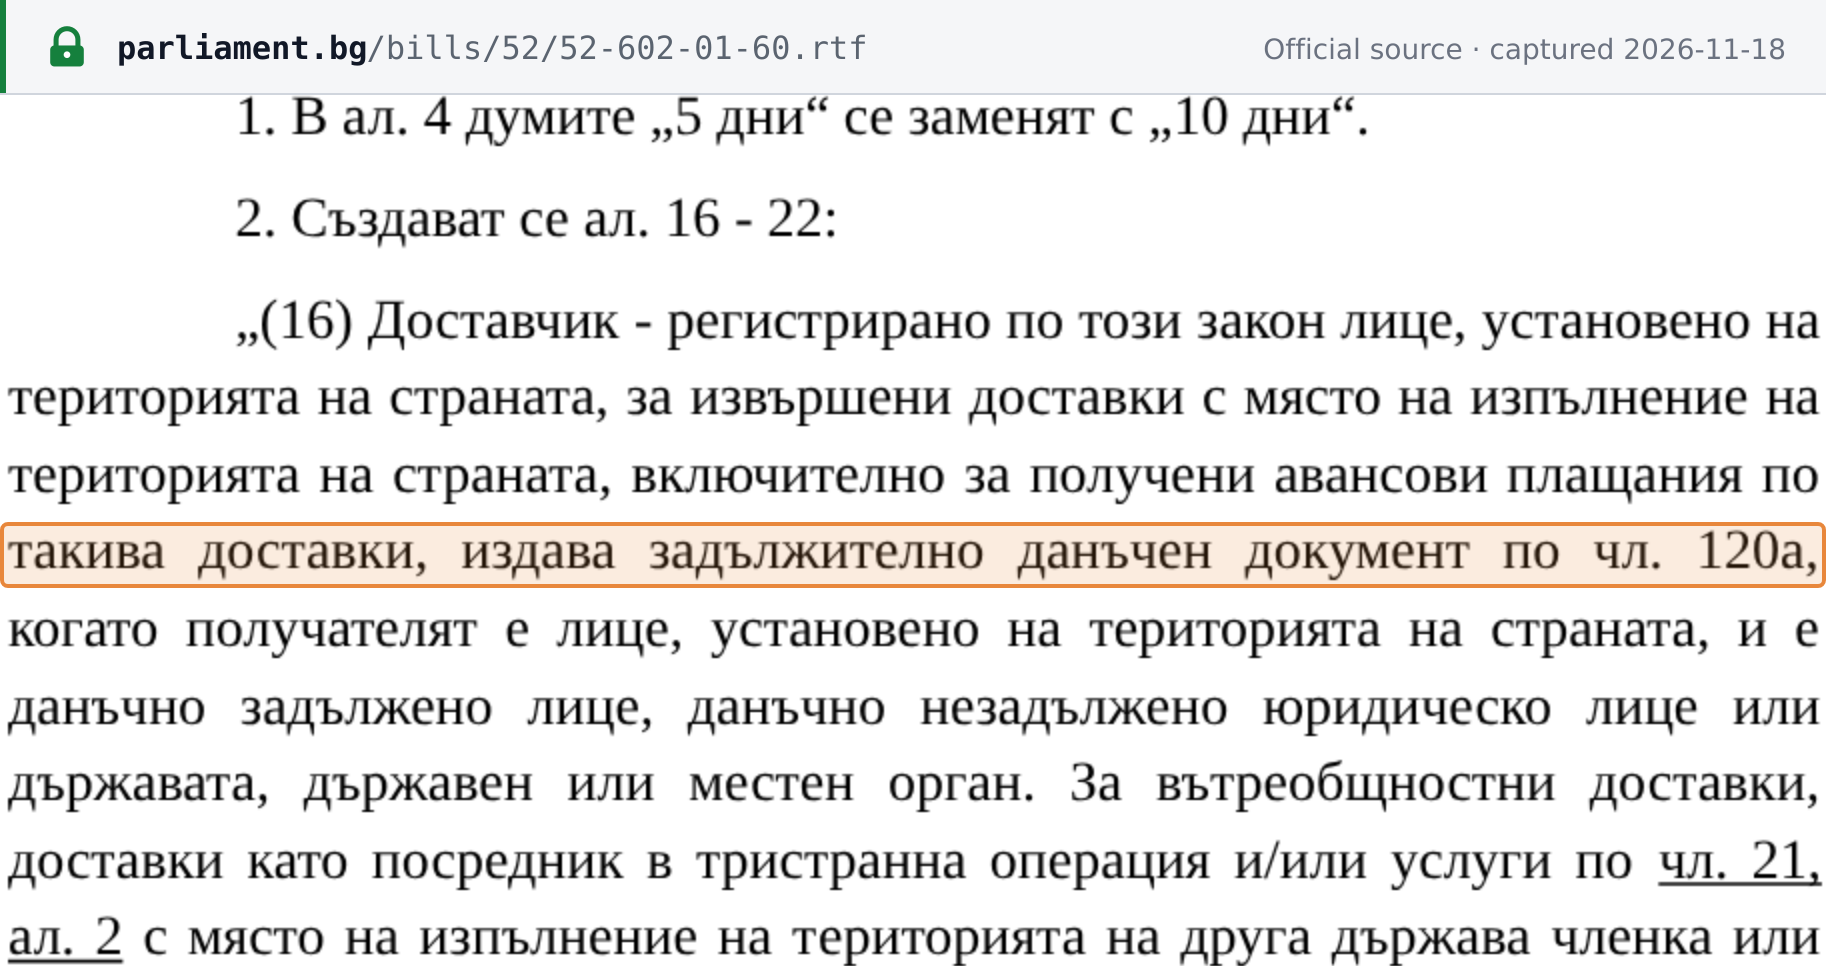 Source snapshot captured 2026-11-18 from bill 52-602-01-60 (proposed art. 113(16)) — original
B2G
Today. Under ЗОП art. 115a, in payments under public procurement contracts, contracting authorities "са длъжни да приемат и обработват електронни фактури" (must accept and process electronic invoices) that meet ЗДДС art. 114(1) and EN 16931. The duty has applied to all contracting authorities since 1 November 2019. The text sets no value threshold and does not split central from sub-central authorities. It imposes no duty on suppliers to send e-invoices: a supplier may still invoice on paper or by PDF. Because ЗОП § 2 item 10a defines an e-invoice as a structured, machine-processable one, a PDF or scan does not trigger the authority's acceptance duty. [3]
Proposed from 1 July 2028. Supplies to the state or to a state or local body fall inside bill art. 113(16), so established VAT-registered suppliers would have to issue structured e-invoices to public bodies. Bill art. 113(17) extends the same duty to suppliers that are established in Bulgaria but not VAT-registered, for their supplies to public bodies.
B2C
Today: no mandate. Proposed: the bill's recipient test covers taxable persons, non-taxable legal persons and public bodies only, so supplies to individuals stay outside the mandate.
Non-established businesses
Today: e-invoicing is voluntary for everyone. Proposed: a supplier that is VAT-registered in Bulgaria but not established there issues an ordinary art. 112 document and does not apply art. 113(16) (bill art. 113(18)). A separate change would make a VAT-registered Bulgarian customer liable for the VAT on such supplies (bill § 18, new art. 82(2)(4), from 1 July 2028); see the Bulgaria VAT guide.
Unregistered established businesses
Proposed: in scope only for supplies to public bodies (bill art. 113(17)).
Exempt supplies and simplified invoices
Unknown. The bill attaches the duty to supplies with a place of supply in Bulgaria and does not say, in the e-invoicing provisions reviewed here, whether exempt supplies or simplified invoices of up to EUR 100 (ЗДДС art. 114(7)) are carved out (checked 2026-11-18).
Format & network
CTC model
Today: none. No invoice passes through a tax-authority system before or after it reaches the buyer. The VAT Act has no submission, clearance or real-time reporting duty for invoices.
Proposed: decentralised exchange with real-time reporting. Under bill art. 120a, a structured e-invoice contains the information the VAT Act requires and meets the European e-invoicing standard and the list of syntaxes under Directive 2014/55/EU (art. 120a(1)). It is issued, transmitted and received in structured form within a standardised network for the secure exchange of e-invoices (art. 120a(2)), reached through an access point from an authorised service and software provider (art. 120a(3)). It may be issued from the taxpayer's own software, a provider's software, or the NRA's national portal (art. 120a(4)), and it "се считат за издадени в момента на предаването им към получателя" (is deemed issued at the moment it is transmitted to the recipient) (art. 120a(5)). Corrections to the taxable amount must be made by a structured electronic note (art. 120a(7)). There is no NRA compliance code: the consultation draft's clearance step was dropped.
Reporting to the NRA (art. 120d, Cyrillic 120д). The data set by the ordinance go to the NRA "в момента на издаване" (at the moment of issue) of each structured e-invoice or note, for each supply. For self-billing, the supplier sends them no later than 5 days after the invoice is issued. Invoices issued or received through the national portal are reported automatically.
National register of receiving addresses (art. 120b, Cyrillic 120б). Every VAT-registered person established in Bulgaria declares, within 7 days of VAT registration, an access-point address for receiving structured e-invoices: the national portal, an access point in the standardised network (for users of a provider's software), or an electronic data interchange address (for own software). The supplier must send the invoice "точно и единствено" (exactly and only) to the address in the register and check that address before sending; the recipient receives and processes structured e-invoices only through the address it declared.
System outages (art. 113(20)–(21)). Where the software, the exchange network or the NRA portal is technically unavailable, structured e-invoices are prepared offline in structured form; paper or unstructured (PDF) invoices are not allowed. They are then transmitted within 7 working days of the official notice that an outage of the national system has been fixed, or within 1 working day of the taxpayer's own systems being restored. (Bill 52-602-01-60, §§ 33 and 40, checked 2026-11-18)
Format
- B2G today: EN 16931, as approved by Commission Implementing Decision (EU) 2017/1870, which covers the standard and its list of syntaxes (UBL 2.1 and UN/CEFACT CII), "or an equivalent standard" (ЗОП art. 115a). The European Commission's Bulgaria eInvoicing page says Bulgaria applies no national CIUS and no extensions beyond EN 16931. (European Commission — eInvoicing in Bulgaria, checked 2026-09-30)
- Proposed from 1 July 2028: EN 16931 under Directive 2014/55/EU. The exchange network must support the semantic standard "чрез осигуряване на пълен автоматичен обмен във форматите XML UBL 2.1 и CII" (by ensuring full automatic exchange in the XML UBL 2.1 and CII formats) (art. 120a(11), item 4). The data elements reported to the NRA and the detailed technical rules are to be set by the ordinance (art. 120a(10)).
- Extra mandatory field (proposed, art. 114(1), item 16): the numbers of the bank accounts, payment accounts or other identifiers that unambiguously identify the supplier's accounts where payment is received or expected.
- Invoice particulars and currency (in force): every invoice, electronic or paper, carries the art. 114(1) particulars. Since euro adoption on 1 January 2026, an invoice in another currency must still show the taxable amount and the VAT in euro (art. 114(5)); see Invoice requirements in the country guide, including the 10-digit numbering rule.
Network
Not Peppol-based today; Peppol not named in the bill. Neither the Public Procurement Act nor the European Commission's Bulgaria eInvoicing page refers to Peppol (checked 2026-09-30), and the bill does not name it (checked 2026-11-18). There is no Bulgarian Peppol participant-identifier rule and no Peppol Authority named in these sources.
Proposed network requirements (art. 120a(11)). The standardised secure exchange network approved by the ordinance must comply with Directive 2014/55/EU; use a technology architecture "базирана на CEF eDelivery, с прилагане на профила на транспортния протокол AS4" (based on CEF eDelivery, applying the AS4 transport protocol profile); follow a decentralised governance model with accredited providers, a "четириъгълен или петъгълен пазарен модел" (four-corner or five-corner market model); and support EN 16931 in UBL 2.1 and CII.
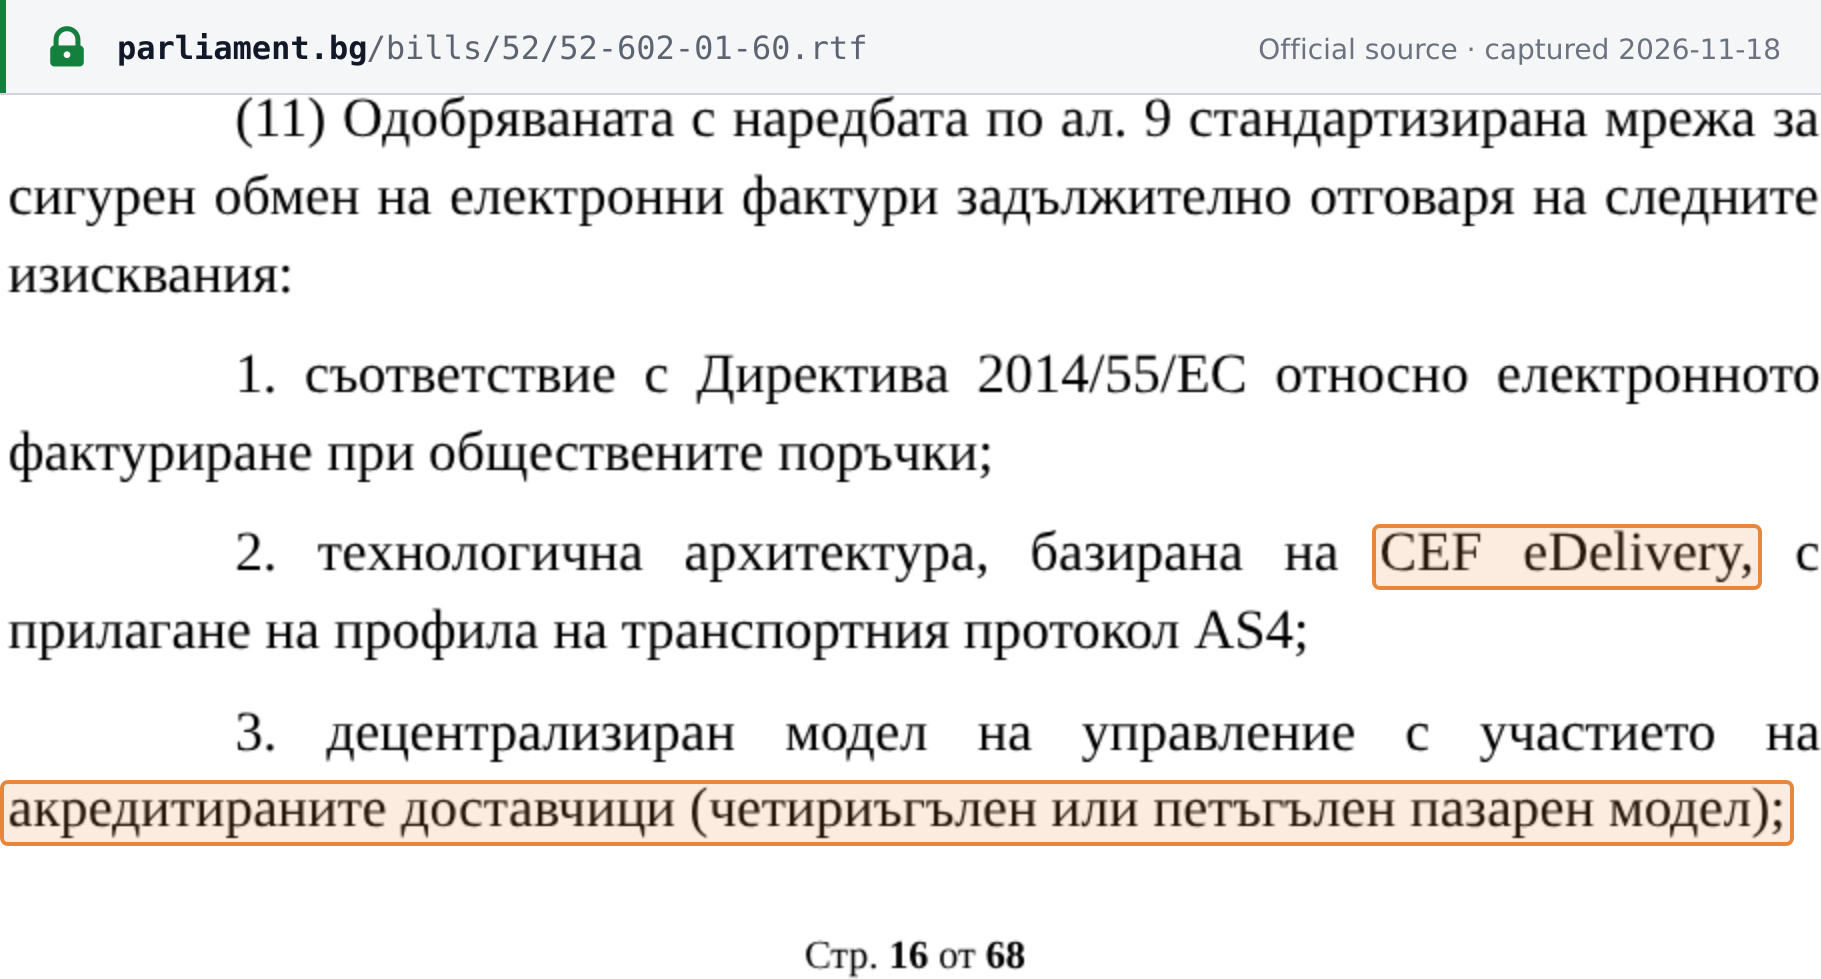 Source snapshot captured 2026-11-18 from bill 52-602-01-60 (proposed art. 120a(11)) — original
B2G channel today: CAIS EOP. The Централизирана автоматизирана информационна система „Електронни обществени поръчки" (ЦАИС ЕОП, CAIS EOP) at app.eop.bg is the central e-procurement platform, maintained by the Public Procurement Agency (Агенция по обществените поръчки, АОП) under ЗОП art. 36(3). Since 1 January 2021 it is mandatory for tendering steps (art. 39a(4)). For invoices it is optional: authorities and economic operators "може да използват" (may use) the platform for "подаване и приемане на електронни фактури" (submitting and receiving electronic invoices) (art. 39a(5)). A supplier may therefore send an EN 16931 invoice through CAIS EOP or directly to the authority's own system. There is no single mandatory B2G hub.
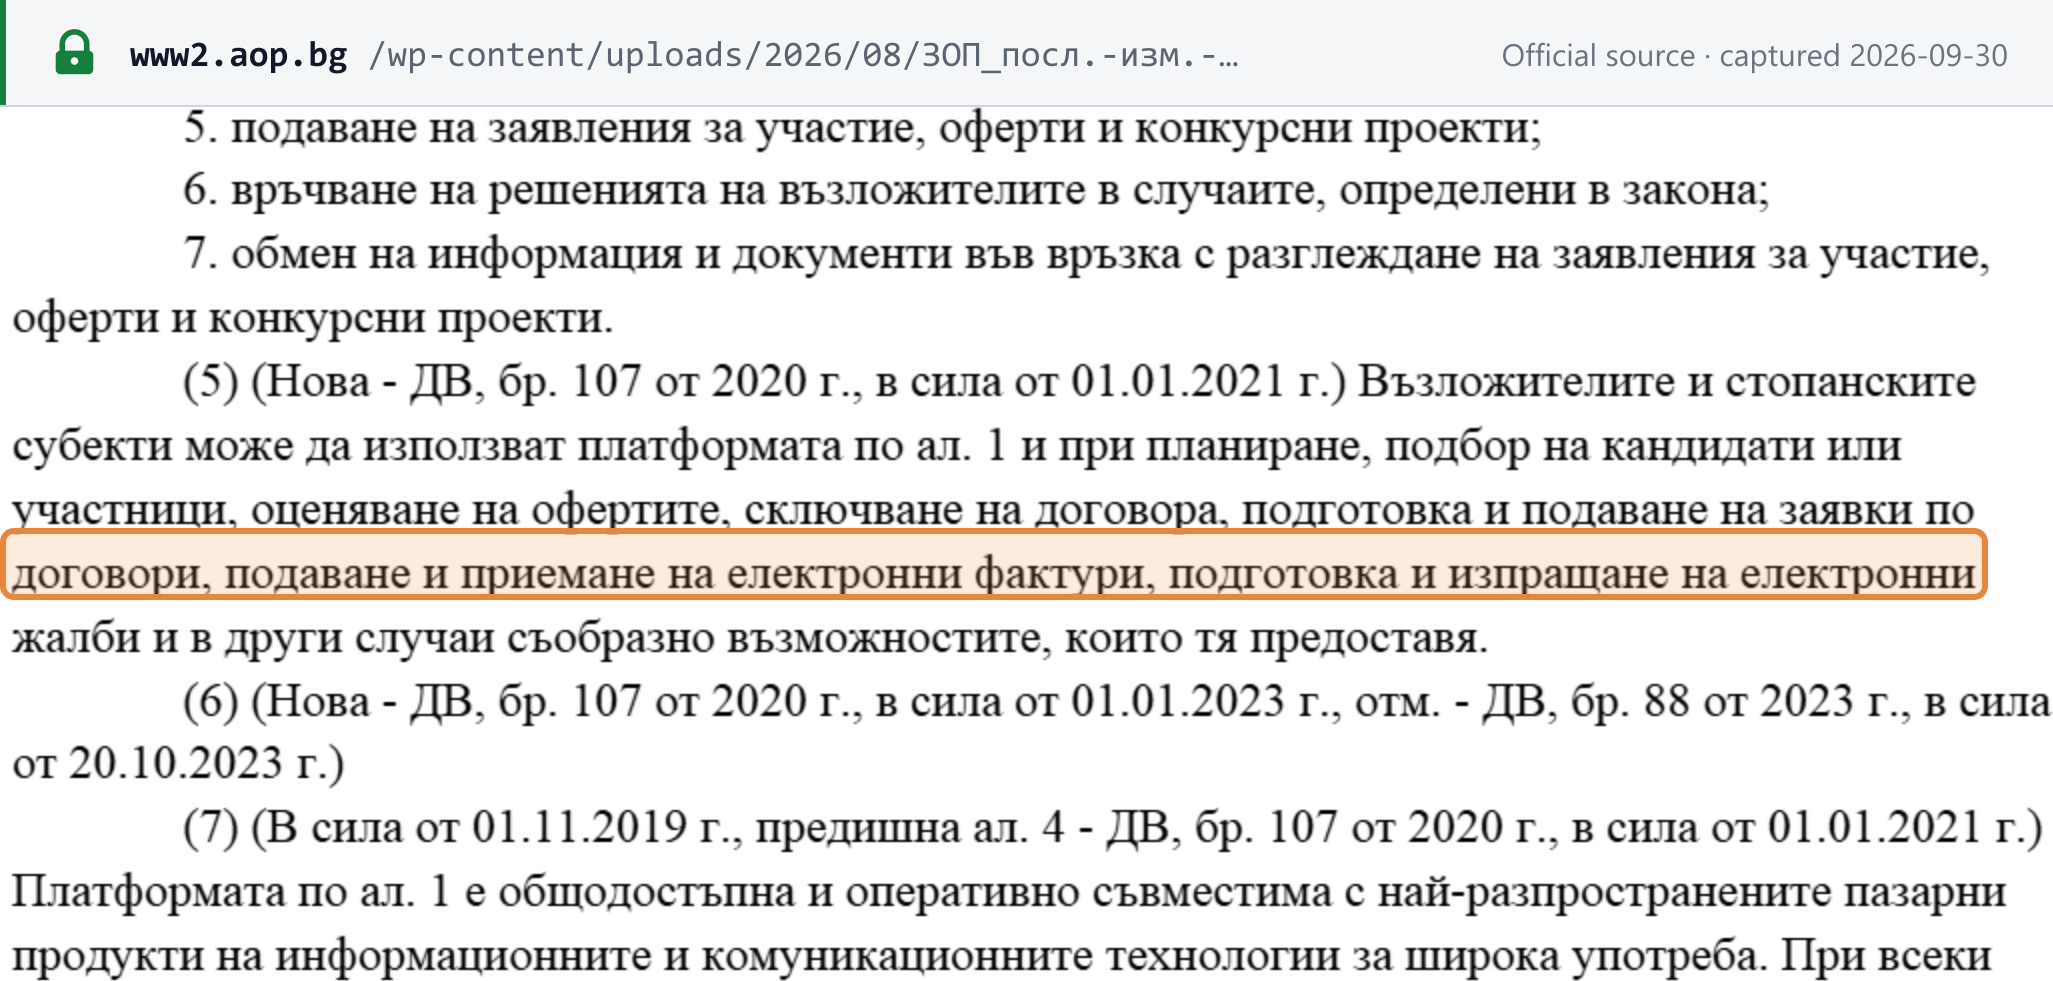 Source snapshot captured 2026-09-30 from the consolidated text published by the Public Procurement Agency (Ciela export of 07.08.2026) — original
Integrity mechanics
Today: no mandatory e-signature, QR code or hash. Each taxable person ensures authenticity of origin, integrity of content and legibility "по избран от него начин" (by a method of its choice) (ЗДДС art. 114(6)), through any business control that creates a reliable audit trail between invoice and supply (art. 114(10)). A qualified electronic signature under Regulation (EU) 910/2014 and EDI are examples, not requirements (art. 114(11)).
Proposed: the bill drops the consultation draft's NRA compliance code and sets no QR-code, hash or cryptographic-stamp requirement in its text (checked 2026-11-18). Security requirements for APIs and the certification of own software are left to the ordinance (art. 120a(10), item 3).
E-reporting alongside e-invoicing
Today: none tied to invoices. Monthly VAT returns with purchase and sales ledgers are filed by the 14th, and SAF-T is a separate monthly file phased in from 2026 (see the SAF-T explainer).
Proposed from 1 July 2028:
- invoice data are reported to the NRA at the moment each structured e-invoice is issued (art. 120d, above);
- the NRA gives every VAT-registered person a pre-generated draft VAT return for each period, built from structured e-invoices issued by and to it and from customs declarations (bill art. 125(3), (16)–(17)), available electronically no later than the 2nd of the following month (art. 125(18)). The person adds supplies for which no structured e-invoice is required (art. 125(19));
- the monthly purchase and sales ledgers (дневник за покупките, дневник за продажбите) are abolished: bill § 43 repeals art. 124(1)–(6).
Onboarding / how to comply
B2G today
- Check what the authority accepts. Every contracting authority must accept EN 16931 e-invoices (UBL or CII) under ЗОП art. 115a. Ask whether it takes them through CAIS EOP or through its own system.
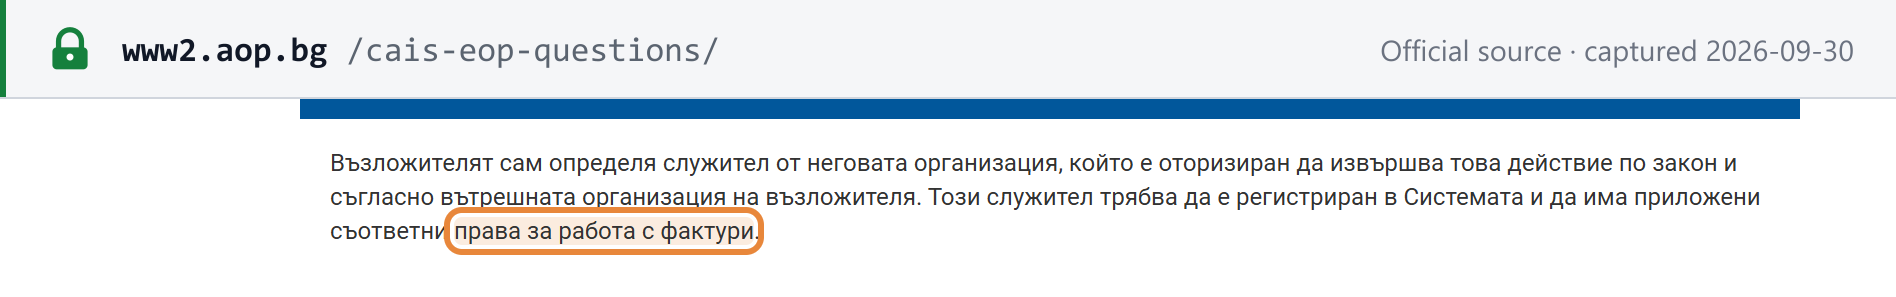
- CAIS EOP. Register at app.eop.bg. The Public Procurement Agency's CAIS EOP FAQ confirms the system has invoice functions: on the authority's side, an employee registered in the system with "права за работа с фактури" (rights to work with invoices) approves the invoice. The FAQ adds that the system has no pro-forma invoice function.
- Test environment. The Public Procurement Agency links a CAIS EOP test instance at app-test.eop.bg.
 Source snapshot captured 2026-09-30 — original
Unknown: whether CAIS EOP registration needs a qualified electronic signature, which invoice formats it accepts on upload, and whether it validates against EN 16931. The Public Procurement Agency's user manuals were not located (checked 2026-09-30).
Preparing for the proposed July 2028 mandate
- Declare a receiving address: persons VAT-registered at 1 January 2028 would have to declare their e-invoice receiving address to the NRA by 30 June 2028 (bill § 104); later registrants within 7 days of registration (art. 120b(2)). The declaration is made electronically with a qualified electronic signature or an electronic identification means (art. 120b(4)).
- Choose a connection mode (proposed, art. 120b(3)): the NRA national portal (no specialised software); an access point in the standardised exchange network through a provider's software; or an electronic data interchange address for own software.
- Accreditation of providers: the national register would list accredited providers of structured e-invoicing services and certified own software (art. 120b(1)); the accreditation conditions are left to the ordinance (art. 120a(10), item 5). No list exists yet.
- Testing: the NRA would give VAT-registered persons access to a test environment of the national data-submission system and portal from 1 January to 30 June 2028 (bill § 105(1)).
- Cost (government estimate): the memorandum puts the cost of the national e-invoicing system at EUR 20 million, according to NRA data, to be planned in the 2027 central budget. (Bill 52-602-01-60, memorandum, checked 2026-11-18)
- Follow the bill: track the second-reading report and vote on the National Assembly bill page.
Penalties
In force
There is no penalty specific to e-invoicing. The general invoice penalties of the VAT Act apply:
| Breach | Penalty | Provision |
|---|---|---|
| Tax document not issued or not reflected, leading to understated VAT or an overstated refund | The uncharged tax, not less than BGN 1,000 | ЗДДС art. 182(1) |
| The same document issued or reflected in the following period | 25% of the uncharged tax, not less than BGN 250 | ЗДДС art. 182(2) |
The BGN amounts are still the statutory figures. The Euro Introduction Act reads them as euro at the fixed rate of 1.95583 (art. 11(2)). [1]
Proposed (bill 52-602-01-60, not law)
| Breach | Proposed penalty | Bill provision | Proposed start |
|---|---|---|---|
| Registered person does not issue a structured e-invoice (art. 120a) | The uncharged tax, not less than EUR 750 (individuals who are not traders) or EUR 1,500 (legal persons and sole traders) | art. 182a (§ 84) | 1 January 2029 |
| Producer or distributor of structured e-invoicing software whose code, through technical gaps or errors, blocks automatic transmission of data to the national information system | EUR 5,000–10,000 (individuals who are not traders); EUR 25,000–50,000 (legal persons and sole traders) | art. 192b(1) (§ 97) | 1 July 2028 |
| Repeat of the software breach | EUR 10,000–20,000 / EUR 50,000–100,000 | art. 192b(2) | 1 July 2028 |
| Buyer: no issued structured e-invoice for the supply | No input-VAT credit: the right to deduct requires holding an issued tax document under art. 120a | art. 71, item 1 (§ 7) | 1 July 2028 |
The bill would also change the general art. 182 floors (bill § 83): not less than EUR 500 for individuals who are not traders and EUR 1,000 for legal persons and sole traders (art. 182(1)), and 25% but not less than EUR 125 / EUR 250 for late issue or reflection (art. 182(2)), against BGN 1,000 and BGN 250 for all today.
Input VAT (proposed). Bill art. 71, item 1 makes the right to deduct depend on the person holding "издаден данъчен документ по чл. 120а" (an issued tax document under art. 120a). A deduction not claimed in the period the right arose can be claimed in one of the next 12 tax periods (new art. 72(2)). The exposure falls on the buyer, which is why Bulgarian buyers would have a direct interest in their suppliers' compliance. (Bill 52-602-01-60, §§ 7–8, 83–84, 97, checked 2026-11-18)
Enforcement posture. The bill does not describe the gap between 1 July 2028 and 1 January 2029 as a grace period. It defers only the art. 182a fine; the obligation, the input-VAT rule and the software penalty would apply from 1 July 2028.
Frequently asked questions
Is e-invoicing mandatory in Bulgaria yet?
No, as at 18 November 2026. There is no B2B or B2C mandate: an e-invoice may be used only if the buyer accepts it by written or tacit consent (VAT Act art. 114(9)). A government bill submitted to the National Assembly on 5 November 2026 proposes mandatory structured e-invoices from 1 July 2028, after a test period from 1 January 2028. It passed first reading on 12 November 2026 but is not law until adopted at second reading and promulgated.
Do we have to send e-invoices to Bulgarian public bodies?
Not today. Since 1 November 2019 contracting authorities must accept and process EN 16931 e-invoices (Public Procurement Act art. 115a), but suppliers are not obliged to send them. Under the bill, from 1 July 2028 suppliers established in Bulgaria would have to issue structured e-invoices to public bodies, even if they are not VAT-registered (proposed art. 113(16)–(17)).
Is a PDF sent by email an e-invoice in Bulgaria?
For VAT purposes today, yes, if the buyer consents (VAT Act art. 114(9)). For the public-procurement acceptance duty, no: the Public Procurement Act defines an e-invoice as one in a structured format that allows automatic processing. Under the bill, from 1 July 2028 only a structured EN 16931 e-invoice sent to the buyer's registered address would satisfy the mandate, and even during an outage paper or PDF invoices would not be allowed.
We are a foreign company registered for VAT in Bulgaria. Would the 2028 mandate apply to us?
Not as proposed. A VAT-registered supplier that is not established in Bulgaria would keep issuing ordinary invoices and would not apply the structured e-invoice rule (proposed art. 113(18)). The bill is not law and may change in the National Assembly.
As a buyer, what happens if my supplier does not issue a structured e-invoice after 2028?
Under the bill, from 1 July 2028 the right to deduct input VAT would require an issued structured e-invoice (proposed art. 71, item 1). The supplier would face a fine equal to the uncharged tax, at least EUR 750 or EUR 1,500, from 1 January 2029 (proposed art. 182a). Both are proposals.
Do we need Peppol or a certified provider?
The bill does not name Peppol. It proposes a decentralised four- or five-corner network built on CEF eDelivery with the AS4 profile, reached through accredited service providers, and also lets businesses use their own software or the National Revenue Agency's national portal (proposed arts 120a and 120b). Provider accreditation rules are left to a ministerial ordinance due by 1 July 2027. For public bodies today, the optional CAIS EOP platform or the authority's own system is used.
Is the 2028 mandate phased by company size?
No. The bill has one start date, 1 July 2028, for everyone in scope. The size-based phasing some sources describe belongs to SAF-T, a separate reporting obligation already in law and phased in from 2026 to 2030.
Which XML syntax will Bulgaria use, UBL or CII?
Both, under the bill. The proposed exchange network must support EN 16931 with full automatic exchange in XML UBL 2.1 and CII (proposed art. 120a(11)). The data reported to the National Revenue Agency and the detailed technical rules are left to a ministerial ordinance due by 1 July 2027. For public bodies today, EN 16931 in either syntax on the EU list is accepted, and Bulgaria applies no national CIUS.
Recent changes
- 2026-11-12 — Proposed, not law. The National Assembly adopted bill 52-602-01-60 amending the VAT Act at first reading (122 for, 49 against, 18 abstentions); proposals for second reading were due by 18 November 2026. The bill still needs a second reading and promulgation in the State Gazette. (National Assembly) — see event · issue
- 2026-11-05 — Proposed, not law. The government submitted bill 52-602-01-60 amending the VAT Act to the National Assembly: structured e-invoices over a decentralised network, with the national data-submission system and portal live from 1 July 2028 after a test period from 1 January 2028, and a national VAT registration threshold of EUR 60,000 from 2027, EUR 70,000 from 2028 and EUR 75,000 from 2029 (updated from the 23 September 2026 consultation draft: clearance from 1 January 2028). (National Assembly) — see event · issue
- 2021-01-01 — CAIS EOP became mandatory for public tendering; submitting and receiving e-invoices through it is optional (Public Procurement Act art. 39a(4)–(5)). (Public Procurement Agency)
- 2019-11-01 — Contracting authorities became obliged to accept and process EN 16931 e-invoices (Public Procurement Act art. 115a, State Gazette 86/2018). (State Gazette)
Related resources
- Bulgaria VAT guide — rates, registration, invoice requirements, SAF-T and filing
- Bulgaria tax identification numbers — the EIK/BULSTAT and VAT number formats
- How to verify a Bulgarian VAT number
- Bulgaria tax-change chronology — every tracked Bulgarian change, dated and sourced
- E-invoicing status and networks worldwide — Bulgaria's row in global context
- ViDA — VAT in the Digital Age — the EU framework behind the 2030 cross-border stage
- SAF-T explainer — the separate audit-file obligation
- Peppol network explainer — for comparison; neither Bulgaria's current rules nor the bill name Peppol
- Other national mandates for comparison: Poland (KSeF), Romania (RO e-Factura)
Important websites
- Bill 52-602-01-60 (National Assembly) — the bill page, readings and committee reports; bill text with explanatory memorandum (RTF)
- Public consultation 12733 (strategy.bg) — the superseded consultation draft of 23 September 2026 and public comments
- CAIS EOP — the Public Procurement Agency's e-procurement platform, with optional e-invoice exchange; test environment
- CAIS EOP FAQ — Public Procurement Agency questions and answers, including invoicing
- Public Procurement Agency — national legislation — consolidated Public Procurement Act
- NRA e-services portal — the NRA's existing e-services portal
- State Gazette — promulgation of any adopted law
- National structured e-invoicing portal, receiving-address register and test environment — none published (proposed for 2028)