E-invoicing in China: the fully digitalised e-fapiao
Overview
Mainland China runs its e-invoicing through the fully digitalised electronic invoice, in Chinese 全面数字化的电子发票, shortened to 数电发票 ("e-fapiao" in English-language practice; the pilot-era name 全电发票 still circulates). The State Taxation Administration (国家税务总局, STA) runs it. This page covers mainland China only: Hong Kong, Macao and Taiwan are separate tax jurisdictions (see the Taiwan e-invoicing guide).
STA Announcement No. 11 of 2024, item 1, defines it: "数电发票是《中华人民共和国发票管理办法》中"电子发票"的一种,是将发票的票面要素全面数字化、号码全国统一赋予、开票额度智能授予、信息通过税务数字账户等方式在征纳主体之间自动流转的新型发票。数电发票与纸质发票具有同等法律效力。" (The fully digitalised e-invoice is a kind of "electronic invoice" under the Fapiao Administrative Measures: its face elements are fully digitised, its number is assigned nationally, its invoicing quota is granted automatically, and its data flows between the tax authority and taxpayers through tax digital accounts. It has the same legal effect as a paper invoice.) Item 2 adds that it is a single copy that exists only in digital form ("数电发票为单一联次,以数字化形态存在"). [1]
 Source snapshot captured 2026-11-11 — original
Legal basis in one line. VAT Law Article 34 (in force 1 January 2026), the Fapiao Administrative Measures as revised in 2023 (Article 3), their Implementing Rules as amended by STA Order No. 56 (in force 1 March 2024), STA Announcement No. 11 of 2024 (nationwide rollout from 1 December 2024), and the sector announcements for rail and air tickets. Full list under Legal basis.
| China (mainland) | |
|---|---|
| System | Fully digitalised e-invoice (数电发票), issued on the STA's national unified e-invoice service platform (全国统一的电子发票服务平台) inside the e-tax bureau |
| Authority | State Taxation Administration; rail and air announcements co-signed with China State Railway Group (Anns. 8/2024 and 22/2026), the Ministry of Finance (Anns. 8/2024 and 9/2024) and the Civil Aviation Administration of China (Ann. 9/2024) |
| Status (as at 2026-11-15) | Formally rolled out nationwide since 1 December 2024, after pilots from 1 December 2021. Paper fapiao remain lawful in general, but refined-oil retail stations had to issue every fuel sale as a real-time e-fapiao through the Leqi platform by 1 November 2026 (STA Ann. 11/2026) |
| B2B and B2C | One system for both: every payee issues a fapiao to the payer (Fapiao Measures Art. 18). No special VAT fapiao to natural persons or for VAT-exempt supplies |
| B2G | No separate B2G system or rule published by the STA |
| Non-residents | The Chinese buyer withholds the VAT and deducts on a tax payment certificate (完税凭证) (VAT Law Art. 15) |
| Model | Centralised issuance: the platform assigns the number, applies the monthly quota and delivers to the buyer's tax digital account |
| Format | XML data message, plus PDF and OFD; files downloaded from the tax digital account carry a digital signature |
| Network | STA platform via the e-tax bureau; Leqi (乐企) direct connection, used by qualifying enterprises themselves (乐企自用) or by others through a connected platform (乐企联用), the route refined-oil stations without their own connection must use (Ann. 11/2026); not Peppol |
| Integrity | 20-digit nationally assigned number; digital signature; real-name verification of the issuer; QR code on rail and air e-tickets |
| Upcoming | Railway e-ticket rules (STA/China Railway Ann. 22/2026), announced 4 November 2026, take effect 1 December 2026 |
For VAT rates, registration and the general fapiao content rules, see the China VAT guide.
Mandate status & timeline
Status (as at 2026-11-15): formally rolled out nationwide since 1 December 2024; paper fapiao remain lawful in general, with a refined-oil retail exception from 1 November 2026 (below). The preamble of STA Announcement No. 11 of 2024 (dated 12 November 2024) recites the pilot and the decision: "自2021年12月1日广东省、上海市和内蒙古自治区试点推行全面数字化电子发票(以下简称数电发票)以来,试点地区已逐步扩大至全国。……国家税务总局决定,在全国正式推广应用数电发票" (Since fully digitalised e-invoices were piloted in Guangdong, Shanghai and Inner Mongolia from 1 December 2021, the pilot area has gradually expanded to the whole country. … The STA has decided to formally roll out fully digitalised e-invoices nationwide.). Item 12: "本公告自2024年12月1日起施行。" (This announcement takes effect on 1 December 2024.) [1]
 Source snapshot captured 2026-11-14 — original
| Phase | Scope | What happens | Date | Instrument | State (2026-11-15) |
|---|---|---|---|---|---|
| Policy target | Nationwide | National e-invoice platform to be built in 2021; e-invoicing in "all fields, all links, all elements" basically achieved by 2025 | Set March 2021 | CPC General Office and State Council General Office, Opinions on Further Deepening Tax Collection and Administration Reform, item (五) | Target year passed |
| Pilot | Guangdong, Shanghai, Inner Mongolia, then gradually the whole country | Fully digitalised e-invoices piloted | From 1 Dec 2021 | Recited in the preamble of STA Ann. 11/2024 | Closed into the nationwide phase |
| Implementing Rules | All fapiao users | E-invoice definition, platform, data security, third-party services, real-name issuance | 1 Mar 2024 | STA Order No. 56 | In force |
| Rail passenger tickets | Railway carriers | The railway e-ticket becomes a fully digitalised e-invoice; paper reimbursement vouchers bookable only for travel dates up to 30 Sep 2025 | 1 Nov 2024 | STA/MOF/China Railway Ann. 8/2024 | In force; paper window closed |
| Nationwide rollout | All taxpayers | Fully digitalised e-invoices formally rolled out nationwide | 1 Dec 2024 | STA Ann. 11/2024 | In force |
| Air passenger itineraries | PRC-registered airlines and air-ticket sales agents, domestic passenger transport | The electronic itinerary (电子行程单) becomes a fully digitalised e-invoice; paper itineraries bookable for flight dates up to 30 Sep 2025 | 1 Dec 2024 | STA/MOF/CAAC Ann. 9/2024 | In force; paper window closed |
| Accounting data standard | All accounting units | National rollout of the MOF e-voucher accounting data standard (XML e-fapiao; OFD with embedded XBRL for air and rail tickets) | From 9 May 2025 (date of issue) | 财会〔2025〕9号 | In force |
| Refined-oil retail: "交易即开票" | Refined-oil retail stations (incl. floating fuel barges and diesel-only rural outlets) | Every fuel sale invoiced in full as a fully digitalised e-invoice through the STA's Leqi platform immediately after the transaction, via Leqi self-use or Leqi joint-use | Ann. dated 8 Jun 2026, in force on publication; stations to comply by 1 Nov 2026 (transition period ended 1 Nov 2026) | STA Ann. 11/2026 | In force |
| Railway channel rules | Passengers, ticket buyers, proxies; railway carriers; third-party internet platforms | Rail e-invoices only through 12306 or a station "scan-to-invoice slip"; third-party platforms and individuals barred from issuing, delivering or downloading them; new optional format | 1 Dec 2026 | STA/China Railway Ann. 22/2026 | Announced 4 Nov 2026; takes effect on 1 Dec 2026 |
Latest announced phase. STA and China State Railway Group Announcement No. 22 of 2026, dated 4 November 2026, takes effect on 1 December 2026 ("本公告自2026年12月1日起施行"). It is covered under Railway e-tickets. [8]
 Source snapshot captured 2026-11-11 — original
Postponements. None: no STA, MOF or State Council instrument has moved any of these dates.
Refined-oil retail. STA Announcement No. 11 of 2026 (8 June 2026) defines "交易即开票" as a station "完成销售成品油交易后,按照交易数据通过税务部门乐企平台即时向购买方全量开具全面数字化电子发票" (after completing a fuel sale, immediately issuing a fully digitalised e-invoice to the buyer for the full transaction data through the tax authority's Leqi platform). Item 8: "成品油零售加油站应当于2026年11月1日前实现“交易即开票”" (stations must achieve it by 1 November 2026). Stations meeting the Leqi self-use conditions, with provincial confirmation, connect their own systems (乐企自用); all others connect to a Leqi joint-use platform (乐企联用) (item 2). The STA's interpretation calls the period from publication to 1 November 2026 a transition period (过渡期). [16] [17]
More phases. Apart from refined-oil retail, no date to abolish paper fapiao has been announced. The VAT Law and the Fapiao Measures say only that the State "积极推广使用电子发票" (actively promotes electronic invoices), an intent rather than a deadline. The MOF says it will extend its accounting data standard to further voucher types "成熟一个、推进一个" (one at a time, as each matures). [3] [10]
Legal basis
| Instrument | What it does | Dated | In force | Official text |
|---|---|---|---|---|
| VAT Law of the PRC (中华人民共和国增值税法), Art. 34 | VAT fapiao "包括纸质发票和电子发票。电子发票与纸质发票具有同等法律效力。国家积极推广使用电子发票。" (include paper and electronic invoices; electronic invoices have the same legal effect as paper ones; the State actively promotes electronic invoices). Art. 15: foreign sellers' VAT withheld by the buyer | Adopted 25 Dec 2024 | 1 Jan 2026 (Art. 38) | NPC |
| VAT Law Implementing Regulations (增值税法实施条例), State Council Order No. 826, Arts. 11, 37 | Deduction vouchers (incl. tax payment certificates); no special VAT fapiao to natural persons or for exempt supplies | 2025 | 1 Jan 2026 | State Council |
| Fapiao Administrative Measures (中华人民共和国发票管理办法), Arts. 3, 18, 22, 28, 33-39 | Art. 3: "发票包括纸质发票和电子发票。电子发票与纸质发票具有同等法律效力。" Art. 22: anyone developing an e-invoice system or providing e-invoice services must follow STA rules. Penalties in Chapter 6 | 1993; third revision by State Council Order No. 764 (2023) | Revised text in force | STA database |
| Implementing Rules of the Fapiao Measures (发票管理办法实施细则), as amended by STA Order No. 56 | Art. 3: e-invoice issued and received "以数据电文形式" (as a data message); "任何单位和个人不得拒收" (no unit or individual may refuse it). Art. 4: e-invoice service platform. Art. 30: invoices in Chinese. Art. 32: third-party e-invoice data services | Adopted 29 Dec 2023 | 1 Mar 2024 | STA database |
| STA Announcement No. 11 of 2024 (国家税务总局公告2024年第11号) | Nationwide rollout: definition, categories, face content, 20-digit number, free platform, monthly quota, real-name verification, red-letter corrections, delivery, use confirmation. Attachment 1: specimen styles | 12 Nov 2024 | 1 Dec 2024 | STA database · State Council mirror |
| STA interpretation of Ann. 11/2024 (18 questions) | Formats (XML, PDF, OFD), digital signature, quota mechanics, special-business invoices, voiding by red-letter invoice | 12 Nov 2024 | Guidance | STA database |
| STA/MOF/China Railway Announcement No. 8 of 2024 | Railway e-ticket as a fully digitalised e-invoice | 29 Sep 2024 | 1 Nov 2024 | STA database |
| STA/MOF/CAAC Announcement No. 9 of 2024 | Air passenger e-itinerary as a fully digitalised e-invoice | 6 Nov 2024 | 1 Dec 2024 | STA database |
| STA Announcement No. 11 of 2026 (国家税务总局公告2026年第11号) (+ STA interpretation) | "交易即开票" for refined-oil retail: real-time e-fapiao for every sale through the Leqi platform; Leqi self-use or joint-use; sanctions | 8 Jun 2026 | On publication; compliance by 1 Nov 2026 | STA Jiangsu bureau copy · interpretation |
| STA/China Railway Announcement No. 22 of 2026 (+ STA interpretation) | Railway e-invoice channels; third-party platforms barred; new optional format | 4 Nov 2026 | 1 Dec 2026 | STA database · interpretation |
| 财会〔2025〕9号 — MOF and others, Notice on promoting the e-voucher accounting data standard | Accounting data standard for XML e-fapiao and XBRL-in-OFD air and rail tickets | 9 May 2025 | From issue | STA database copy |
| 财会〔2020〕6号 — MOF and National Archives Administration, Notice on booking and archiving electronic accounting vouchers | E-invoices as accounting vouchers; printouts must be kept with the electronic original | 23 Mar 2020 | In force | State Council |
Technical standards. The STA's interpretation says the system works "通过制发电子发票数据规范、出台电子发票国家标准" (by issuing e-invoice data specifications and a national e-invoice standard). The interpretation names neither the data specifications nor the national standard. On the accounting side, the MOF promotes a national e-voucher accounting data standard (电子凭证会计数据标准) under 财会〔2025〕9号; units outside the pilot may adopt it where conditions allow ("对于未参与试点的单位,在具备条件的基础上,可充分借鉴试点先行经验,稳步推进"). [2] [10]
Scope
B2B and B2C. One system covers both. "收款方应当向付款方开具发票" (the payee must issue a fapiao to the payer), and in special cases the payer issues it to the payee (Fapiao Measures Art. 18); every unit and business individual that pays must obtain one (Art. 19). The 数电发票 is the electronic form of every fapiao category (Ann. 11/2024 item 2). Under Implementing Regulations Art. 37, a taxpayer must not issue a special VAT fapiao (增值税专用发票) where the buyer is a natural person or the supply is VAT-exempt; it issues an ordinary fapiao instead. Individuals see the e-invoices issued to them in the Individual Income Tax app (个人所得税APP) as well as in a tax digital account (Ann. 11/2024 item 11). [4] [12] [1]
B2G. Not applicable as a separate regime: the STA's e-invoicing announcements, the Fapiao Measures and the MOF accounting-standard notice publish no separate rule, channel or date for supplies to government bodies. Suppliers to government issue the same 数电发票. Do not confuse this with fiscal e-receipts (财政电子票据), which government bodies and public institutions issue for non-tax revenue; 财会〔2025〕9号 lists them as a separate voucher type. [10]
Non-established (foreign) businesses. VAT Law Art. 15: "境外单位和个人在境内发生应税交易,以购买方为扣缴义务人;按照国务院的规定委托境内代理人申报缴纳税款的除外。" (Where a foreign unit or individual makes a taxable transaction in China, the buyer is the withholding agent, unless a domestic agent is appointed under State Council rules.) The buyer's input-VAT deduction voucher is then a tax payment certificate (完税凭证), one of the deduction vouchers listed in Implementing Regulations Art. 11, rather than a fapiao. A foreign-invested enterprise registered in China is an ordinary taxpayer and uses the 数电发票 like any domestic company. [3] [12]
Imports and exports. Import VAT is collected by customs, and the deduction voucher is the customs import VAT special payment certificate (海关进口增值税专用缴款书), not a fapiao (Implementing Regulations Art. 11). On the export side, a buyer that wants to claim an export refund on a 数电发票 must first confirm its use in its tax digital account (Ann. 11/2024 item 10). [12] [1]
Simplified invoices. Not applicable: the VAT Law, its Implementing Regulations and the Fapiao Measures set no value threshold for a simplified invoice. The split is special VAT fapiao versus ordinary fapiao, by buyer and use (Implementing Regulations Art. 37). [12]
Format & network
CTC model: what the platform does to an invoice
Invoices are issued through the STA's national platform (or by systems connected to it), and the platform assigns the number, applies the quota and delivers the invoice to the buyer (see CTC e-invoicing models explained). The steps, from Ann. 11/2024 and the STA's interpretation: [1] [2]
- Platform. "税务机关建设全国统一的电子发票服务平台,提供免费的数电发票开票、用票服务。" (Tax authorities build a national unified e-invoice service platform providing free issuing and use services; item 5.) Provincial tax authorities may withhold the service from taxpayers who by rule do not file online, lack network access or carry major tax risk.
- Number. Each invoice gets a unique number from the system when it is generated (the "赋码制"); there are no pre-allocated number ranges. The number has 20 digits (item 4).
- Quota. The platform grants a total invoicing quota (发票总额度): "一个自然月内,纳税人发票开具总金额(不含增值税)的上限额度" (the cap on a taxpayer's total invoiced amount, excluding VAT, in one calendar month). It is set and adjusted by tax risk, credit rating and actual business (item 6).
- Identity. "数电发票的开具需要通过实人认证等方式进行身份验证。" (Issuing requires identity verification such as real-person authentication; item 7.)
- Delivery. Issued invoices are delivered automatically through the platform; the issuer may also send them by email, QR code or download. A downloaded or printed invoice shows its "下载次数" and "打印次数" (download and print counts) on its face (item 9).
- Use confirmation. A buyer that wants to deduct input VAT or refined-oil consumption tax, or to claim an export refund, must confirm the invoice's use in its tax digital account (item 10).
No special tax-control device is needed any more ("去介质"), and qualifying newly registered taxpayers can largely "开业即可开票" (issue invoices as soon as they open), the STA says. [2]
 Source snapshot captured 2026-11-14 — original
File formats and integrity
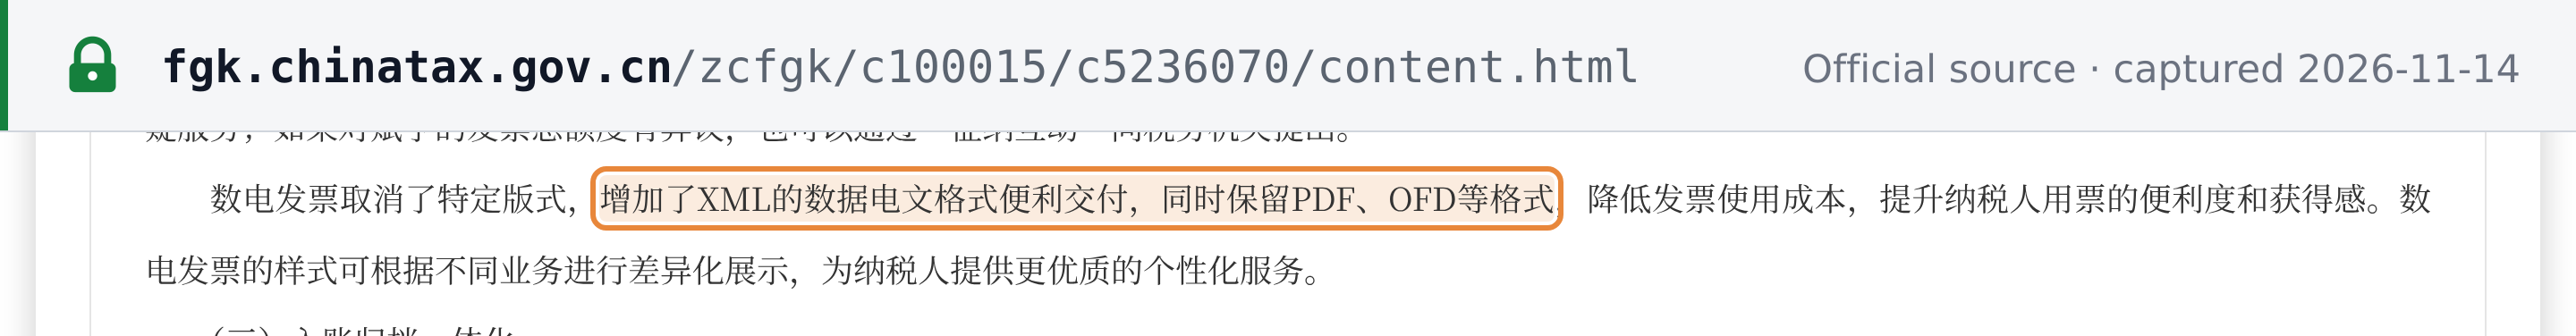
The 数电发票 has no fixed print layout. The STA's interpretation of Ann. 11/2024 (question 2): "数电发票取消了特定版式,增加了XML的数据电文格式便利交付,同时保留PDF、OFD等格式" (the fully digitalised e-invoice drops the specific layout, adds an XML data-message format for easier delivery, and keeps formats such as PDF and OFD). It adds: "通过税务数字账户下载的数电发票含有数字签名,无需加盖发票专用章即可入账归档。" (Invoices downloaded through the tax digital account carry a digital signature and can be booked and archived without an invoice seal.) OFD is China's national fixed-layout document format. [2]
 Source snapshot captured 2026-11-14 — original
On the accounting side, the MOF's e-voucher accounting data standard "支持XML格式的数电发票(含增值税专用发票、普通发票、航空运输电子客票行程单、铁路电子客票等)、内嵌XBRL的OFD格式数电发票(含航空运输电子客票行程单、铁路电子客票)" (supports XML-format e-fapiao, including special VAT invoices, ordinary invoices, air e-itineraries and rail e-tickets, and OFD-format e-fapiao with embedded XBRL for air e-itineraries and rail e-tickets) (财会〔2025〕9号, part 3). [10]
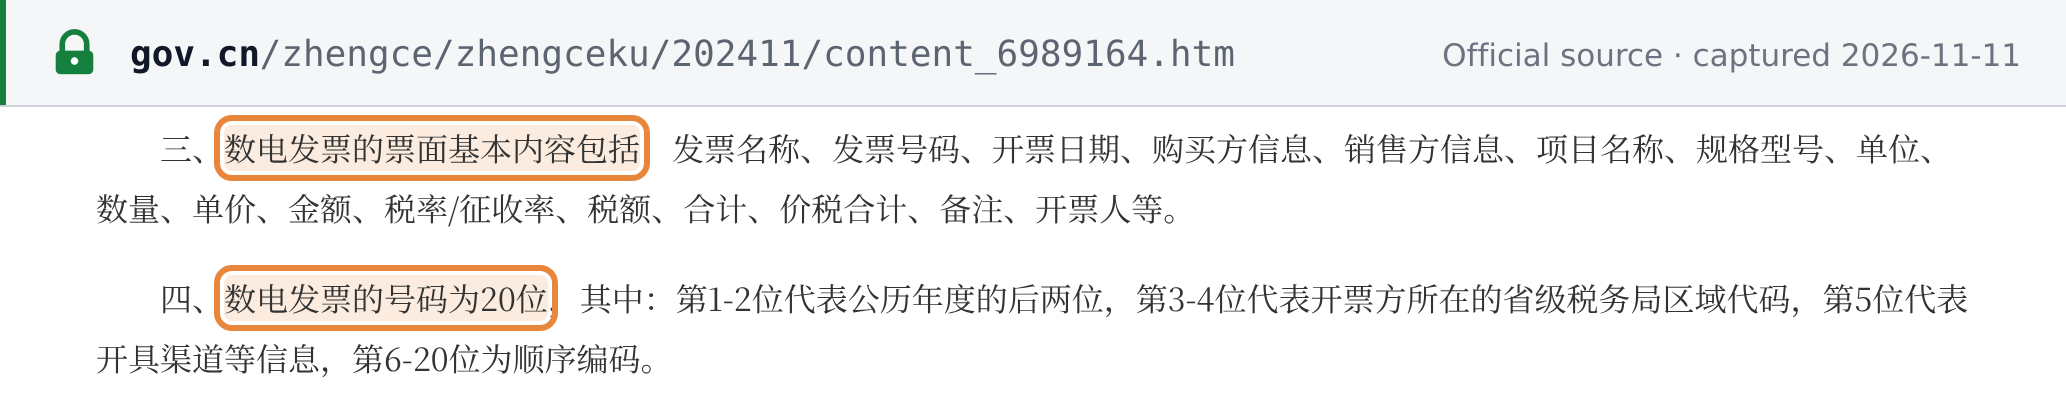
Number and face content. Ann. 11/2024 item 4: positions 1-2 are the last two digits of the year, 3-4 the code of the issuer's provincial tax bureau, 5 the issuing channel and other information, and 6-20 a sequence number. Item 3 lists the basic face content: invoice name, number, issue date, buyer and seller information, item name, specification or model, unit, quantity, unit price, amount, tax rate or levy rate, tax amount, total, total including tax, remarks and issuer. Invoices must be issued in Chinese (Implementing Rules Art. 30: "开具发票应当使用中文。"). [15] [5]
 Source snapshot captured 2026-11-11 — original
Categories. E-invoice (special VAT invoice), e-invoice (ordinary invoice), e-invoice (air transport e-ticket itinerary), e-invoice (railway e-ticket), e-invoice (unified motor-vehicle sales invoice), e-invoice (unified used-car sales invoice) and others (Ann. 11/2024 item 2). Business tags generate special-business invoices; the STA lists construction services, refined oil, scrap-product purchase, passenger and goods transport, sale and leasing of real estate, agricultural-product purchase, photovoltaic purchase, vehicle-and-vessel tax collected, margin taxation, tolls, medical services and rare earths, among others. Attachment 1 to Ann. 11/2024 carries the specimen styles (a .doc file of images). [1] [2]
Peppol and international standards. Not Peppol-based. The STA's announcements and interpretations publish no Peppol, UBL or CII profile; invoices flow through the STA's own platform and tax digital accounts.
E-reporting. Not applicable as a separate regime: the STA has published no transaction-reporting obligation apart from issuance, because the platform already holds the issued-invoice data. The buyer-side use confirmation (above) is the gate for input-VAT deduction.
Railway e-tickets
Since 1 November 2024 (Ann. 8/2024) the railway e-ticket is an e-fapiao: "电子发票(铁路电子客票)属于全面数字化的电子发票,基本内容包括:发票号码、开票日期、购买方信息、旅客身份证件信息、行程信息、票价、二维码等。" (The railway e-ticket e-invoice is a fully digitalised e-invoice; its basic content includes the invoice number, issue date, buyer information, passenger ID information, journey, fare and a QR code.) China Railway uploads the data to the tax authorities, which pass it to the buyer's tax digital account. Paper reimbursement vouchers could be booked only for travel dates up to 30 September 2025 (item 6). [6]
From 1 December 2026 (Ann. 22/2026, dated 4 November 2026, takes effect on 1 December 2026), passengers, ticket buyers and proxies obtain the railway e-invoice through railway 12306 (website and app), or ask at a station window or ticket machine for a "扫码开票单" (scan-to-invoice slip) and scan its QR code with the 12306 app (items 1-4). Carriers issue from the buyer name, unified social credit code and journey provided. Item 5: "任何涉铁路车票销售业务的第三方互联网平台和个人不得提供电子发票(铁路电子客票)的开具、交付、下载等服务。" (No third-party internet platform or individual involved in railway ticket sales may provide issuance, delivery or download services for railway e-ticket e-invoices.) Item 6 adds a new optional format; per the STA's interpretation it is the existing layout without the blue background ("取消了蓝色底色"), with all face elements unchanged. The announcement sets no specific sanction for platforms. [8] [9]
Air passenger e-itineraries
Since 1 December 2024 (Ann. 9/2024), PRC-registered public air-transport enterprises and air-ticket sales agents providing domestic passenger transport may issue the 电子发票(航空运输电子客票行程单) (air transport e-ticket itinerary e-invoice, "电子行程单"), which "属于全面数字化的电子发票" (is a fully digitalised e-invoice). Its content includes the passenger's ID, journey, fare, fuel surcharge, VAT amount, VAT rate, Civil Aviation Development Fund and a QR code. Passengers obtain it after all flight segments are completed, through the airline's or agent's website, app or phone line. Paper itineraries could be booked only for flight dates up to 30 September 2025. Itineraries can be verified on the national VAT invoice verification platform. [7]
Onboarding: how to comply
- Portal. Taxpayers log in to the national unified standardised e-tax bureau (全国统一规范电子税务局) and use the "发票业务" (invoice business) function of the integrated e-invoice service platform to issue, deliver, verify and confirm use, the STA says. No device purchase or number-range application is needed. The e-tax bureau is reached through each provincial tax bureau's site; start at the STA home page. [2]
- Credentials. The person issuing must complete real-name verification: "其经办人应当实名办税" (the operator must handle tax matters under their real name) (Implementing Rules Art. 34; Ann. 11/2024 item 7). [5]
- Quota disputes. A taxpayer that disagrees with its quota can raise it through the e-tax bureau's "征纳互动" (taxpayer-authority interaction) function, or apply to its tax office for an adjustment (interpretation, questions 2 and 4). [2]
- Connection modes.
- E-tax bureau (web and app): the default for most taxpayers.
- Leqi (乐企) direct connection: "乐企(Natural System),是指国家税务总局向符合条件的企业,通过税务系统与企业自有信息系统直连的方式,提供规则开放、标准统一的全面数字化的电子发票等涉税服务……的平台" (a platform through which the STA connects qualifying enterprises' own systems directly to the tax system). Access is requested in the e-tax bureau's Leqi module. As an example of the conditions, the STA Jiangsu bureau's guideline of 31 May 2023 required, for a self-use connection, a credit rating of A or B, prior-year revenue of RMB 50 million or more for the unit and its requested users, and at least 50,000 invoices issued and received in the preceding 12 months (or fewer but at least RMB 500 million invoiced). The connecting unit bears joint liability (连带责任) for serious consequences of its users' violations. These conditions come from a provincial text of 2023. [14]
- Third-party e-invoice service providers: anyone providing e-invoice services must follow STA rules (Fapiao Measures Art. 22); a provider of invoice-data query, download, storage or use services must meet the tax authority's data standards, sign an agreement with its client and "不得超越授权范围使用发票数据" (not use invoice data beyond the authorisation) (Implementing Rules Art. 32). [4] [5]
- Accreditation of providers. Not applicable in the certified-provider sense: the STA publishes no list of accredited e-invoice providers; providers are regulated through the articles above.
- Testing environment. For Leqi direct connection, "乐企平台测试中心为直连单位提供能力使用的仿真测试环境" (the Leqi platform test centre provides connecting units with a simulated test environment); units run joint testing there before going live (STA Jiangsu bureau guideline, 2023). [14]
Corrections: no voiding. An issued 数电发票 cannot be cancelled. The STA: "纳税人因开票有误等情形需要作废数电发票的,应当通过电子发票服务平台全额开具红字数电发票。" (A taxpayer that needs to void an e-invoice because of an issuing error must issue a full red-letter e-invoice through the platform.) Under Ann. 11/2024 item 8: [2] [1]
- if the buyer has not confirmed use or booked the invoice, the issuer starts the reversal and issues the red-letter invoice directly (purchase invoices for agricultural products, scrap and photovoltaic power always follow this route);
- if the buyer has confirmed use or booked it, either party may start the reversal, and the other must confirm a 红字发票信息确认单 (red-letter invoice information confirmation form); "《确认单》发起后72小时内未经确认的,自动作废" (a form not confirmed within 72 hours lapses automatically);
- a buyer that has already deducted the input VAT transfers out the VAT shown on the form in the current period.
Booking and archiving. "来源合法、真实的电子会计凭证与纸质会计凭证具有同等法律效力" (lawful, genuine electronic accounting vouchers have the same legal effect as paper ones), and compliant electronic accounting archives need not also be kept on paper. A unit that books a printout must also keep the electronic original (财会〔2020〕6号 items 2, 4 and 5). Issued-fapiao stubs are kept for 5 years (Fapiao Measures Art. 28). [11] [4]
Penalties
The Fapiao Administrative Measures, Chapter 6, set the general sanctions. STA Announcement No. 11 of 2026 adds sector rules for refined-oil retail: a Leqi direct-connection unit that charges stations improper fees or helps them evade tax supervision loses its Leqi access ("停止其乐企平台接入资格", item 7); a station that has not achieved "交易即开票" by 1 November 2026 is ordered to correct and dealt with under the Tax Collection and Administration Law and the Fapiao Measures (item 8); and evasion such as collecting payment through another entity's payment code is fined up to RMB 10,000 under Fapiao Measures Art. 33 (item 9). [16] [4]
| Breach | Sanction | Article |
|---|---|---|
| Failing to issue a fapiao when required, or not issuing it within the prescribed time, sequence and fields; using other vouchers in place of a fapiao, and similar breaches | Order to correct; fine up to RMB 10,000 ("可以处1万元以下的罚款"); confiscation of illegal gains | Art. 33 |
| False invoicing (虚开): issuing, receiving or arranging invoices that do not match the actual business (Art. 21), and illegal issuing on behalf of others | Confiscation; false amount up to RMB 10,000: fine up to RMB 50,000; above RMB 10,000: RMB 50,000 to 500,000; criminal liability where a crime | Art. 35 |
| Forging or altering fapiao; stealing, intercepting, tampering with, selling or leaking fapiao data | RMB 10,000 to 50,000; serious cases RMB 50,000 to 500,000; criminal liability where a crime | Art. 36 |
| Breaches that cause others to under-pay tax or obtain it fraudulently | Confiscation; fine up to 1× the tax concerned | Art. 39 |
A fapiao that does not meet the rules cannot serve as a reimbursement voucher, and anyone may refuse it (Fapiao Measures Art. 20). A compliant e-invoice, by contrast, may not be refused (Implementing Rules Art. 3). For refined-oil retail, the STA's interpretation of Ann. 11/2026 set a transition period from publication to 1 November 2026 ("本公告自发布之日起至2026年11月1日为过渡期"); no other grace period has been announced. [17] [4] [5]
Frequently asked questions
Our new company hit its monthly invoicing quota halfway through the month. What can we do?
The quota caps the total invoiced amount, excluding VAT, in a calendar month (Announcement No. 11 of 2024, item 6). For taxpayers with a good credit record, the system raises the current month's quota once, automatically, when invoicing first reaches a set share of it. Beyond that, apply to your tax office for a manual increase, or raise it through the e-tax bureau's "征纳互动" function. During the filing period, until the previous period's VAT return is filed and matched, you can invoice only up to last month's remaining quota, capped at this month's quota. [1] [2]
We issued a 数电发票 by mistake. Can we cancel it?
No. An issued fully digitalised e-invoice cannot be voided; issue a full red-letter e-invoice through the platform. If the buyer has already confirmed use or booked the invoice, the reversal needs a red-letter information confirmation form that the other party must confirm within 72 hours, or it lapses. [2] [1]
Do we still have to print and stamp e-invoices for our files?
No seal is needed: invoices downloaded from the tax digital account carry a digital signature and can be booked and archived without an invoice seal. If you book a printout instead, you must also keep the electronic original (MOF and National Archives Administration notice 财会〔2020〕6号, item 4). [2] [11]
Which file should we keep: XML, PDF or OFD?
The STA offers XML (data message), PDF and OFD files. The MOF e-voucher accounting data standard (财会〔2025〕9号) supports XML e-fapiao and, for air itineraries and rail e-tickets, OFD files with embedded XBRL. No STA or MOF text says that a PDF copy is invalid. [2] [10]
Our travel platform downloads rail e-invoices for employees. Will that still work after 1 December 2026?
No. From 1 December 2026, Announcement No. 22 of 2026 bars any third-party internet platform or individual involved in railway ticket sales from issuing, delivering or downloading railway e-ticket e-invoices. Employees issue them in railway 12306 with the company name and unified social credit code, or through a scan-to-invoice slip from a station window or ticket machine. [8]
A customer refuses our e-invoice and wants paper. Must we issue a paper fapiao?
The Implementing Rules of the Fapiao Measures (Art. 3, as amended by STA Order No. 56, in force 1 March 2024) say an e-invoice has the same legal effect as paper and no unit or individual may refuse it. [5]
A private individual wants a special VAT fapiao. Can we issue one?
No. Article 37 of the VAT Law Implementing Regulations bars a special VAT fapiao where the buyer is a natural person or the supply is VAT-exempt. Issue an ordinary e-invoice. [12]
Can a foreign supplier with no Chinese entity issue a fapiao?
The VAT Law (Art. 15) makes the Chinese buyer the withholding agent when a foreign seller makes a taxable transaction in China, unless a domestic agent is appointed. The buyer deducts input VAT on the tax payment certificate (完税凭证) rather than on a fapiao. [3] [12]
Can we still book paper rail tickets or paper air itineraries?
Only for travel dates up to 30 September 2025. For later trips, rail tickets are reimbursed on the railway e-ticket e-invoice, and air passengers who need to book the expense obtain the e-itinerary or another fapiao (Announcements No. 8 and No. 9 of 2024). [6] [7]
Recent changes
- 2026-11-04 — STA/China Railway Announcement No. 22 of 2026 announced; from 1 December 2026, railway e-ticket e-invoices only through 12306 or a station scan-to-invoice slip, third-party internet platforms and individuals barred from issuing, delivering or downloading them, and a new optional format. (State Taxation Administration) — see event
- 2026-11-01 — Refined-oil retail stations must issue every fuel sale as a real-time e-fapiao through the Leqi platform ("交易即开票"); the transition period under STA Announcement No. 11 of 2026 (dated 8 June 2026) ends. (State Taxation Administration, Jiangsu bureau copy)
- 2025-05-09 — The MOF and other bodies roll out the e-voucher accounting data standard nationwide, covering XML e-fapiao and XBRL-in-OFD air and rail tickets (财会〔2025〕9号). (State Taxation Administration database)
- 2024-12-01 — Fully digitalised e-invoices rolled out nationwide (STA Announcement No. 11 of 2024, dated 12 November 2024). (State Taxation Administration) — see event
- 2024-12-01 — Domestic air passenger e-itineraries become fully digitalised e-invoices (STA/MOF/CAAC Announcement No. 9 of 2024, dated 6 November 2024). (State Taxation Administration)
- 2024-11-01 — Railway passenger e-tickets become fully digitalised e-invoices (STA/MOF/China Railway Announcement No. 8 of 2024, dated 29 September 2024). (State Taxation Administration) — see event
- 2024-03-01 — Amended Implementing Rules of the Fapiao Administrative Measures in force (STA Order No. 56). (State Taxation Administration)
Related resources
- China VAT guide — rates, registration, fapiao content rules, filing
- China tax ID (unified social credit code) guide and the USCC validator
- E-invoicing status and networks by country
- CTC e-invoicing models explained
- Taiwan e-invoicing · Vietnam e-invoicing · South Korea e-invoicing
- China tax changes on Lookuptax
Important websites
- State Taxation Administration — the e-tax bureau is reached from here and from the provincial tax bureaus' sites
- National VAT invoice verification platform — check a fapiao, rail e-ticket or air e-itinerary
- China Railway 12306 — issue railway e-ticket e-invoices
- STA Announcement No. 11 of 2024 — full text, with the specimen styles as Attachment 1
Reference links
- STA — Announcement No. 11 of 2024 on the nationwide rollout of fully digitalised e-invoices
- STA — interpretation of Announcement No. 11 of 2024
- NPC — VAT Law of the People's Republic of China
- STA database — Fapiao Administrative Measures (revised 2023)
- STA database — Implementing Rules of the Fapiao Administrative Measures, as amended by STA Order No. 56
- STA/MOF/China Railway — Announcement No. 8 of 2024 (railway e-tickets)
- STA/MOF/CAAC — Announcement No. 9 of 2024 (air e-itineraries)
- STA/China Railway — Announcement No. 22 of 2026 (railway e-invoices)
- STA — interpretation of Announcement No. 22 of 2026
- MOF and others — 财会〔2025〕9号, e-voucher accounting data standard (STA database copy)
- MOF and National Archives Administration — 财会〔2020〕6号, booking and archiving electronic accounting vouchers
- State Council — VAT Law Implementing Regulations (Order No. 826)
- State Council — Opinions on Further Deepening Tax Collection and Administration Reform (2021)
- STA Jiangsu Provincial Tax Bureau — guideline on Leqi self-use direct connection (2023)
- State Council — Announcement No. 11 of 2024 (mirror)
- STA — Announcement No. 11 of 2026 on "交易即开票" in refined-oil retail (STA Jiangsu bureau copy)
- STA — interpretation of Announcement No. 11 of 2026