Streamlined Sales Tax (SSUTA)
The Streamlined Sales and Use Tax Agreement (SSUTA) is a voluntary agreement among US states to simplify sales and use tax collection. It provides uniform definitions, state-level administration, one central registration system and state-paid Certified Service Providers. As at 3 November 2026, 24 states take part: 23 full members and one associate member (Tennessee).
The Agreement's stated purpose is "to simplify and modernize sales and use tax administration in the member states in order to substantially reduce the burden of tax compliance" (SSUTA §102). It is administered by the Streamlined Sales Tax Governing Board, Inc. (SSTGB), a nonprofit incorporated in Indiana: "Authority to administer the Agreement shall rest with the Governing Board comprised of representatives of each member state" (SSUTA §806). The Agreement was "Adopted November 12, 2002 and amended through October 15, 2026" (SSUTA as amended through 15 October 2026).
It was a response to the physical-presence rule. The project "was created by the National Governor's Association (NGA) and the National Conference of State Legislatures (NCSL) in the fall of 1999 to simplify sales tax collection", and "the effort that became the Streamlined Sales Tax® Governing Board began in March 2000". Its goal was to fix the complexity behind the Supreme Court holdings in Bellas Hess and Quill "that a state may not require a seller that does not have physical presence in the state to collect tax on sales into the state" (SSTGB FAQ; About SSTGB). The Supreme Court overruled that rule in South Dakota v. Wayfair on 21 June 2018 (see South Dakota v. Wayfair explained).
This page is about the US Streamlined Sales Tax. Malaysia's Sales and Service Tax is also called SST and is unrelated; see how to register for SST in Malaysia.
How it works
The Governing Board lists ten simplifications: state-level administration, uniform state and local tax bases, uniform definitions, a central electronic registration system, simplified rates, uniform sourcing, simplified exemption administration, simplified returns, simplified remittances, and consumer privacy (About SSTGB). The ones a seller deals with day to day are below.
State-level administration and uniform bases
"Sellers and purchasers are only required to register with, file returns with, and remit funds to the state level authority." The state collects local taxes and distributes them, and "local jurisdictions shall not conduct independent sales or use tax audits of sellers and purchasers" (SSUTA §301.A). State and local tax bases must be the same, with limited exceptions such as motor fuel, energy and vehicles, aircraft, watercraft and homes (SSUTA §302).
Uniform definitions — states still decide what to tax
"The Agreement defines over 100 different administrative terms and products and services that states either tax or exempt" (SSTGB FAQ). The Agreement does not decide taxability. Under SSUTA §103 it "shall not be construed as intending to influence a member state to impose a tax on or provide an exemption from tax for any item or service. However, if a member state chooses to tax an item or exempt an item from tax, that state shall adhere to the provisions concerning definitions as set out in Article III".
Rates and rate changes
- One state rate, plus one optional food and drug rate. A member state may not have multiple state rates, "except that a member state may impose a single additional rate, which may be zero, on food and food ingredients and drugs" (SSUTA §308.A).
- One local rate per jurisdiction. A member state "shall not have more than one local sales tax rate or more than one local use tax rate per local jurisdiction" (SSUTA §308.B).
- Local rate changes: mandatory quarter start. States must "provide that local rate changes will be effective only on the first day of a calendar quarter after a minimum of sixty days' notice to sellers" (SSUTA §305.A.1). Local boundary changes follow the same rule (§305.A.3).
- State rate changes: "reasonable effort" only. For its own rate, a state must make "a reasonable effort to do all of the following", including "2. Limit the effective date of a rate change to the first day of a calendar quarter" (SSUTA §304.A). If fewer than 30 days pass between enactment and the effective date, the state must relieve sellers of liability for failing to collect at the new rate, within limits (§304.C).
- Rate and boundary databases. Each member state publishes rate and boundary files, which "must be provided at no cost to the user of the database" (SSUTA §307.A). "The states hold a business harmless for charging too much or too little tax if the business calculated and collected the incorrect tax based on the state's rate and boundary files" (SSTGB FAQ; SSUTA §305–306).
Sourcing
Sales are sourced to where the buyer receives the product. When the product is not received at the seller's business location, "the sale is sourced to the location where receipt by the purchaser (or the purchaser's donee, designated as such by the purchaser) occurs" (SSUTA §310.A.2). A member state may instead source to where the order is received only when the order is received in the same state where the buyer takes delivery (SSUTA §310.1.B). In practice, interstate sales are destination-sourced and the origin election applies only to intrastate orders.
Central registration (SSTRS)
The Streamlined Sales Tax Registration System at sstregister.org lets a seller register in all or selected member states with one application. That includes the associate member, Tennessee, as well as the 23 full members as at 2026-11-03 (state information).
 Source snapshot captured 2026-07-19 — original
What happens after you submit (all SSTGB):
- No fee. "There is no fee to register through the SSTRS. (Note: A state may charge a fee if you are legally required to register in that state.)" No written signature is required (SSUTA §303.D).
- A confirmation email, not a permit. "When you submit the registration a confirmation email will be sent to the contact person." The SSTRS passes your details to the states you chose, and "the states will issue your business a sales tax account" (SSTRS FAQ).
- Each state sends the number. "Most states will send you registration and reporting information within 15 business days."
- Returns go to each state. "No returns are filed through the Streamlined Sales Tax Registration System", and "returns must be filed even if you have no sales in that state."
- Registering creates a collection duty. "If you register for a sales and use tax permit, you are required to collect and remit sales tax to each state even if you don't have nexus" (sstregister.org). By registering, the seller "agrees to collect and remit sales and use taxes for all taxable sales into the states in which the seller elected to register" (SSUTA §401.B).
- Registration alone is not nexus. A state "shall not use registration with the central registration system and the collection of sales and use taxes in the member states as the sole factor in determining whether the seller has nexus with that state for any tax at any time" (SSUTA §401.D).
- You can update registrations and end them in selected or all states through the same system (SSUTA §303; SSTRS FAQ).
The SSTGB reports "Total Active Registrations: 36,132 (28.6% of the businesses registered through the SSTRS contract with a CSP™) (as of 9/30/2026)" (SSTGB).
Certified Service Providers (CSPs)
"A CSP is an agent certified under the Streamlined Sales and Use Tax Agreement to perform all the seller's sales and use tax functions, other than the seller's obligation to remit tax on its own purchases" (SSTGB). Sellers that want a CSP register through the SSTRS, and the CSP can complete the registration for them.
Current providers (as at 2026-11-03). The Governing Board lists Avalara, TaxCloud, Sovos, AccurateTax and Avior as certified CSPs offering free services. Exactor (a subsidiary of Intuit) is certified but "not currently offering free services under Streamlined's CSP program" (CSP list). A Certified Automated System (CAS) is different: certified calculation software for a seller that keeps filing and remitting in-house.
Who gets a CSP free. The states pay the CSP in each state where the seller is a "CSP-compensated seller" (the former "volunteer seller"). Under the 2025–2026 CSP contract (§D.2(b)), that is a seller registered through the SSTRS that, in the 12 months before registering in the state, had:
- no fixed place of business in the state for more than 30 days;
- less than $50,000 of property and less than $50,000 of payroll in the state;
- less than 25% of its total property or total payroll in the state; and
- was not collecting the state's tax as a condition of being a state supplier.
The economic-nexus case does not replace these tests: "a Seller who meets the criteria in Section D.2.(b)(1) and (2), but is required to register, collect and remit sales or use tax in a Streamlined State only because it meets or exceeds that state's economic nexus threshold is a CSP-compensated Seller for that state" (§D.2(b)(3)). A marketplace facilitator that meets the tests can also qualify (CSP contract 2025–2026).
What the states pay the CSP. Per state, per CSP-compensated seller: "five percent (5%) of the first $500,000 of Taxes Due in that Streamlined State and two percent (2%) of the Taxes Due in that Streamlined State in excess of the $500,000". For a seller with gross sales of $100,000 or less in the state in the previous calendar year: 6% of the first $8,000 of tax due, 5% from $8,000 to $500,000, and 2% above (CSP contract §D.5). A state may agree a different structure directly with the CSP.
Contract end date. The contract "shall be effective until December 31, 2026" (§C.1). It extends automatically for three years unless either party gives 90 days' notice (§C.2). As at 2026-11-03 the SSTGB's CSP page links only the 2025–2026 contract, so the rates above are the 2025–2026 terms.
Audit protection. "Any business that uses Streamlined - certified software is generally immune from audit liability for the sales they process through that software" (SSTGB FAQ). The protection covers tax calculated through the certified system, not the seller's other obligations.
Marketplace collection is a separate mechanism. Where a marketplace collects tax for its third-party sellers, that comes from each state's marketplace-facilitator law, not from a CSP arrangement; see marketplace deemed supplier rules.
Exemption certificate (Form F0003)
The Governing Board publishes one multistate form, SSTGB Form F0003, the Streamlined Sales Tax Certificate of Exemption (Revised 12/21/2021). "The Streamlined Sales Tax ® Exemption Certificate and instructions are accepted by all 24 Streamlined member states" (SSTGB exemptions). The buyer gives it to the seller: "Do not send this form to the Streamlined Sales Tax Governing Board. Send the completed form to the seller and keep a copy for your records" (Form F0003). "Not all states allow all exemptions listed on this form", and the SSTGB's exemptions page notes that "GA requires the seller verify the purchaser's ID number". "Purchasers that claim an incorrect exemption are responsible for paying the sales or use tax, interest and penalties" (SSTGB FAQ).
Governance and membership
The Governing Board
"Each member state may appoint up to four representatives to the Governing Board. … Each member state shall be entitled to one vote on the Governing Board" (SSUTA §806). Since 2023, full, contingent and associate member states are all "qualified to vote" on Governing Board matters (SSUTA §801.5.A), although associates are excluded from some votes (below).
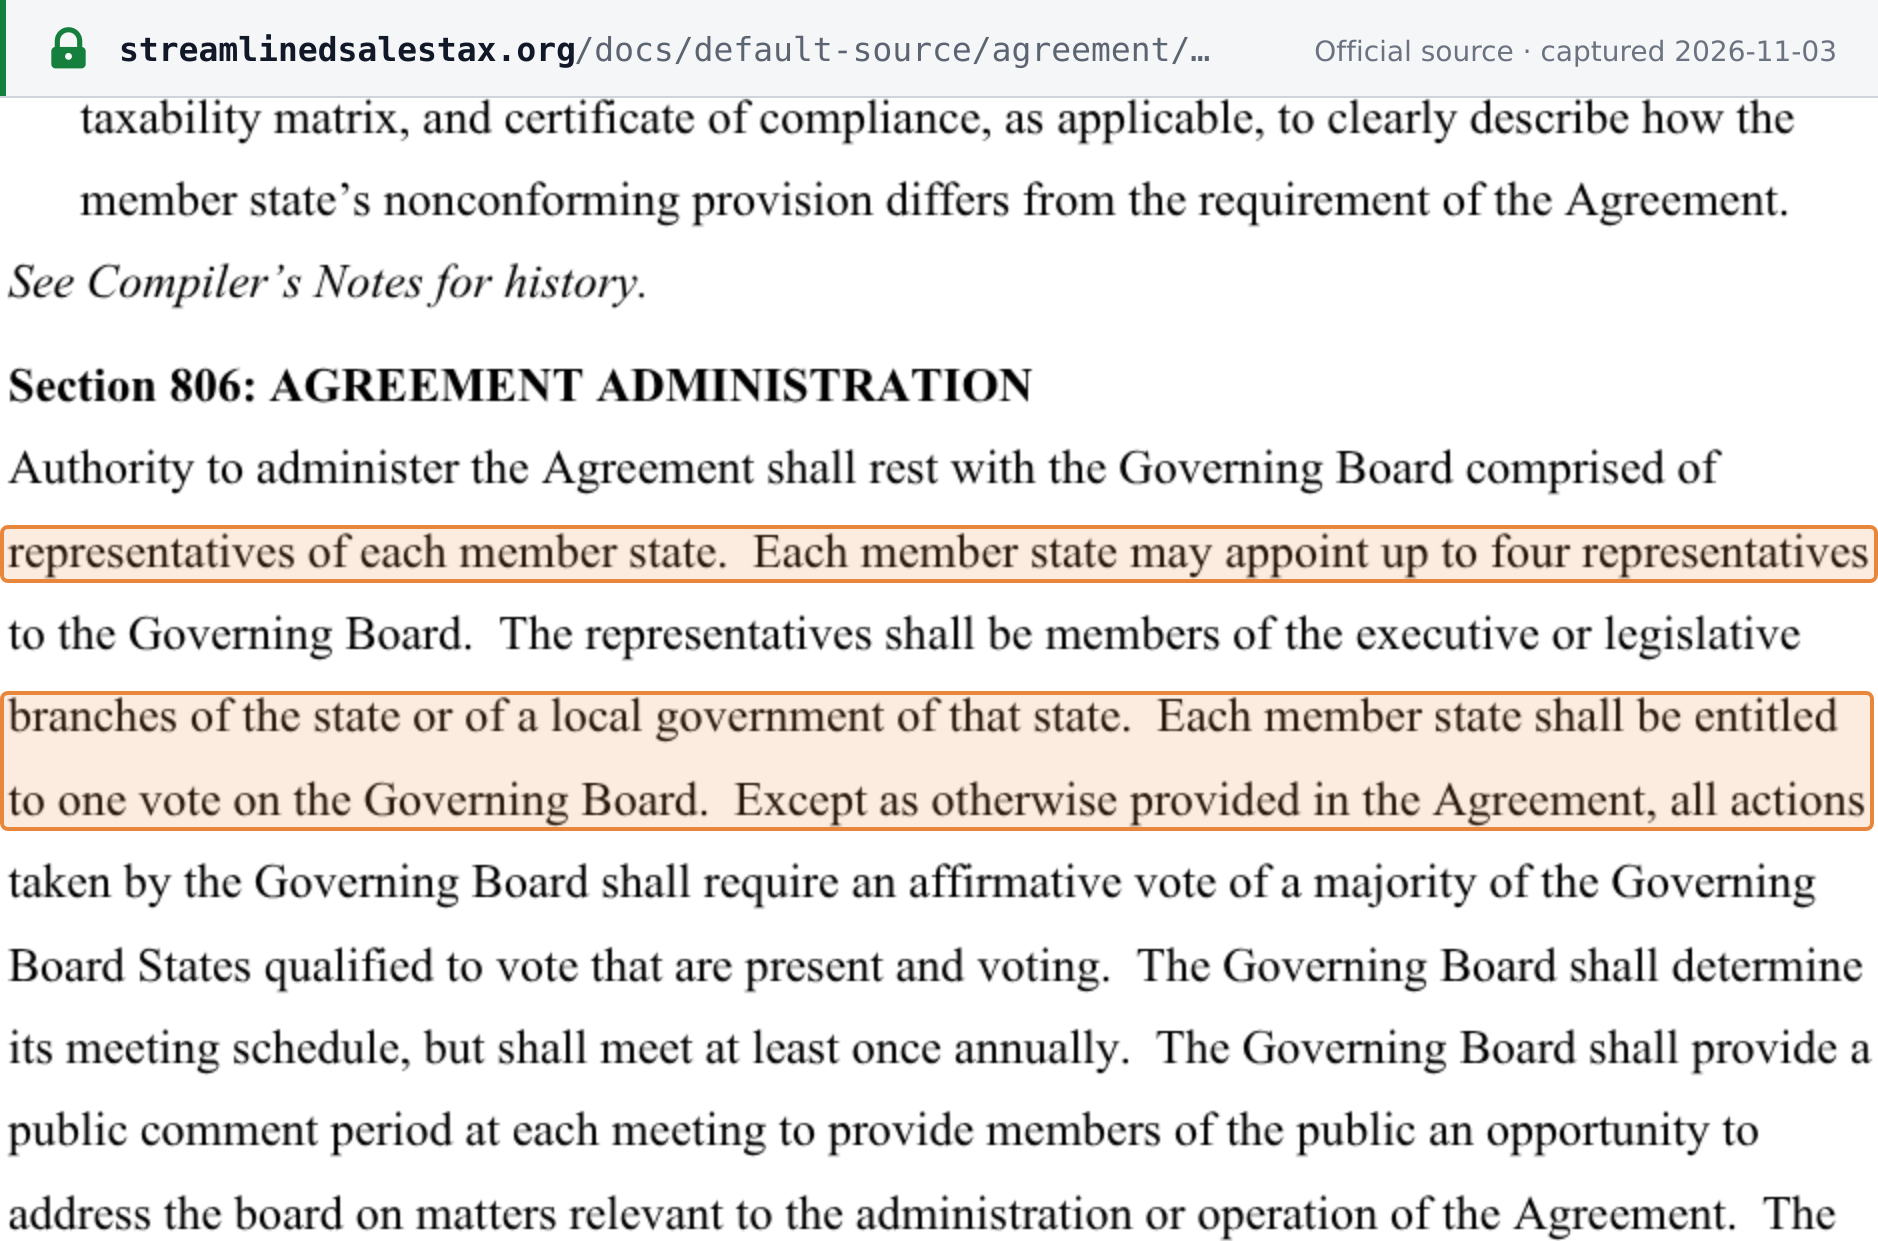 Source snapshot captured 2026-11-03 — original
Membership tiers (SSUTA §801)
| Tier | Definition | Key rights and limits |
|---|---|---|
| Full member | "Found in compliance pursuant to Sections 804 and 805 and the changes to their statutes, rules, regulations or other authorities necessary to bring them into compliance are in effect" (§801.1) | Votes on amendments, interpretations and compliance; sits on the Compliance Review and Interpretations Committee (CRIC) |
| Contingent member | In compliance, but the conforming laws take effect within 12 months of the proposed entry date (§801.2.A) | "All the rights and privileges of a full member state, except as provided in this subsection" (§801.2.B): it receives no seller registration information, and no audit information unless it was party to the audit; sellers may, but need not, collect there unless otherwise required by law |
| Associate member | "Substantial compliance with the terms of the Agreement taken as a whole, but not necessarily each provision" (§801.3) | May not vote on amendments, interpretations or any state's compliance, and may not sit on CRIC (§801.3.A); receives no seller registration information, and no audit information unless it was party to the audit (§801.3.D); sellers may, but need not, collect there unless otherwise required by law (§801.3.C) |
| Advisor state | Pre-October 2005 implementing states, or states joining by legislation or memorandum (§801.4) | "Ex officio capacity on the Governing Board, with non-voting status" |
As at 2026-11-03, the SSTGB's state-information page lists full, associate and non-member states. It lists no contingent member and publishes no advisor-state list (state information).
Joining and staying in
- Petition and vote. "A three-fourths vote of the Governing Board States qualified to vote is required to approve a state's petition for membership." Membership starts on the later of the proposed entry date and the first day of the calendar quarter after approval, and "is at least sixty days after its petition is approved" (SSUTA §804).
- Petition fee. $20,000, held in escrow, returned if the state is not admitted, and credited against dues if it is (Governing Board Rules 806.1.5.C–D, Rules as amended through 15 October 2026).
- Annual recertification. "Each member state shall make a re-certification to the Governing Board on or before August 1 of each year after the year of the state's entry based on the state's laws as of July 1" (SSUTA §803). By 15 September the Executive Director reports potential compliance issues to CRIC (Rule 803.C).
- Noncompliance. A finding that a state is out of compliance needs a three-fourths vote, excluding that state (§805.1.B). The state must then file a statement of noncompliance within 60 days (§805.1.E). Sanctions and expulsion are in §§808–809.
- Petitions from outside. "Any member state or person, including the Business Advisory Council" may petition for reconsideration of a Governing Board decision or invoke the issue resolution process (SSUTA §1002).
Who it affects
- Remote sellers that choose the SSTRS. Using the system is optional: "Only those sellers that want the benefits of the SSUTA must register through the SSTRS" (SSTRS FAQ). Sellers that use it must collect in every full member state they select, whether or not they have nexus there. In Tennessee, the associate member, a seller "may, but is not required to collect" unless otherwise required by law (SSUTA §801.3.C).
- Sellers without a physical footprint. These are the CSP-compensated sellers for whom the states pay a CSP, including sellers registered only because they crossed a state's economic nexus threshold.
- Buyers claiming exemption in any of the 24 states, who can use Form F0003.
- Sellers in non-member states such as California, Texas, New York and Florida are not covered. Sellers cannot register in those states through the SSTRS (state information) and must follow each state's own rules; see the US sales tax guide.
Current status and dates (as at 2026-11-03)
- 24 participating states: 23 full members and one associate member. The full members are Arkansas, Georgia, Indiana, Iowa, Kansas, Kentucky, Michigan, Minnesota, Nebraska, Nevada, New Jersey, North Carolina, North Dakota, Ohio, Oklahoma, Rhode Island, South Dakota, Utah, Vermont, Washington, West Virginia, Wisconsin and Wyoming. "Tennessee is the only Associate Member State at this time" (state information; SSTGB FAQ).
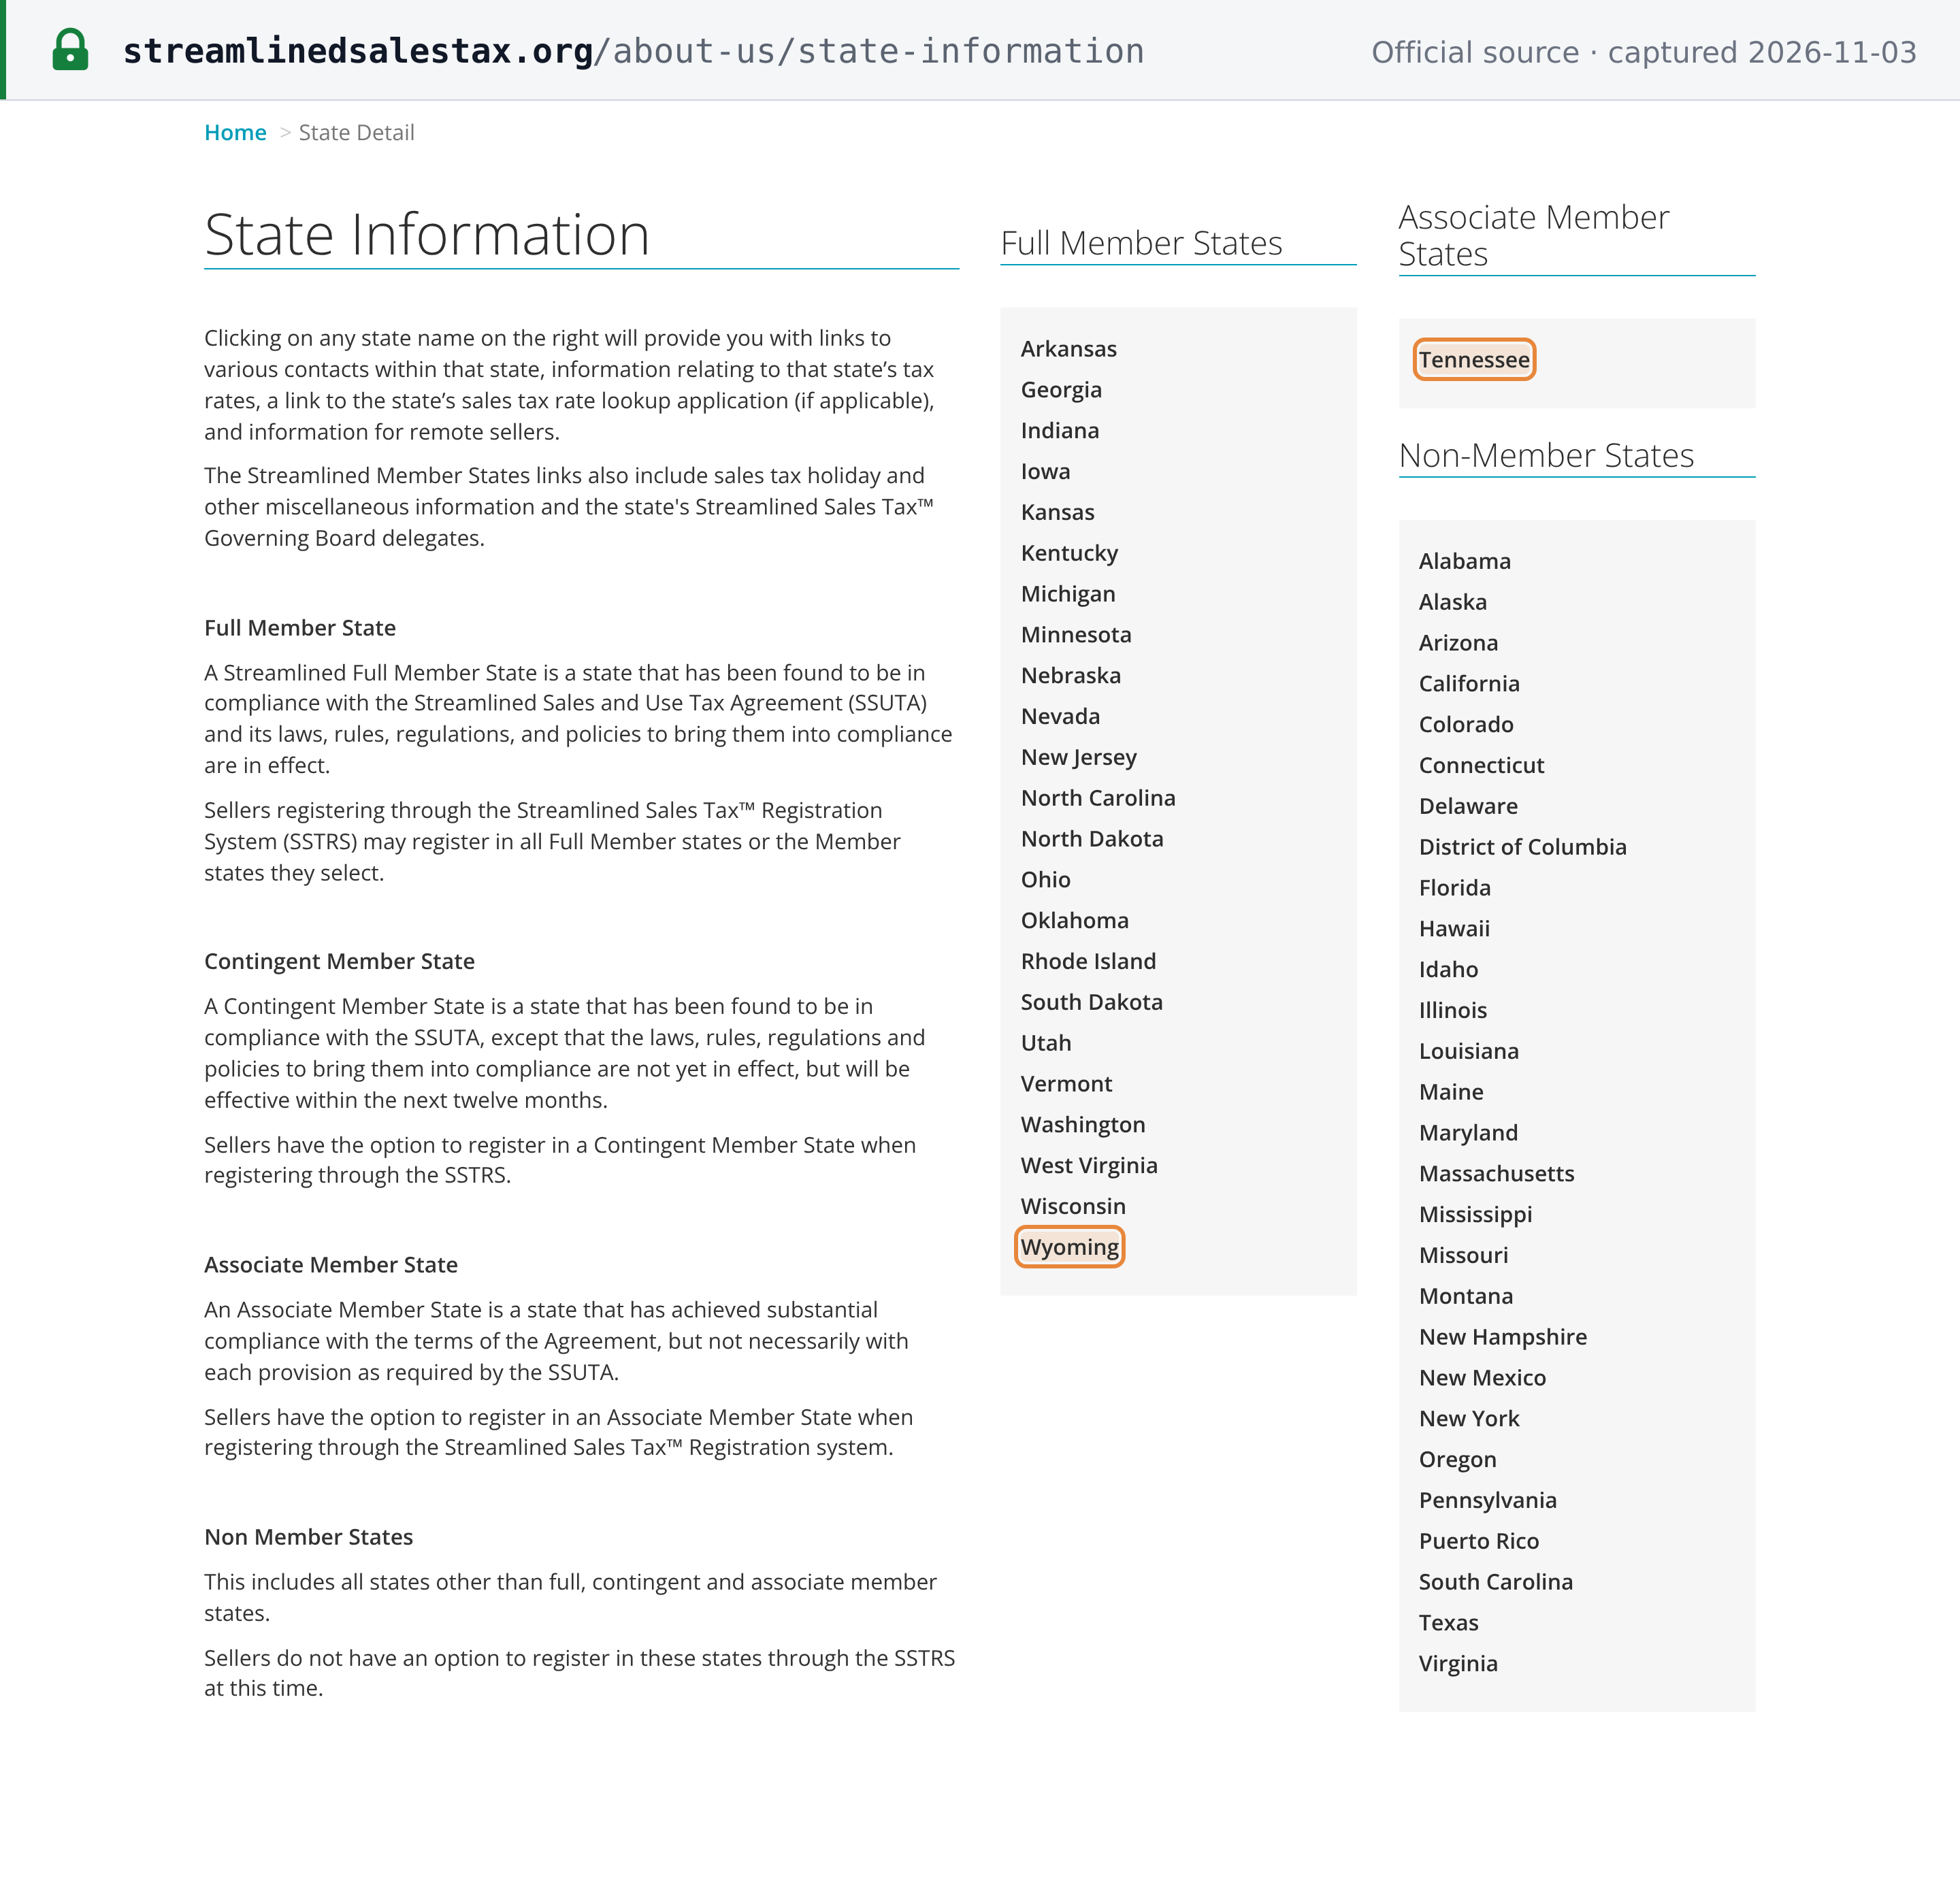 Source snapshot captured 2026-11-03 — original
- No change of membership status since Ohio became a full member on 1 January 2014. The Governing Board's recertification-letter index shows the same 24 states recertifying in 2025 and 2026. The most recent change of status on any state's SSTGB page is Ohio, which "became an associate member of Streamlined Sales Tax on October 1st, 2005 and a full member on January 1, 2014" (Ohio).
- Agreement amended through 15 October 2026. The current text reads "Adopted November 12, 2002 and amended through October 15, 2026", and its amendment list ends "May 13, 2026 and October 15, 2026".
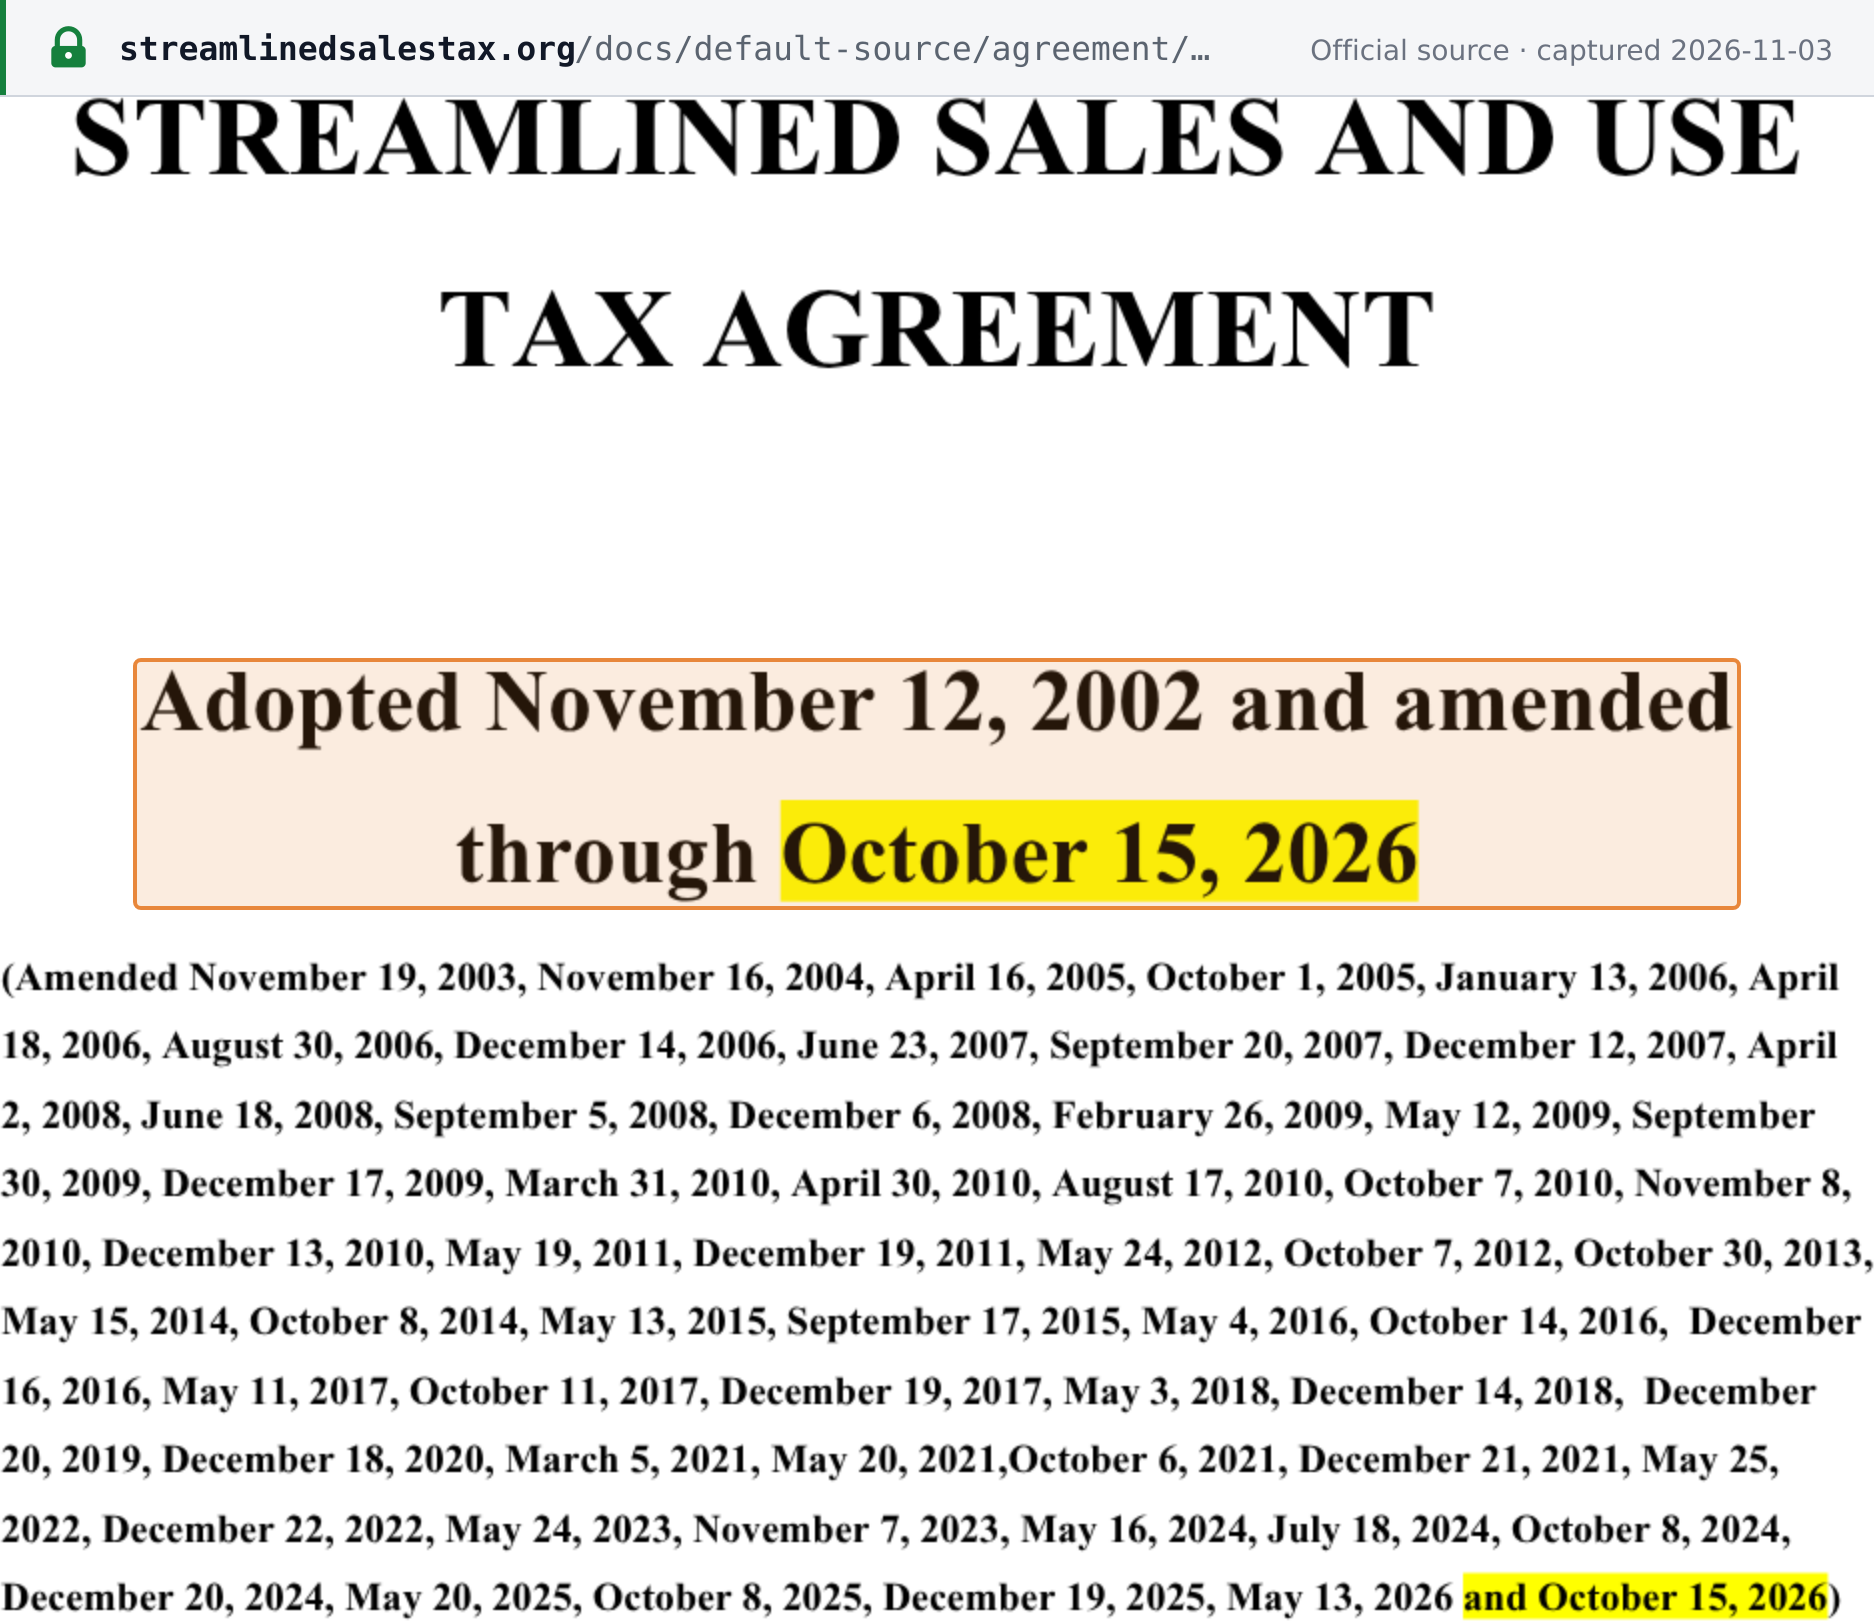 Source snapshot captured 2026-11-03 — original
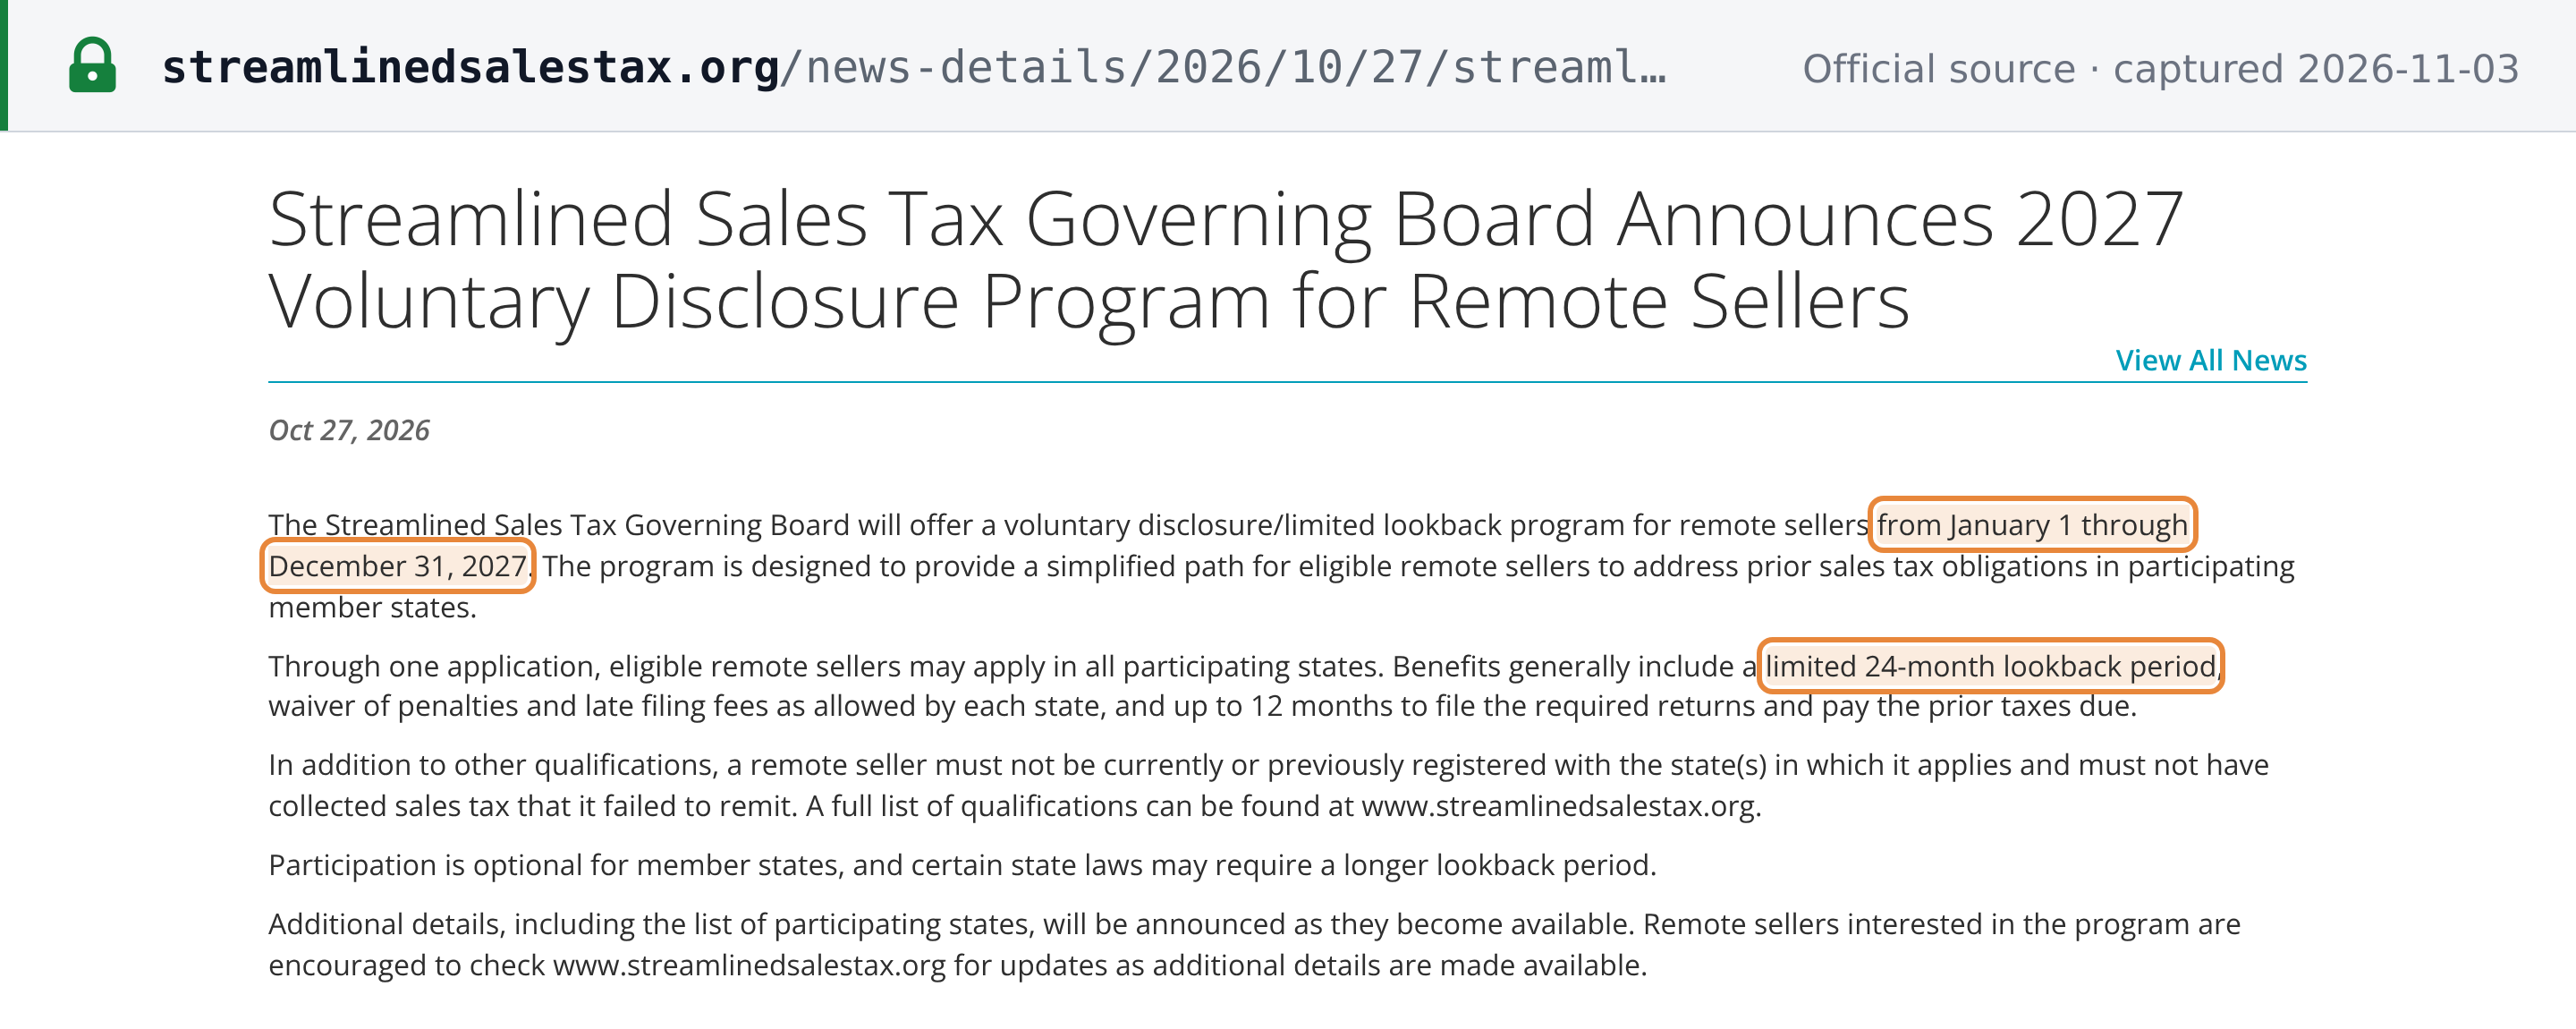
- New: Streamlined Sales Tax Voluntary Disclosure Program (SSTVD), 1 January to 31 December 2027.
"On October 14, 2026 the Governing Board adopted AM26010-02 which ended the amnesty program provided
under Section 402 and adopted the Streamlined Sales Tax Voluntary Disclosure Program (SSTVD) for
Remote Sellers. The SSTVD begins January 1, 2027" (SSUTA §402.1, compiler's note). The Governing
Board announced it on 27 October 2026: "Benefits generally include a limited 24-month lookback
period, waiver of penalties and late filing fees as allowed by each state, and up to 12 months to
file the required returns and pay the prior taxes due"
(SSTGB news, 27 Oct 2026).
The Agreement text is more precise: returns are due within 12 months of receiving the signed
contract back from the state, and the balance is due "within 30 calendar days of the state providing
the balance due, or as otherwise required by each state" (SSUTA §402.1.C.1.e). The SSTVD FAQ says
the same: "You will have 30 days to make the payment once the state notifies you of the balance due,
unless the state grants you additional time to pay"
(SSTVD FAQ).
- The program "sunsets on December 31, 2027, unless the Streamlined Sales Tax Governing Board … votes to extend the program" (SSUTA §402.1.A.1).
- "Full-member state participation is voluntary. Full-member states must affirmatively elect to opt in to the SSTVD. Associate and contingent member states are required to offer the SSTVD" (SSTVD program). Tennessee's SSTVD continues after 31 December 2027 (SSTVD FAQ).
- Sellers that register in the SSTRS between 14 October and 31 December 2026, and meet the other criteria, "may apply for the SSTVD no later than January 15, 2027" (SSTVD program).
- Participating states (as at 2026-11-03): the program page lists "Participating Full Member States as of 10/27/26": Kentucky, and "Participating Associate Member States": Tennessee, and marks the list "Work in progress…check back often for updates" (SSTVD program). Other full members may still opt in.
 Source snapshot captured 2026-11-03 — original
- The §402 registration amnesty now applies in Tennessee only. "Tennessee is the only state offering amnesty at this time" (SSTGB amnesty). It ends when the SSTVD begins (SSUTA §402.G).
- CSP contract runs until 31 December 2026, with automatic three-year extension unless notice is given (see CSPs).
Jurisdiction table — participating states
Status is from the SSTGB state-information page. Entry dates are quoted from each state's SSTGB page ("The state of … became a … member of Streamlined Sales Tax on …"). Last confirmed is the date that source was read. Thirteen states' pages give 1 October 2005 as their full-membership date, and Ohio, Tennessee and Utah became associates that day.
| State | Status | Entry and status history | Last confirmed | Source |
|---|---|---|---|---|
| Arkansas | Full | Full member 1 Jan 2008 | 2026-11-03 | SSTGB — Arkansas |
| Georgia | Full | Associate 1 Jan 2011; full 1 Jul 2011 | 2026-11-03 | SSTGB — Georgia |
| Indiana | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Indiana |
| Iowa | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Iowa |
| Kansas | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Kansas |
| Kentucky | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Kentucky |
| Michigan | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Michigan |
| Minnesota | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Minnesota |
| Nebraska | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Nebraska |
| Nevada | Full | Full member 1 Apr 2008 | 2026-11-03 | SSTGB — Nevada |
| New Jersey | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — New Jersey |
| North Carolina | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — North Carolina |
| North Dakota | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — North Dakota |
| Ohio | Full | Associate 1 Oct 2005; full 1 Jan 2014 | 2026-11-03 | SSTGB — Ohio |
| Oklahoma | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — Oklahoma |
| Rhode Island | Full | Full member 1 Jan 2007 | 2026-11-03 | SSTGB — Rhode Island |
| South Dakota | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — South Dakota |
| Tennessee | Associate | Associate 1 Oct 2005; the only associate member, the only §402 amnesty state, and required to offer the SSTVD | 2026-11-03 | SSTGB — Tennessee |
| Utah | Full | Associate 1 Oct 2005; full 1 Oct 2012 | 2026-11-03 | SSTGB — Utah |
| Vermont | Full | Full member 1 Jan 2007 | 2026-11-03 | SSTGB — Vermont |
| Washington | Full | Full member 1 Jul 2008 | 2026-11-03 | SSTGB — Washington |
| West Virginia | Full | Full member 1 Oct 2005 | 2026-11-03 | SSTGB — West Virginia |
| Wisconsin | Full | Full member 1 Oct 2009 | 2026-11-03 | SSTGB — Wisconsin |
| Wyoming | Full | Full member 1 Jan 2008 | 2026-11-03 | SSTGB — Wyoming |
All other states, the District of Columbia and Puerto Rico are listed as non-member states, and sellers "do not have an option to register in these states through the SSTRS at this time" (state information).
Recent changes
- 2026-10-27 — The Governing Board announced the 2027 Streamlined Sales Tax Voluntary Disclosure Program (SSTVD) for remote sellers. It runs from 1 January to 31 December 2027 with a limited 24-month lookback, and full-member participation is optional. (SSTGB)
- 2026-10-14 — Amendment AM26010-02 added SSUTA §402.1 (SSTVD) and ends the §402 registration amnesty when the SSTVD begins on 1 January 2027. (SSUTA as amended through 15 October 2026)
Frequently asked questions
If I register through the SSTRS, do I have to collect in states where I am below the economic nexus threshold?
Yes, in every full member state you select. sstregister.org says that once you register "you are required to collect and remit sales tax to each state even if you don't have nexus" (SSUTA §401.B). Tennessee, the associate member, is different: a seller may, but is not required to, collect there unless it is otherwise required to under state law (SSUTA §801.3.C). Registration through the SSTRS is not by itself a nexus factor for any tax (SSUTA §401.D).
Does the SSTRS issue my state sales tax permits?
No. When you submit the registration, the SSTRS sends a confirmation email to the contact person and passes your details to the states you selected. Each state issues the sales tax account, and most states send registration and reporting information within 15 business days. Returns are filed with each state, not through the SSTRS, even when you had no sales. Registering through the SSTRS is free, although a state may charge a fee where you are legally required to register.
Will the states pay for a Certified Service Provider for my business?
Only in states where you are a CSP-compensated seller. Under the 2025–2026 CSP contract, that means you registered through the SSTRS and, in the 12 months before registering, had no fixed place of business in the state for more than 30 days, less than $50,000 of property and of payroll there, less than 25% of your total property or payroll there, and were not collecting the state's tax as a condition of being a state supplier (CSP contract 2025–2026 §D.2(b)). A seller that meets these tests is still a CSP-compensated seller even if it registered only because it crossed the state's economic nexus threshold (§D.2(b)(3)). As at 3 November 2026, Avalara, TaxCloud, Sovos, AccurateTax and Avior offer free CSP services (SSTGB CSP list). The contract runs until 31 December 2026 and extends automatically for three years unless either party gave notice at least 90 days before it expires (§C.1–C.2).
Can I clean up past sales tax exposure in Streamlined states?
From 1 January to 31 December 2027, through the Streamlined Sales Tax Voluntary Disclosure Program (SSTVD) in participating states. It offers a limited 24-month lookback and waiver of penalties and late filing fees as each state allows. Returns are due within 12 months of receiving the signed contract back from the state, and payment within 30 days of the state's balance-due notice unless the state allows more time (SSUTA §402.1.C.1.e). Full members must opt in: as at 3 November 2026 the program page lists Kentucky as the participating full member state (as of 10/27/26) and Tennessee as the participating associate member state, and calls the list a work in progress (SSTVD program). Until the SSTVD starts, the §402 registration amnesty is available in Tennessee only (SSTGB amnesty).
Which exemption certificate works across the Streamlined states?
SSTGB Form F0003, the Streamlined Sales Tax Certificate of Exemption (Revised 12/21/2021), is accepted by all 24 Streamlined member states (SSTGB exemptions). Give it to the seller, not to the Governing Board. Not all states allow all exemptions listed on the form, and Georgia requires the seller to verify the purchaser's ID number. A purchaser that claims an incorrect exemption is responsible for the tax, interest and penalties (SSTGB FAQ).
Related resources
- South Dakota v. Wayfair explained — the 2018 decision that ended the physical-presence rule and introduced economic nexus
- Marketplace deemed supplier rules — how marketplace-facilitator collection works, separately from CSPs
- United States sales tax guide — state nexus thresholds, marketplace rules and registration
- United States tax ID guide — the EIN, which is not a sales tax permit
- How to verify an EIN
- How to register for VAT, sales tax or GST
- Tax-change chronology: United States
Reference links
- Streamlined Sales and Use Tax Agreement, as amended through 15 October 2026
- Governing Board Rules, as amended through 15 October 2026
- SSTGB — state information
- SSTGB — Streamlined Sales Tax Registration System and sstregister.org
- SSTGB — Certified Service Providers list
- CSP contract 2025–2026
- SSTGB Form F0003 — Certificate of Exemption
- SSTGB — SST voluntary disclosure program (SSTVD)