Albania auto-files missed VAT returns, sets cash limits and mandates POS terminals (Law 79/2025)
- Jurisdiction
- Albania
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Plan ahead
- Announced
- 11 December 2025
- Effective
- 29 January 2026
- Instrument
- AL-STATUTE-79-2025
- Authority
- Kuvendi i Republikës së Shqipërisë (Albanian Parliament)
- Verified
- Fetched from official source · high confidence
VAT-registered taxpayers in Albania; businesses selling for cash (POS/POI duty), with exemptions for areas without internet, invoice-exempt taxpayers and single self-employed non-VAT taxpayers.
Businesses with POS obligations must comply by 30 May 2026 (tourism, transport, public sector) or 31 December 2026 (others). Tax authority auto-files VAT returns within 24 hours if taxpayer misses deadline.
Law No. 79/2025, adopted by the Albanian Assembly on 11 December 2025, amends Law No. 9920/2008 on Tax Procedures; it enters into force 15 days after publication in the Official Gazette (reported as FZ No. 11 of 14 January 2026, giving 29 January 2026). If a taxpayer misses the VAT return deadline, the tax administration's system completes and files the VAT return automatically within 24 hours from the sales and purchase ledgers; the taxpayer bears the late-filing penalty and may review and amend the return. Cash sale or purchase transactions are capped at ALL 100,000 between taxpayers/entities and ALL 500,000 with individuals. Taxpayers selling for cash must have a POS/POI terminal at every point of sale by 30 May 2026 (accommodation structures, transport services, public institutions and state-owned companies) or 31 December 2026 (all others), with exemptions for areas without internet, invoice-exempt taxpayers and certain single self-employed non-VAT taxpayers. Tax notices are served to the taxpayer's e-filing account and/or by registered post.
What changed in detail
Law No. 79/2025, adopted by the Albanian Assembly on 11 December 2025, amends Law No. 9920/2008 on Tax Procedures. Under its article 19 it enters into force 15 days after publication in the Official Gazette. Publication was reported as Fletorja Zyrtare No. 11 of 14 January 2026, which would give 29 January 2026; we have not confirmed the gazette date from the gazette itself.
- Automatic VAT returns (art. 11, new art. 71/1(6)). If a taxpayer misses the VAT return deadline, the tax administration’s electronic system completes and files the return within 24 hours, from the taxpayer’s sales and purchase ledgers. The taxpayer bears any late-filing penalty and may review, change or correct the return.
- Cash limits (art. 5, art. 59). Cash sale or purchase transactions are prohibited above ALL 100,000 between taxpayers, traders, the self-employed and entities, and above ALL 500,000 with individuals.
- POS/POI terminals (art. 6, new art. 59/3). Taxpayers selling for cash must have a card terminal at every point of sale by 30 May 2026 (listed accommodation structures, transport services, public institutions and state-owned companies) or 31 December 2026 (all others). Exempt are businesses in areas without internet coverage, taxpayers exempt from invoicing, and single self-employed taxpayers outside VAT with one business location.
- Notices (art. 1, art. 23). Assessments, notices, decisions and official communications are served to the taxpayer’s “e-filing” account and/or by registered post, and are treated as received no later than 10 calendar days after sending.
What it means
The law is in force. We have not found a later amendment to these rules, but Law 9920 has been the subject of further amending proposals, so check the current consolidated text before relying on these figures.
The auto-filed VAT return removes the option of simply not filing: a return now exists from the ledgers whether or not the business submits one, and the penalty still applies. A business whose sales or purchase ledger is incomplete should correct the auto-filed return rather than leave it.
The first POS deadline has passed. The general deadline of 31 December 2026 is still ahead for cash-selling businesses outside tourism accommodation, transport and the public sector.
Proof
6. Në rast se tatimpaguesi nuk ka dorëzuar deklaratën e TVSH-së brenda afatit të përcaktuar në ligj, sistemi elektronik i administratës tatimore, brenda 24 orëve nga përfundimi i këtij afati, plotëson dhe dorëzon automatikisht deklaratën e TVSH-së mbi bazën e të dhënave të librit të shitjes e të librit të blerjes.6. Where the taxpayer has not filed the VAT return within the deadline set by law, the tax administration’s electronic system, within 24 hours of the end of that deadline, completes and files the VAT return automatically on the basis of the data in the sales ledger and the purchase ledger.
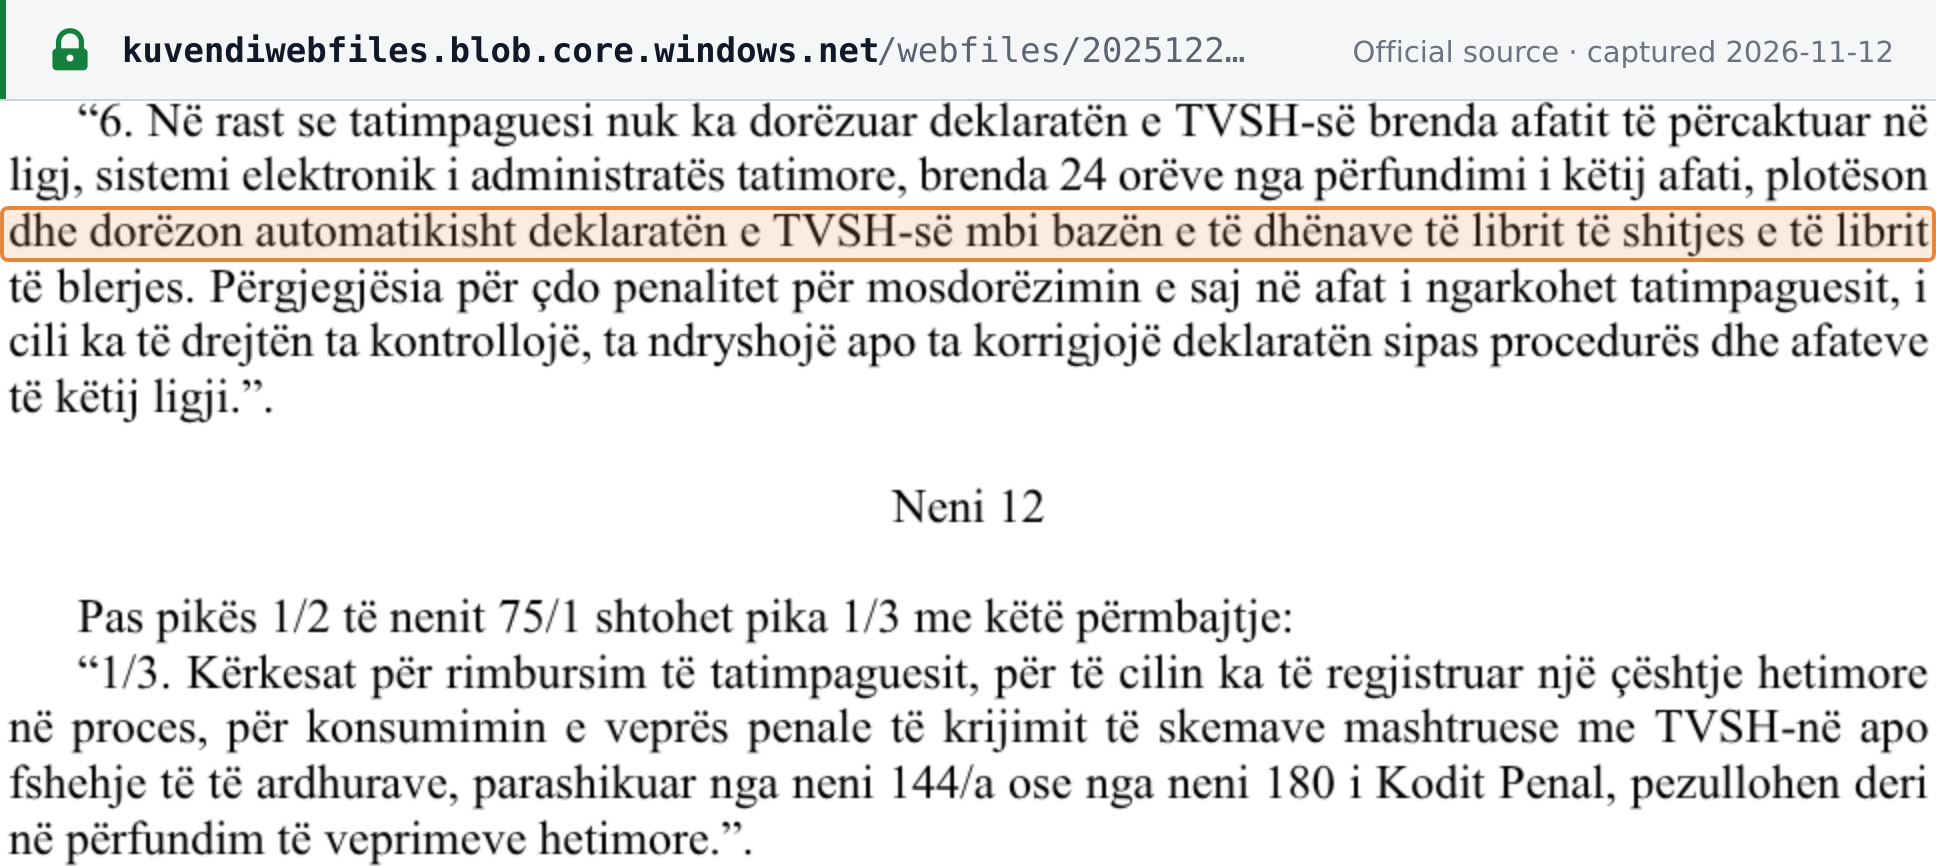 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Ligj Nr. 79/2025, miratuar në datën 11.12.2025 (Kuvendi i Republikës së Shqipërisë) · kuvendiwebfiles.blob.core.windows.net