Antigua and Barbuda sets the ABST return deadline at 15 calendar days after each tax period
- Jurisdiction
- Antigua and Barbuda
- Tax
- ABST
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 2 April 2024
- Effective
- 1 March 2024
- Instrument
- AG-STATUTE-1-of-2024
- Authority
- Ministry of Legal Affairs, Antigua and Barbuda
- Verified
- Fetched from official source · high confidence
Every ABST-registered taxable person in Antigua and Barbuda, for the tax period ending 31 March 2024 and every later period.
No action — monitoring only.
The Antigua and Barbuda Sales Tax (Amendment) Act 2024 (No. 1 of 2024), assented by the Governor-General on 2 April 2024 and published in the Official Gazette Vol. XLIV No. 22 on 2 April 2024, amended section 39(1) of the ABST Act 2006 to require a taxable person to lodge an ABST return for each tax period no later than fifteen (15) calendar days after the end of the period. The Act came into operation retroactively on 1 March 2024 and applies to the tax period ending 31 March 2024 and subsequent periods.
What changed in detail
The Antigua and Barbuda Sales Tax (Amendment) Act 2024 (No. 1 of 2024) amends the Antigua and Barbuda Sales Tax Act 2006 (No. 5 of 2006). It passed the House of Representatives on 22 February 2024 and the Senate on 1 March 2024, received the Governor-General’s assent on 2 April 2024 and was published in the Official Gazette Vol. XLIV No. 22 the same day.
The Act has one operative section. Section 3 repeals section 39(1) of the principal Act, which governs ABST returns, and replaces it in full with a single rule: a taxable person must lodge an ABST return for each tax period no later than fifteen (15) calendar days after the end of the period.
Section 1(2) brings the Act into operation on 1 March 2024, before the date of assent, and applies it to the tax period ending 31 March 2024 and every later tax period. The first return due under the new rule was therefore the March 2024 return, due by 15 April 2024.
The Act changes only the filing deadline. It does not touch the ABST rate, the tax period, or the payment and penalty provisions of the principal Act.
What it means
The 15-day deadline is still in force. The official alphabetical index of Acts on laws.gov.ag lists no later Sales Tax amendment after the 2024 Act, so section 39(1) stands as rewritten.
Because the rule is in calendar days, a period ending on 31 March closes on 15 April whatever the weekday; the new subsection writes in no weekend or holiday rollover. A monthly close has to produce the ABST figures within roughly two weeks of month end. The retroactive start date meant the March 2024 return was already caught when the Act was published on 2 April. The same year’s returns also fell under the 17% ABST rate set by Act No. 13 of 2023, which has no commencement clause of its own (Antigua and Barbuda raises the ABST rate to 17%).
Proof
(1) A taxable person must lodge an ABST return for each tax period no later than fifteen (15) calendar days after the end of the period.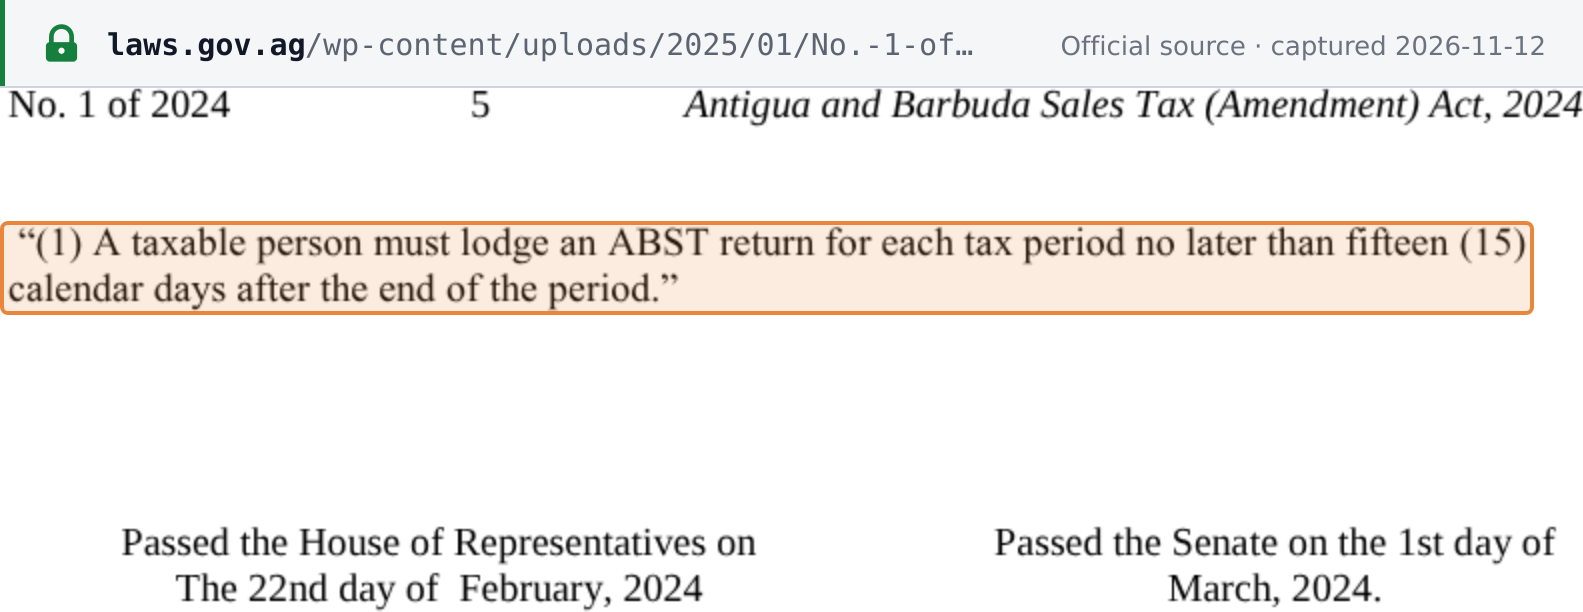 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Antigua and Barbuda Sales Tax (Amendment) Act 2024, No. 1 of 2024 (Official Gazette Vol. XLIV No. 22, 2 April 2024) · laws.gov.ag