Australia makes services funded under the Disability Services and Inclusion Act 2023 GST-free, backdated to 2024
This page records one dated change. For the rules in Australia as they stand today, see the Australia guide →
- Jurisdiction
- Australia
- Tax
- GST
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 4 December 2025
- Effective
- 1 January 2026
- Instrument
- AU-ACT-72-2025
- Authority
- Federal Register of Legislation, Australian Government
- Verified
- Fetched from official source · high confidence
Disability service providers that receive funding under the Disability Services and Inclusion Act 2023 or a complementary State or Territory law.
No action — monitoring only. Specialist disability service providers should confirm classification under the Disability Services and Inclusion Act 2023.
The Treasury Laws Amendment (Strengthening Financial Systems and Other Measures) Act 2025 (No. 72, 2025) received Royal Assent on 4 December 2025. Schedule 4, Part 2, commencing 1 January 2026, makes these GST changes. Division 1 adds s 38-40(2) to the GST Act 1999: a supply of services is GST-free if the supplier receives funding for those services under the Disability Services and Inclusion Act 2023 or a complementary State or Territory law. This applies to supplies made on or after 1 January 2024. Division 2 replaces s 29-10(4) with an election to attribute input tax credits not taken into account in an assessment to a later tax period (with a parallel rule for fuel tax credits). Division 3 amends attribution rules.
What changed in detail
The Treasury Laws Amendment (Strengthening Financial Systems and Other Measures) Act 2025 (No. 72, 2025) received Royal Assent on 4 December 2025. Under the commencement table in section 2, Schedule 4, Part 2 commences on 1 January 2026. It makes three groups of GST changes.
Division 1, specialist disability services, amends section 38-40 of the A New Tax System (Goods and Services Tax) Act 1999. The existing text becomes subsection (1), and its reference to the Disability Services Act 1986 now reads “former”. Item 34 adds a new subsection 38-40(2): a supply of services is GST-free if the supplier receives funding under the Disability Services and Inclusion Act 2023, or under a complementary State or Territory law, in respect of those services. Item 35 applies the new subsection to supplies made on or after 1 January 2024.
Division 2 replaces section 29-10(4) with an election to attribute input tax credits that were not taken into account in an assessment to a later tax period, with a parallel rule for fuel tax credits. Division 3 amends attribution rules.
What it means
The GST-free status of funded disability services had depended on a reference to the Disability Services Act 1986, which the Disability Services and Inclusion Act 2023 replaced. The amendment brings services funded under the 2023 Act into the exemption.
It is backdated. Although the subsection commenced on 1 January 2026, it applies to supplies from 1 January 2024. Providers that charged or remitted GST on such funded services in 2024 and 2025 may need to review those supplies and consider adjustments with the ATO. The provision is in force, and no later amendment has been identified.
Proof
A supply of services is GST-free if the supplier receives funding under the Disability Services and Inclusion Act 2023 or under a complementary *State law or *Territory law in respect of the services.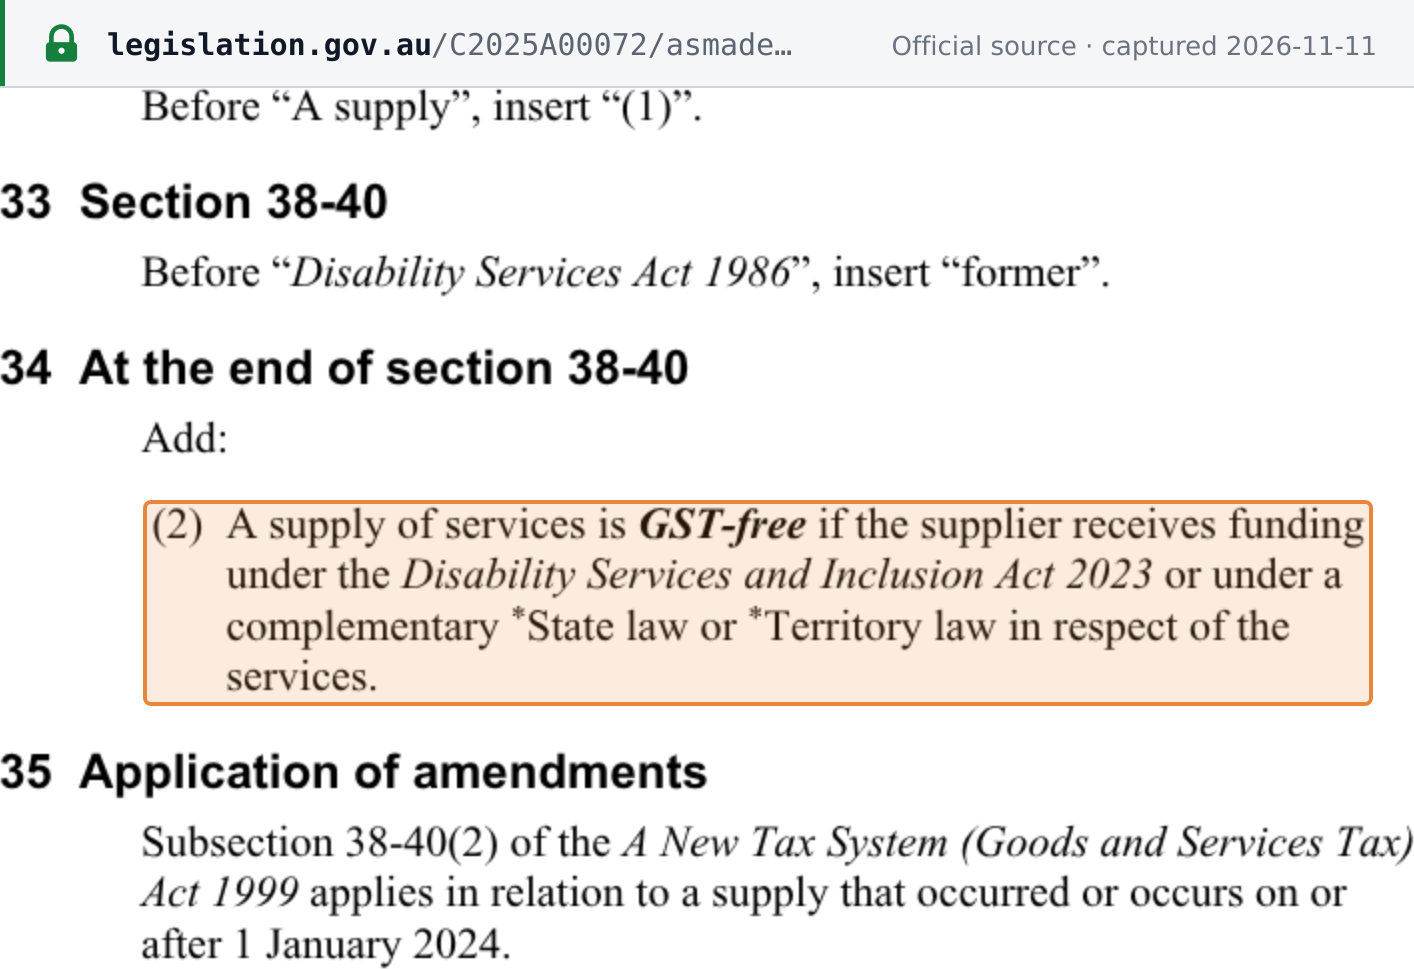 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Treasury Laws Amendment (Strengthening Financial Systems and Other Measures) Act 2025, No. 72, 2025 (Authorised Version C2025A00072 registered 05/12/2025) · www.legislation.gov.au