Austria requires payment service providers to report cross-border payments for CESOP from 1 January 2024
This page records one dated change. For the rules in Austria as they stand today, see the Austria guide →
- Jurisdiction
- Austria
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 1 January 2024
- Effective
- 1 January 2024
- Instrument
- AT-FEDERAL-LAW-BGBl-I-Nr-106-2023
- Authority
- Rechtsinformationssystem des Bundes (RIS)
- Verified
- Fetched from official source · high confidence
Payment service providers whose home or host Member State is Austria and that make more than 25 cross-border payments to the same payee in a calendar quarter.
Payment service providers in Austria must keep records of cross-border payments and transmit them quarterly to the tax authority via FinanzOnline when they make more than 25 cross-border payments to the same payee in a quarter; merchants receiving such payments need not act, but their payment data reaches the EU CESOP database.
The CESOP-Umsetzungsgesetz 2023 (BGBl. I Nr. 106/2023, published 21 July 2023) inserted § 18a into the Umsatzsteuergesetz 1994, requiring payment service providers (PSPs) to record and transmit detailed data on cross-border payments, where they make more than 25 cross-border payments to the same payee in a calendar quarter, to the Austrian tax authority for forwarding to the EU CESOP central system. In force from 1 January 2024 (§ 28 Abs. 61 UStG 1994).
What changed in detail
The CESOP-Umsetzungsgesetz 2023, published on 21 July 2023 as BGBl. I Nr. 106/2023, transposed the EU payment-data rules (Directive (EU) 2020/284) into Austrian law. Article 1 inserted § 18a into the Umsatzsteuergesetz 1994, and § 28 Abs. 61 put it in force on 1 January 2024.
§ 18a applies to payment service providers whose home or host Member State is Austria. For each calendar quarter they must keep, retain and transmit records of cross-border payments and their payees:
- Threshold. The duty applies only where a provider makes more than 25 cross-border payments to the same payee in a calendar quarter, counted per Member State and per payee identifier (Abs. 5).
- Payer-side exception. The payer’s provider does not report a payment where at least one of the payee’s providers is located in a Member State, although it still counts those payments towards the threshold (Abs. 6).
- Content. The records include the payee’s name, any VAT or tax number, IBAN or other identifier, address where held, and the date, amount, currency and origin of each payment and refund (Abs. 7).
- Deadlines. Data is transmitted electronically by the end of the month after the quarter, errors are corrected within one month of discovery, and records are kept for three calendar years (Abs. 8).
Article 3 added § 49e to the Finanzstrafgesetz: intentional breaches carry a fine of up to EUR 50,000, grossly negligent ones up to EUR 25,000. The transmission format is set by BGBl. II Nr. 265/2023.
What it means
The reporting duty is still in force. No later federal law has amended § 18a; the 2026 UStG amendments (BGBl. I Nr. 37/2026, 43/2026 and 62/2026) left it untouched. The first transmission, for the first quarter of 2024, was due by 30 April 2024.
The duty sits with banks and payment institutions, not with merchants. Merchants who receive many card or transfer payments from other Member States file nothing extra, but their payment data now reaches the EU’s CESOP database, where tax authorities can compare it with what the merchant declared, for example under the One-Stop Shop.
Proof
Zahlungsdienstleister sind verpflichtet in Bezug auf grenzüberschreitende Zahlungen hinreichend detaillierte Aufzeichnungen über Zahlungsempfänger und Zahlungen in Bezug auf die von ihnen in jedem Kalendervierteljahr erbrachten Zahlungsdienste zu führen, aufzubewahren und zu übermitteln.Payment service providers are required to keep, retain and transmit sufficiently detailed records of payees and payments in respect of the payment services they provide in each calendar quarter concerning cross-border payments.
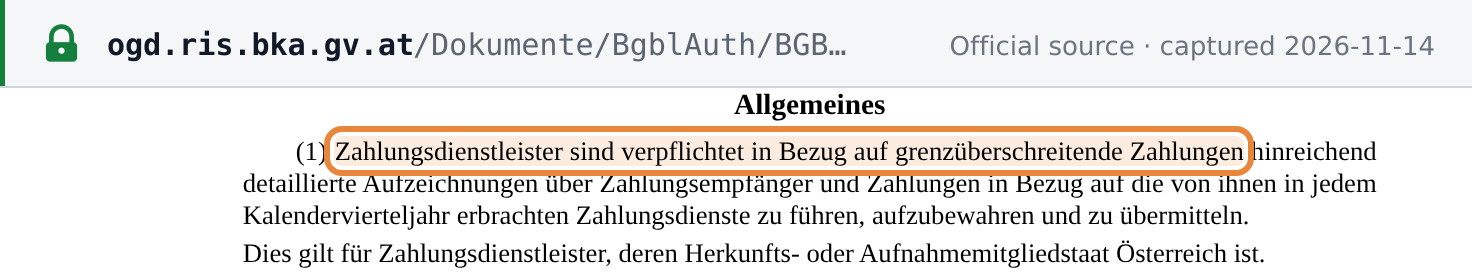 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BGBl. I Nr. 106/2023 (CESOP-Umsetzungsgesetz 2023), ausgegeben am 21. Juli 2023, Artikel 1 (§ 18a UStG 1994) · ogd.ris.bka.gv.at