Belarus extends VAT registration for foreign e-services and distance sellers to all foreign-state taxpayers from 1 January 2025
- Jurisdiction
- Belarus
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 13 December 2024
- Effective
- 1 January 2025
- Instrument
- BY-LAW-47
- Authority
- Министерство по налогам и сборам Республики Беларусь (Ministry of Taxes and Duties)
- Verified
- Fetched from official source · high confidence
Non-resident persons taxable under a foreign state’s law (beyond foreign organisations and entrepreneurs) supplying electronic services or distance sales to individuals in Belarus above EUR 10,000 a year.
No action — monitoring only.
Law No. 47-Z of 13 December 2024 (amending the Tax Code) extended Belarus VAT registration obligations from 1 January 2025 to 'other foreign taxpayers' — persons who are taxpayers under the legislation of a foreign state — providing electronic services or making electronic distance sales to individuals in Belarus, in addition to the previously covered foreign organisations and individual entrepreneurs. The existing EUR 10,000 annual-turnover registration threshold continues to apply.
What changed in detail
Law No. 47-Z of 13 December 2024 “Об изменении законов”, published on the National Legal Internet Portal on 20 December 2024, amends the Belarus Tax Code. From 1 January 2025 it inserts “иные лица, являющиеся налогоплательщиками в соответствии с законодательством иностранного государства” (other persons who are taxpayers under the legislation of a foreign state) into:
- article 141(1), which covers electronic services supplied to individuals in Belarus; and
- article 141-1(1), which covers electronic distance sales of goods to individuals in Belarus.
Before this, the VAT registration duty applied only to foreign organisations and foreign individual entrepreneurs. Foreign organisations supplying electronic services have had to register since 1 January 2018; from 1 July 2022 the duty was extended to foreign individual entrepreneurs and to electronic distance sales of goods. The widened scope captures foreign-taxable persons that fit neither category.
The registration conditions are unchanged. A non-resident must register with the Belarus tax authority and pay VAT when it supplies electronic services or distance sales to buyers in Belarus and its turnover from those supplies in the current calendar year exceeds the equivalent of EUR 10,000. Once registered, it calculates and pays VAT quarterly regardless of the turnover in the period.
What it means
The extension has applied since 1 January 2025 and remains in force; the Ministry of Taxes and Duties’ e-VAT page still states it, and no later change recorded here alters the scope or the EUR 10,000 threshold.
The practical effect is to close a gap in who counts as a supplier rather than to change the tax itself. A non-resident seller that had concluded it was outside the regime because it was neither an organisation nor an individual entrepreneur under Belarusian definitions should reassess: if it is a taxpayer in its home country and crosses the threshold, it now has to register.
Proof
С 1 января 2025 г. постановке на учет в качестве плательщика налога на добавленную стоимость также подлежат: • иные лица, являющиеся налогоплательщиками в соответствии с законодательством иностранного государства, оказывающие услуги в электронной форме физическим лицам (включая индивидуальных предпринимателей), находящимся в Республике БеларусьFrom 1 January 2025, the following persons are also required to register as VAT taxpayers: other persons who are taxpayers under the legislation of a foreign state and who provide electronic services to individuals (including individual entrepreneurs) located in the Republic of Belarus
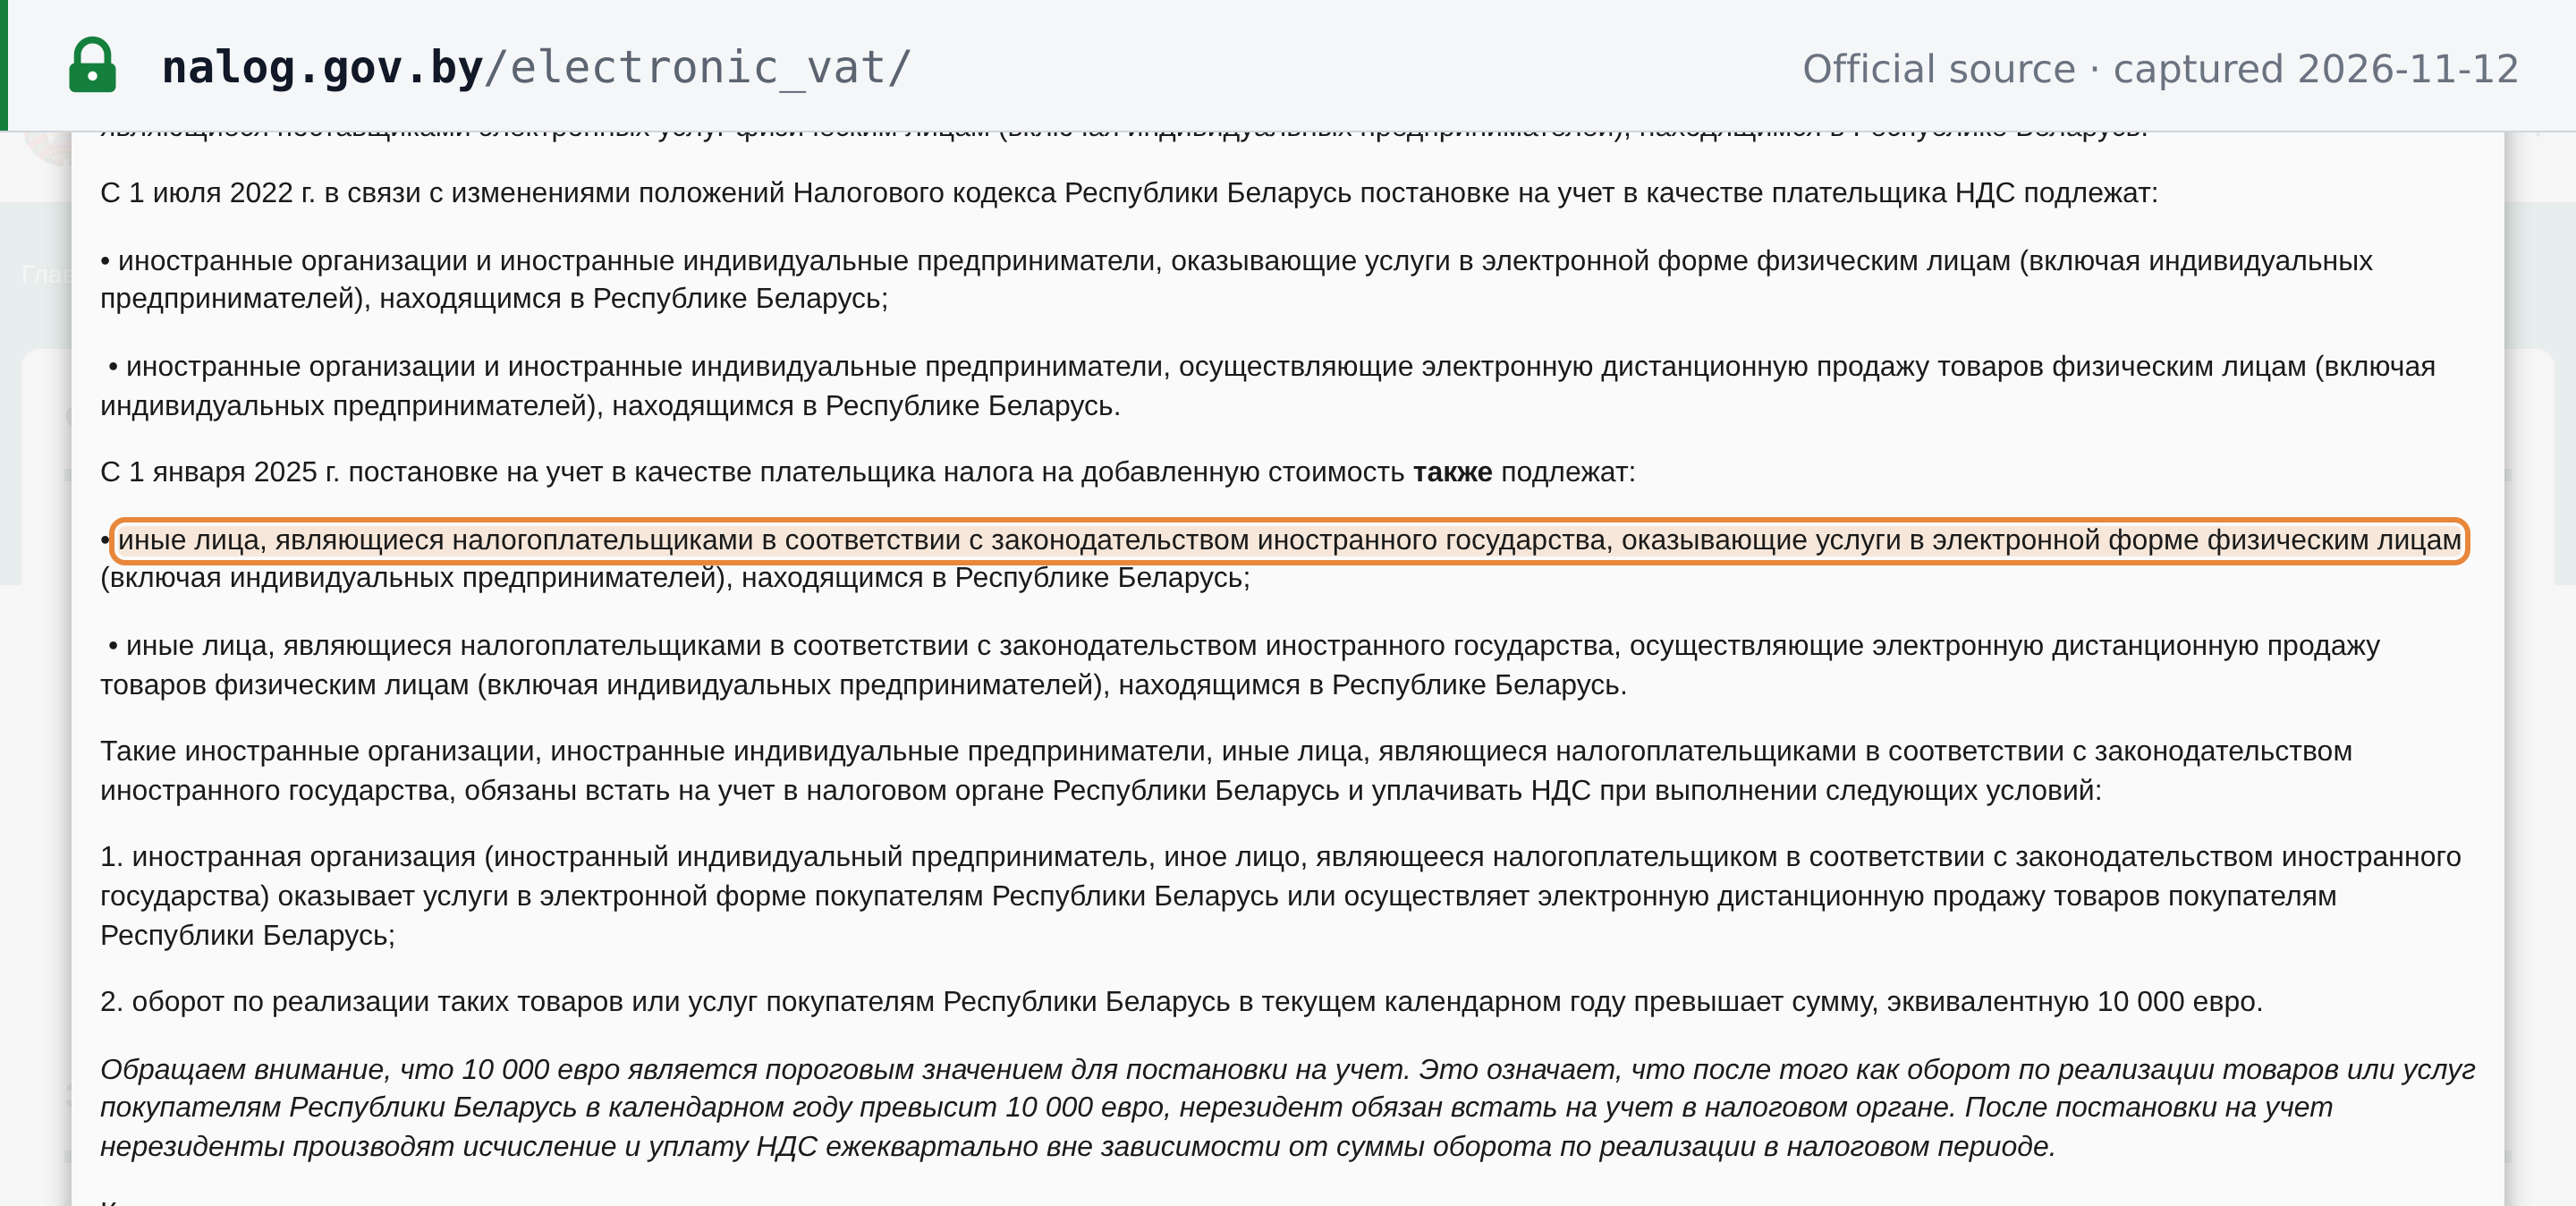 Source snapshot of the official page. Open full size ↗