Belgium makes online marketplaces jointly liable for sellers' VAT on goods from 1 January 2024
This page records one dated change. For the rules in Belgium as they stand today, see the Belgium guide →
- Jurisdiction
- Belgium
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 1 December 2023
- Effective
- 1 January 2024
- Instrument
- BE-ACT-2023047474
- Authority
- SPF Finances (FPS Finance), Belgium
- Verified
- Fetched from official source · high confidence
Operators of marketplaces, platforms and portals that facilitate supplies of goods taking place in Belgium, for sales not covered by the EU deemed-supplier rules.
Marketplaces and platforms facilitating supplies of goods in Belgium should check each seller's VAT number before onboarding and at least once a year, and act within one month of any SPF Finances notice of serious suspicion (warn the seller twice, exclude it after the third notice) to avoid joint liability for the seller's VAT.
The Law of 23 November 2023 on miscellaneous VAT provisions (Moniteur belge 1 December 2023, Numac 2023047474), art. 17, 2°, inserts art. 51bis, §3bis into the VAT Code, applicable to VAT chargeable from 1 January 2024. A taxable person that facilitates supplies of goods taking place in Belgium through an electronic interface (marketplace, platform, portal or similar) is jointly and severally liable with the supplier for the VAT on those supplies when it is not in good faith or has committed a fault or negligence. It covers Belgian domestic supplies and intra-EU distance sales outside the deemed-supplier rules, and distance sales of imported goods in consignments above EUR 150. The platform is deemed negligent if it does not check, before facilitating and at least once each calendar year, that the supplier holds a valid VAT number. It is deemed not in good faith if, within one month of each of the administration's first two notices of serious suspicion, it does not put the supplier on notice, or if it does not exclude the supplier within one month of the third notice.
What changed in detail
Article 17, 2° of the Law of 23 November 2023 on miscellaneous VAT provisions (Moniteur belge 1 December 2023, Numac 2023047474) inserts a new §3bis into article 51bis of the Belgian VAT Code. Under article 18 of the law it applies to VAT that becomes chargeable from 1 January 2024.
A taxable person that facilitates supplies of goods taking place in Belgium through an electronic interface (a marketplace, platform, portal or similar means) is jointly and severally liable with the supplier for the VAT on those supplies. The liability arises only where the platform is not in good faith or has committed a fault or negligence. It covers:
- supplies within Belgium, supplies without transport and intra-EU distance sales listed in §3bis, 1°, outside the deemed-supplier rules;
- distance sales of goods imported from outside the EU in consignments with an intrinsic value above EUR 150, where the supplier is the importer.
The platform is deemed negligent if it did not check, before it began facilitating and at least once each calendar year, that the supplier holds a valid VAT number. It is deemed not in good faith if it does not warn the supplier within one month of each of the administration’s first two notices of serious suspicion, or does not exclude the supplier within one month of the third.
What it means
The rule is still in force as enacted. The consolidated text of article 51bis shows no amendment to §3bis since 2024. The ViDA law of 25 October 2026 changes other articles of the Code and leaves this paragraph untouched.
In practice the defence is procedural. A platform that verifies each seller’s VAT number at onboarding and once a year, and acts within one month on every SPF Finances notice, keeps the good-faith protection. A platform that misses one of those steps is presumed at fault and can be pursued for the seller’s unpaid VAT. Keep dated records of each check and each notice handled, because the platform carries the burden of showing it met them.
Proof
est solidairement tenu au paiement de la taxe due sur ces livraisons envers l’État avec le fournisseur qui en est redevable en vertu de l’article 51, § 1er, 1°, lorsqu’il n’est pas de bonne foi ou lorsqu’il a commis une faute ou une négligenceis jointly and severally liable to the State for payment of the tax due on those supplies with the supplier liable for it under Article 51, §1, 1°, where it is not in good faith or has committed a fault or negligence
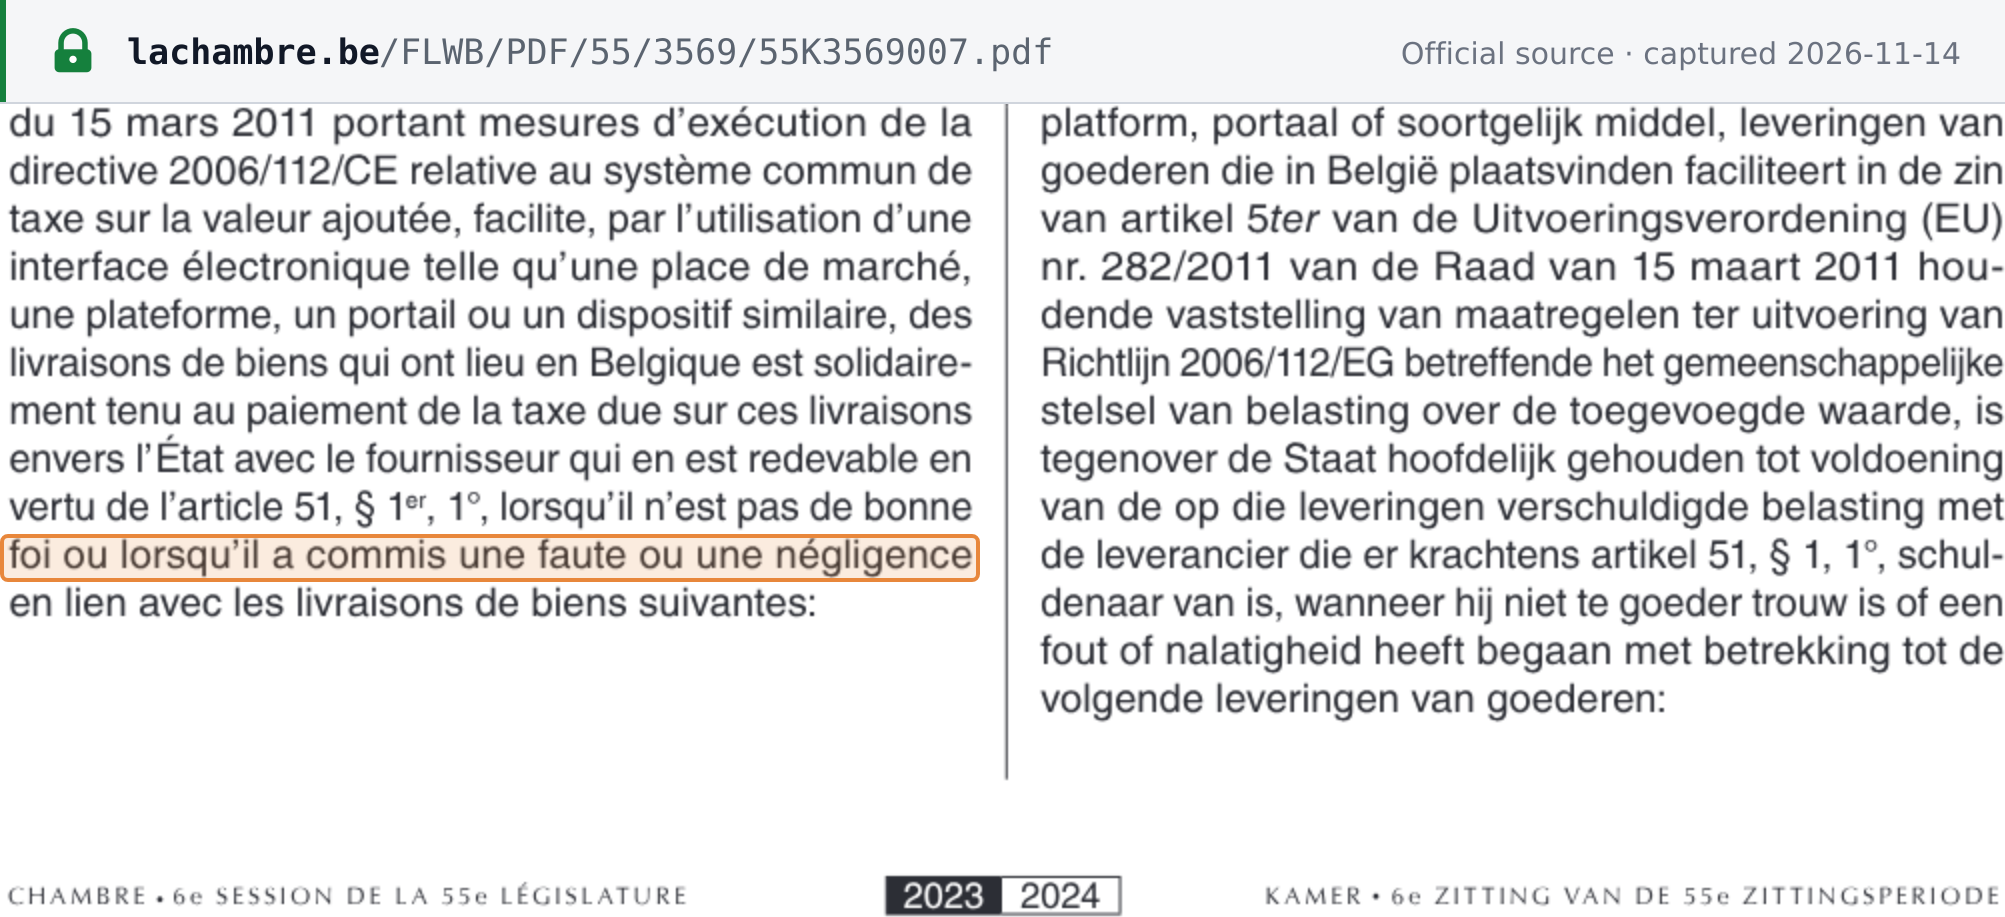 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Chambre des représentants, DOC 55 3569/007 (texte adopté en deuxième lecture; adopté tel quel en séance plénière, DOC 55 3569/008) · www.lachambre.be
est solidairement tenu au paiement de la taxe due sur ces livraisons envers l'Etat avec le fournisseur qui en est redevable en vertu de l'article 51, § 1er, 1°, lorsqu'il n'est pas de bonne foi ou lorsqu'il a commis une faute ou une négligenceis jointly and severally liable to the State for payment of the tax due on those supplies with the supplier liable for it under Article 51, §1, 1°, where it is not in good faith or has committed a fault or negligence
Archived from the official distribution · Fisconetplus 9f826f65-e0b8-4273-abf6-998844ee48ef: Article 51bis, Code de la TVA (texte actuel et historique) · www.minfin.fgov.be