Belize writes electronic invoicing into the GST Act: e-invoices must be authorised by the Tax Administration from 1 January 2025
This page records one dated change. For the rules in Belize as they stand today, see the Belize guide →
- Jurisdiction
- Belize
- Tax
- GST
- Change type
- E-invoicing
- Status
- In force
- Impact
- Action required
- Announced
- 14 December 2024
- Effective
- 1 January 2025
- Instrument
- BZ-STATUTE-34-of-2024
- Authority
- Belize Tax Service
- Verified
- Fetched from official source · high confidence
All GST-registered persons in Belize that issue tax invoices, tax receipts, credit notes or debit notes.
Taxable persons must ensure electronic invoices are authorised by the Tax Administration and comply with technical standards published by the Commissioner.
The General Sales Tax (Amendment) Act, 2024 (No. 34 of 2024), assented by the Governor-General on 9 December 2024 and gazetted on 14 December 2024, in force 1 January 2025, established the legal basis for electronic invoicing under the GST. It amended section 36 of the General Sales Tax Act to allow invoices to be issued electronically or in printed form, provided that electronic invoices are identified as such, required all electronic invoices and other electronic tax documents to be authorised by the Tax Administration for validity and tax recognition, authorised the Commissioner to prescribe technical specifications and procedures for e-invoices and to set mandatory e-issuing dates, and introduced a new section 36A for tax receipts. The Act also extended the record-retention period from 6 months to one year.
What changed in detail
The General Sales Tax (Amendment) Act, 2024 (No. 34 of 2024) amends the General Sales Tax Act, Chapter 63. The Governor-General assented on 9 December 2024, it was gazetted on 14 December 2024, and section 14 brings it into force on 1 January 2025. Its long title says it is to enable electronic tax invoicing.
- Section 2 defines an invoice to include one issued, transmitted and received in a structured data format that allows automatic electronic processing.
- Section 6 amends section 36. Tax invoices may be issued electronically or in printed form; an electronic one must be identified as an electronic tax invoice. New subsection (4A) has the Commissioner prescribe how a recipient accesses the electronic record. New subsection (7) requires every electronic invoice and other electronic tax document to be authorised by the Tax Administration for validity and tax recognition. Subsection (8) has the Commissioner publish the technical specifications, and subsection (9) has the Commissioner set the dates by which all invoices and tax documents must be issued electronically.
- Section 7 inserts section 36A, a tax receipt for supplies to a taxable person or final consumer, with six mandatory particulars.
- Section 8 lets credit and debit notes be electronic and requires them to quote the invoice number.
- Section 5 extends the section 33(3) record period from 6 months to one year.
- Section 12 adds a regulation-making power for the electronic tax document regime.
What it means
The Act is in force and is the legal basis for Belize’s e-invoicing system. It sets no mandatory date itself; it leaves the timetable to the Commissioner. The Belize Tax Service has since published the technical rules the Act calls for, an orientation manual for issuers of electronic tax documents (version 1.30, May 2026), under which invoices and credit and debit notes are authorised before issue in normal operation.
For a business, the practical point is that an electronic invoice the Tax Administration has not authorised has no tax recognition; until electronic issue is compulsory, the printed tax invoice remains a valid alternative. Watch for the Commissioner’s dates under section 36(9), which end that choice.
Proof
(7) All electronic invoices and other electronic tax documents shall be authorized by the Tax Administration for their validity and tax recognition, in accordance with the regulations and technical standards issued for this purpose.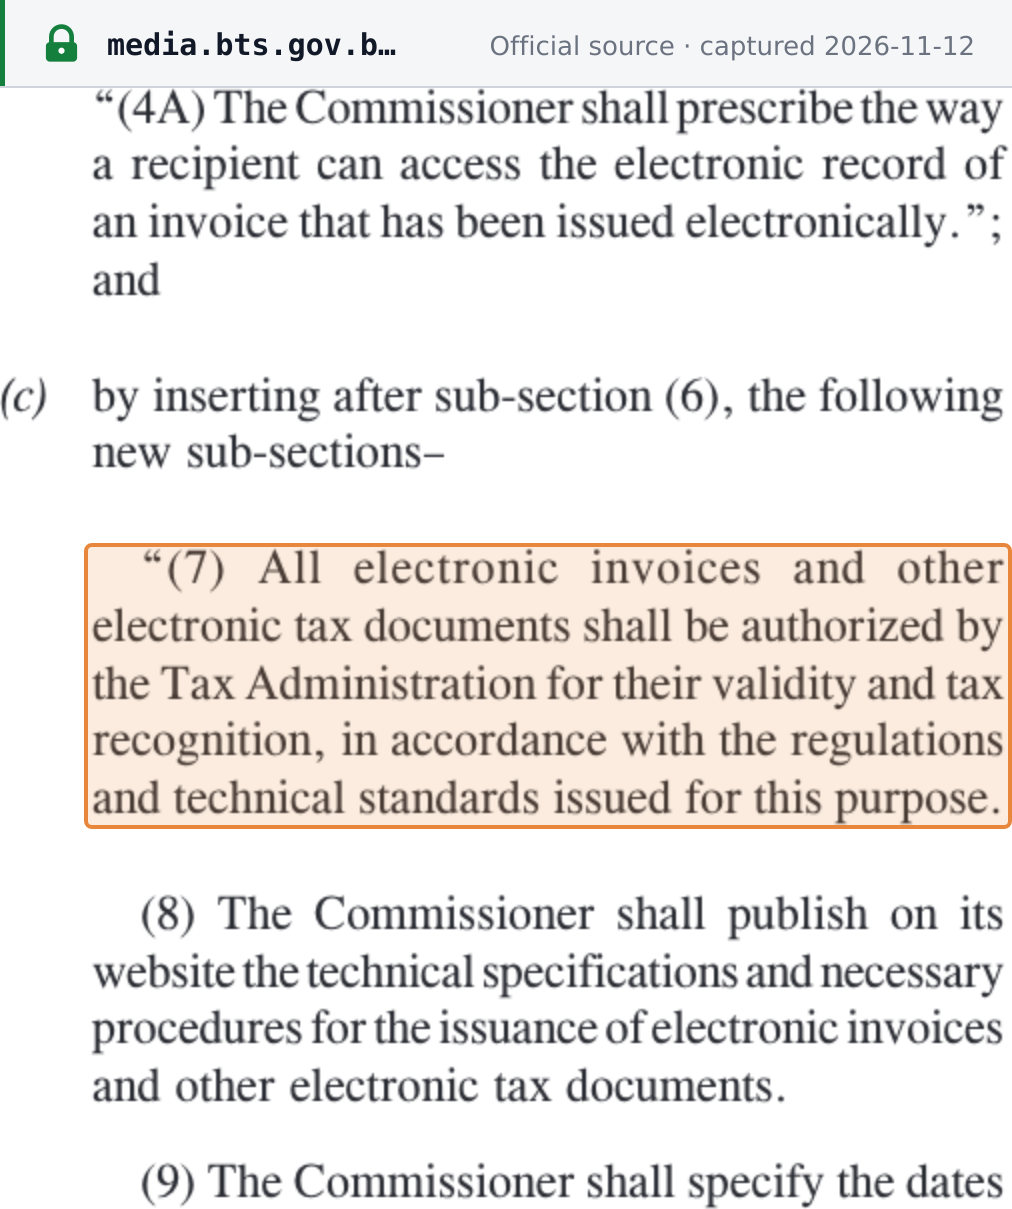 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · General Sales Tax (Amendment) Act, 2024, No. 34 of 2024 (assented 9 December 2024; gazetted 14 December 2024) · media.bts.gov.bz