Brazil enacts Lei Complementar 214/2025, instituting the IBS, CBS and Imposto Seletivo
This page records one dated change. For the rules in Brazil as they stand today, see the Brazil guide →
- Jurisdiction
- Brazil
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 16 January 2025
- Effective
- 1 January 2026
- Instrument
- BR-COMPLEMENTARY-LAW-214-2025
- Authority
- Imprensa Nacional — Diário Oficial da União
- Verified
- Fetched from official source · high confidence
All suppliers of goods and services in Brazil, and digital platforms, including foreign ones, through which operations and imports are made.
Review CBS/IBS registration and transaction-level tax codes for the 2026 test year (CBS 0.9%, IBS 0.1%); digital platforms must assess their responsibility under art. 22. Monitor LC 227/2026 amendments and CGIBS regulations.
Lei Complementar nº 214, de 16 de janeiro de 2025, published in the Diário Oficial da União (Edição Extra nº 11-B) on 16 January 2025, implements the consumption-tax reform mandated by EC 132/2023. It institutes the IBS (shared state/municipal tax), the CBS (federal contribution) and the IS (selective tax), creates the Comitê Gestor do IBS, and makes digital platforms, including foreign ones, responsible for IBS/CBS on operations and imports made through them (art. 22). For taxable events from 1 January to 31 December 2026, IBS is charged at 0.1% (art. 343) and CBS at 0.9% (art. 346), offsettable against PIS/COFINS (art. 348). The law was sanctioned with partial vetoes (Mensagem de Veto nº 88/2025), some later rejected by Congress, and was amended by LC 227/2026 (13 January 2026).
What changed in detail
Lei Complementar nº 214, de 16 de janeiro de 2025, published in the Diário Oficial da União (Edição Extra nº 11-B) on 16 January 2025, implements the consumption-tax reform mandated by Emenda Constitucional 132/2023.
It:
- institutes the Imposto sobre Bens e Serviços (IBS), the shared state and municipal tax; the Contribuição Social sobre Bens e Serviços (CBS), the federal contribution; and the Imposto Seletivo (IS);
- creates the Comitê Gestor do IBS;
- makes digital platforms, including foreign ones, responsible for IBS and CBS on operations and imports made through them, in the cases listed in art. 22.
For taxable events from 1 January to 31 December 2026, the IBS is charged at a state rate of 0.1% (art. 343) and the CBS at 0.9% (art. 346), offsettable against PIS and COFINS (art. 348).
The law was sanctioned with partial vetoes (Mensagem de Veto nº 88/2025), some of which Congress later rejected. It was amended by Lei Complementar 227/2026 of 13 January 2026.
What it means
LC 214 is the operative law of Brazil’s reform and is in force, though not in its original text: vetoes overturned by Congress and LC 227/2026 changed it, so cite the consolidated version, not the January 2025 publication. The 2026 rates are test rates that sit on the fiscal document and are offset against PIS/COFINS (br-dual-vat-pilot-test-rate-2026); real CBS collection starts in 2027 under the transition EC 132 set. For platforms, art. 22 is the provision to plan around, but its conditions changed. Art. 22(I) still makes the platform answer for IBS and CBS where the supplier is resident abroad. For Brazil-resident suppliers, LC 227/2026 rewrote art. 22(II) and added a § 5: the platform is jointly liable only if it fails to provide the information § 5 requires, or if the supplier is a taxpayer and issues no electronic invoice for the operation.
Proof
Art. 346. Em relação aos fatos geradores ocorridos de 1º de janeiro a 31 de dezembro de 2026, a CBS será cobrada mediante aplicação da alíquota de 0,9% (nove décimos por cento).Art. 346. For taxable events occurring from 1 January to 31 December 2026, CBS shall be charged at the rate of 0.9% (nine tenths of one percent).
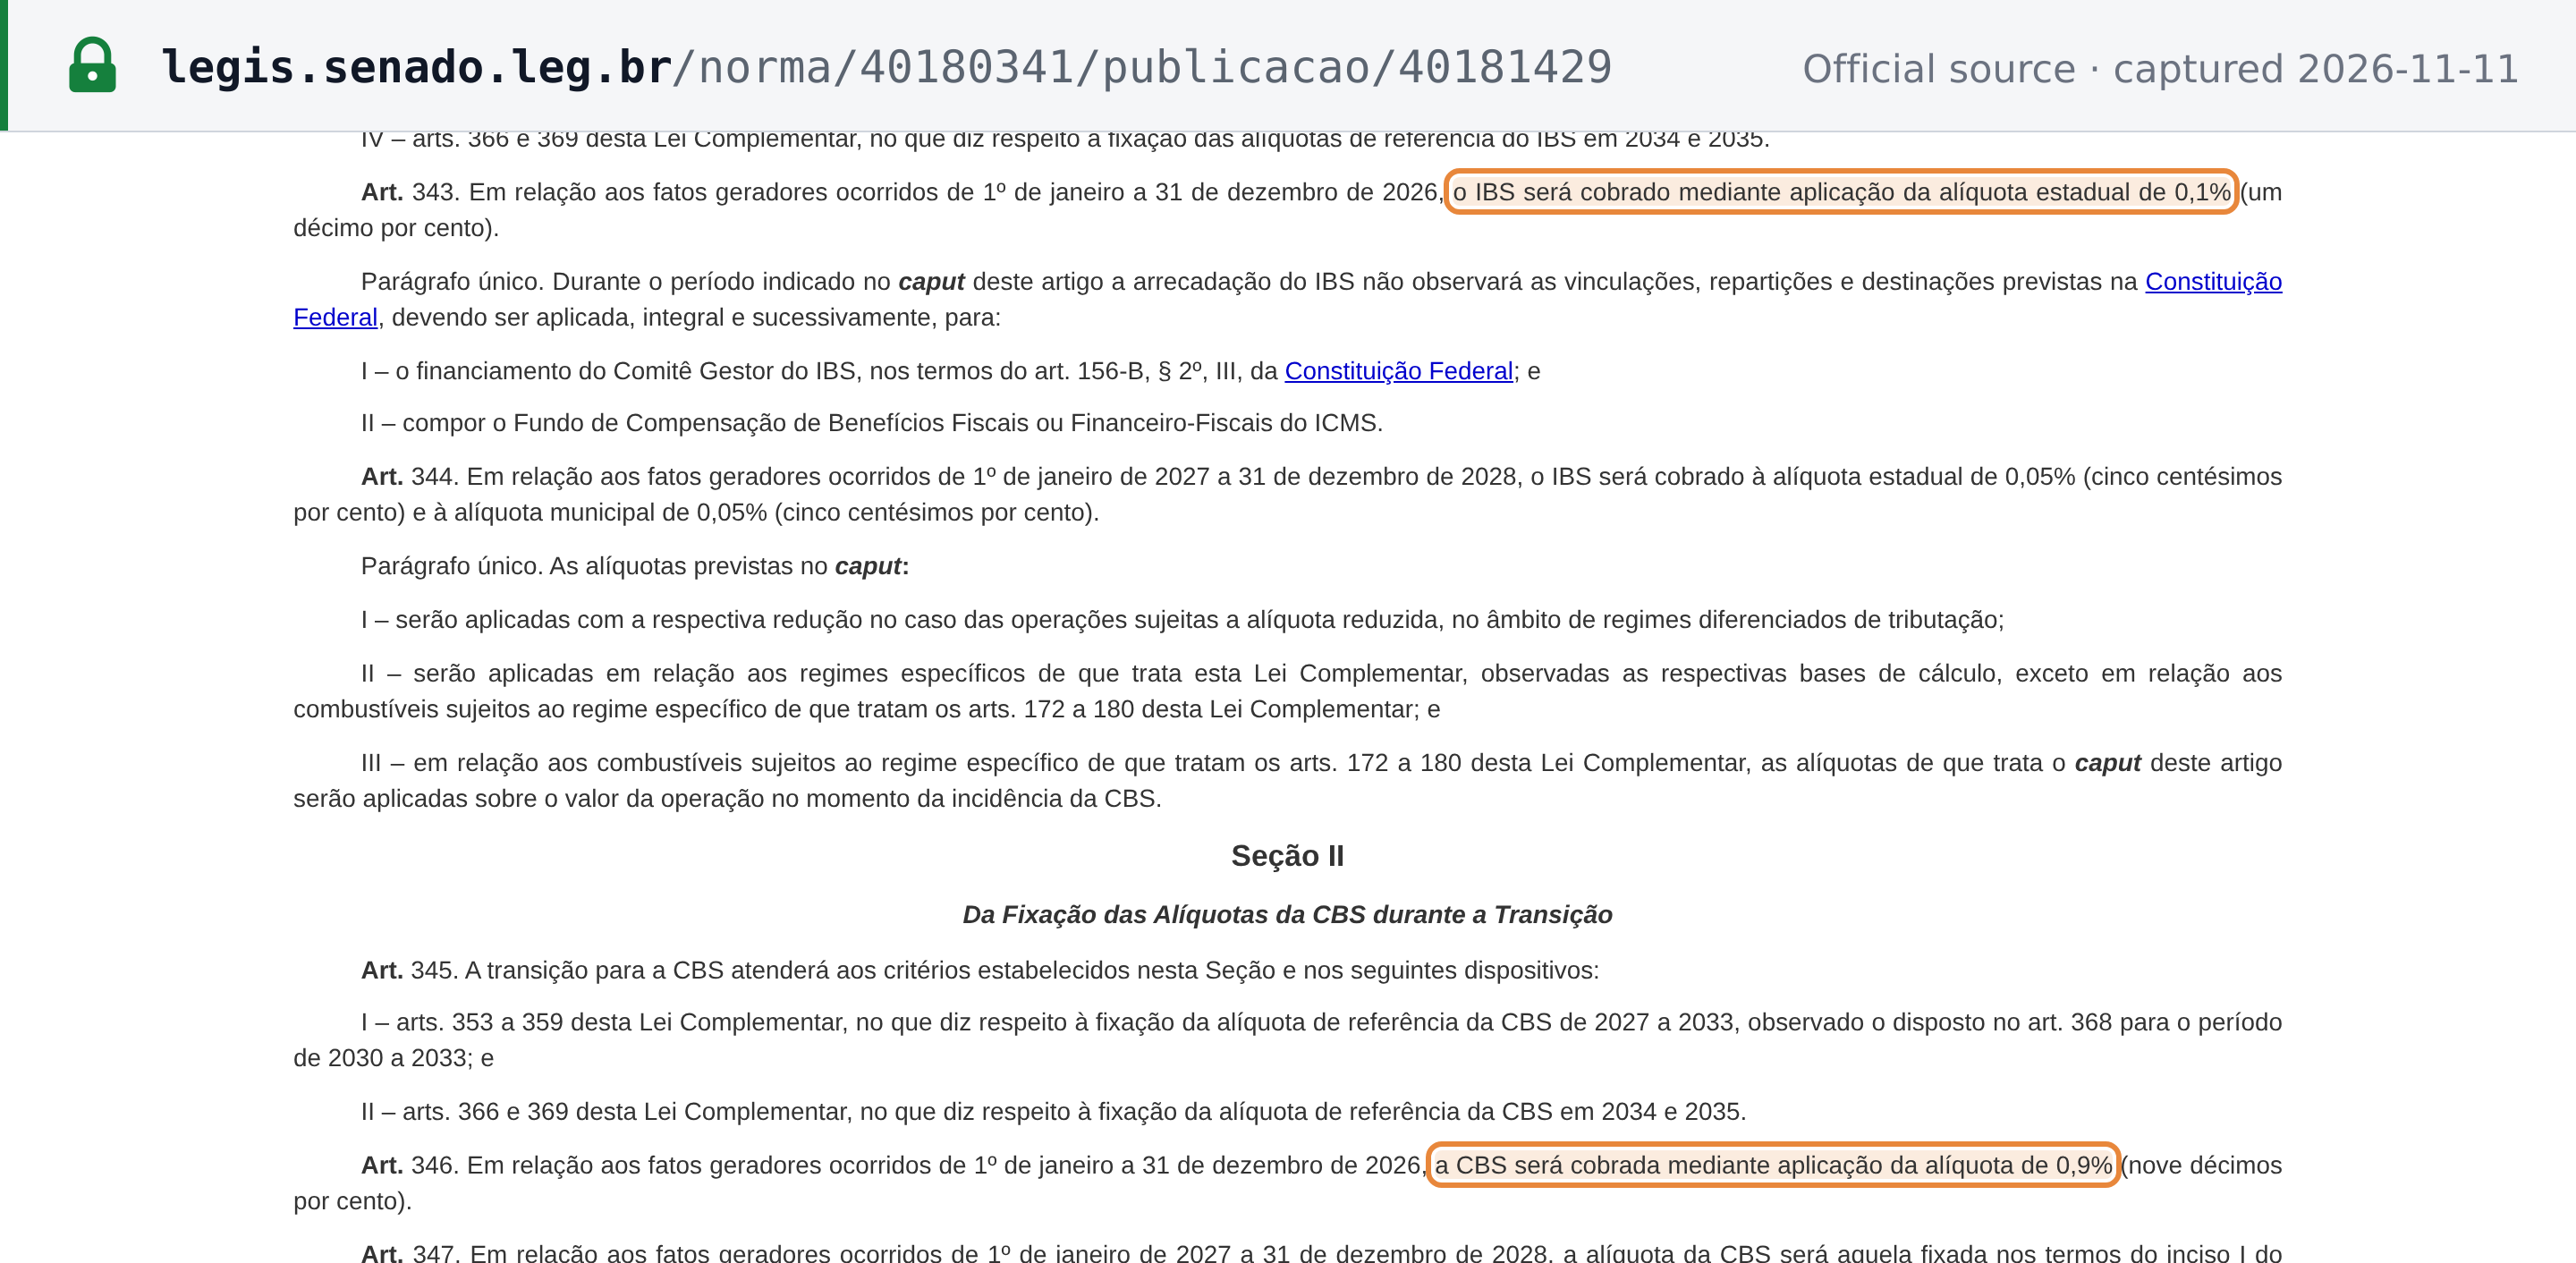 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Lei Complementar nº 214, de 16 de janeiro de 2025 — Senado Federal, Legislação (publicação) · legis.senado.leg.br