Burkina Faso brings e-commerce platform sales into TVA and makes platform operators collect it from 1 January 2025
- Jurisdiction
- Burkina Faso
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 23 December 2024
- Effective
- 1 January 2025
- Instrument
- BF-FINANCE-LAW-042-2024-ALT
- Authority
- Assemblée Législative de Transition du Burkina Faso
- Verified
- Fetched from official source · high confidence
Operators of foreign or local e-commerce platforms through which goods and services are sold in Burkina Faso, and the suppliers selling through them.
No action — monitoring only.
Loi n°042-2024/ALT, the 2025 Finance Law adopted by the Assemblée Législative de Transition on 23 December 2024 (Arts. 26 and 35, effective 1 January 2025), brought sales of goods and services made in Burkina Faso through foreign or domestic e-commerce platforms, and the commissions platform operators earn on them, within the scope of TVA (new CGI art. 299 point 4). Platform operators must liquidate, declare and remit the TVA on those sales on behalf of the suppliers, declare and remit the TVA on their own commissions, and register with the tax administration (new CGI art. 334 point 5); non-compliance can lead to suspension of access to the platform from Burkinabè territory. Implementing details are left to an order (arrêté) of the finance minister.
What changed in detail
Loi n°042-2024/ALT, Burkina Faso’s Finance Law for 2025, was adopted by the Assemblée Législative de Transition on 23 December 2024 and takes effect from 1 January 2025 (art. 89). Two of its articles create a TVA regime for e-commerce platforms.
Article 26 rewrites article 299 of the General Tax Code and adds a new point 4): sales of goods and services made in Burkina Faso through foreign or local e-commerce platforms, including the commissions platform operators earn on them, are within the scope of TVA.
Article 35 adds a paragraph 5) to article 334:
- a) platform operators liquidate, declare and remit the TVA due on those sales on behalf of the suppliers, and declare and remit the TVA on their own commissions;
- b) operators must register with the tax administration, and may register, file and pay online through its portal;
- c) failing those obligations can lead to suspension of access to the platform from Burkinabè territory, on top of the code’s other penalties;
- d) the implementing details are left to an order (arrêté) of the finance minister.
What it means
The regime has been law since 1 January 2025 and we have found no later amendment to it. It shifts collection from the supplier to the platform, so a marketplace serving Burkinabè customers is responsible for the TVA on its sellers’ sales, not only on its own commission.
The access-suspension sanction is the enforcement lever against foreign platforms with no local presence. How the obligations work in practice depends on the finance minister’s implementing order, which this law left to follow.
Proof
4) Les ventes de biens et les prestations de services effectuées sur le territoire burkinabè à travers les plateformes de commerce électronique étrangères ou locales, y compris les commissions perçues par les opérateurs de plateformes de commerce en ligne à l’occasion de ces opérations.4) The sale of goods and provision of services made on Burkinabè territory through foreign or domestic e-commerce platforms, including commissions received by online commerce platform operators on the occasion of these transactions.
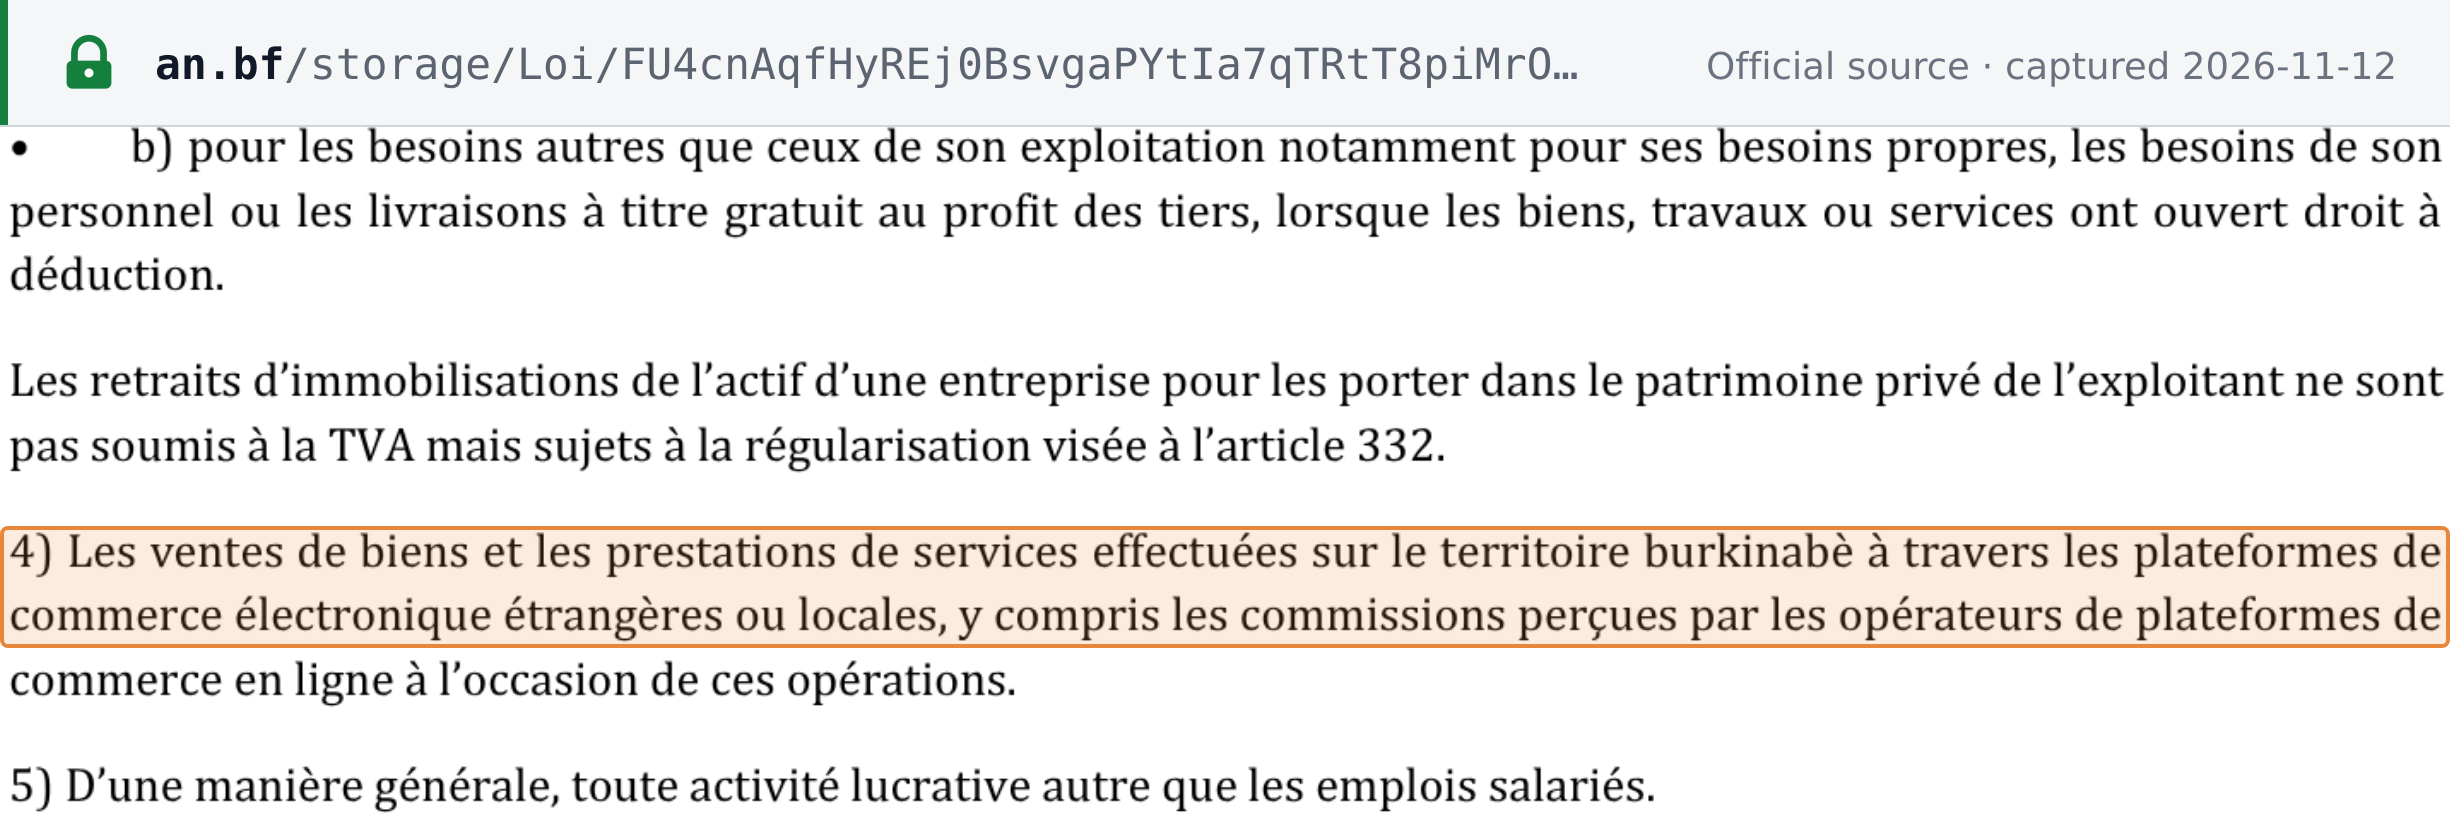 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Loi n°042-2024/ALT portant loi de finances pour l'exercice 2025 (adoptée le 23 décembre 2024) · an.bf