Cameroon makes VAT on goods due when an advance payment is received
- Jurisdiction
- Cameroon
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 17 December 2025
- Effective
- 1 January 2026
- Instrument
- CM-FINANCE-LAW-2025-012
- Authority
- Direction Générale des Impôts, Cameroun
- Verified
- Fetched from official source · high confidence
VAT-registered suppliers of goods in Cameroon that receive advance payments or deposits before delivery.
No action — monitoring only.
Finance Law 2026 (Law No. 2025/012 of 17 December 2025, Section 23) amended Section 134(1)(a) of Cameroon's General Tax Code. VAT on supplies of goods remains due when the chargeable event (delivery) occurs, but when an advance payment is received before delivery, VAT is now due on receipt, up to the amount received. This aligns goods with the existing rule for services. Suppliers must issue an advance-payment invoice showing the VAT separately. Applies from 1 January 2026.
What changed in detail
Section 23 of Cameroon’s Finance Law for 2026 (Law No. 2025/012 of 17 December 2025) amends Section 134(1)(a) of the General Tax Code, which fixes when VAT becomes payable (exigibilité).
Before the change, VAT on supplies of goods was payable when the chargeable event took place, that is, on delivery, even if the customer had paid part of the price earlier. For services, VAT was already payable on receipt of payment, including advances.
The amended text keeps the general rule for goods but adds: “However, in case of an advance payment, the tax shall be payable at the time of receipt, up to the amount received.” The rest of Section 134 is unchanged.
The DGI circular published in the same official edition of the tax code explains that the change aligns goods with services and that suppliers must issue an advance-payment invoice showing the VAT separately.
The amendment applies with the 2026 financial year, from 1 January 2026.
What it means
The rule is in force for 2026 and no later instrument recorded here changes it. Suppliers that take deposits, such as on vehicles, equipment or construction materials, now declare VAT in the month the deposit arrives rather than the month of delivery, so their billing and VAT return processes need to capture advances as taxable events.
The balance remains taxable on delivery. If an order is cancelled after a deposit is taxed, the supplier needs the general correction rules to recover the VAT already paid.
Proof
a. on supplies of goods when the chargeable event takes place. However, in case of an advance payment, the tax shall be payable at the time of receipt, up to the amount received.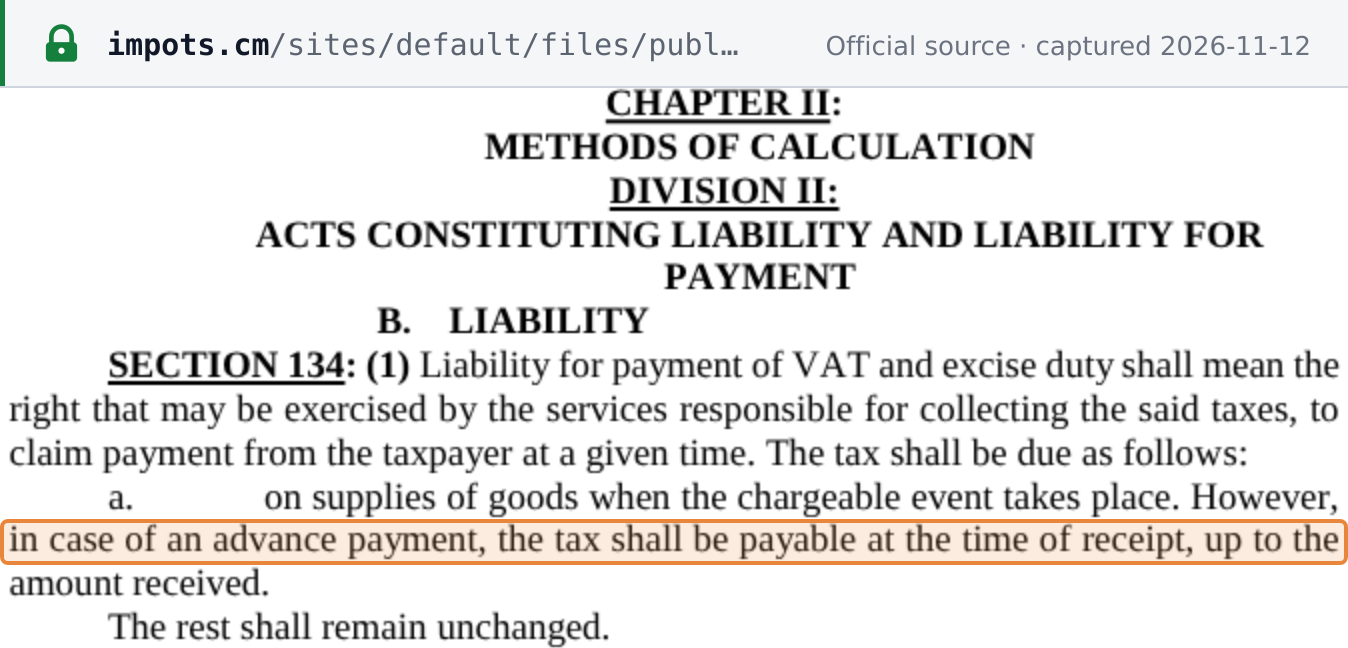 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · General Tax Code, Official Edition 1 January 2026 (DGI Cameroon), reproducing Law No. 2025/012 of 17 December 2025, Finance Law for 2026 · www.impots.cm