Canada Budget 2026 proposes GST/HST exemption for massage therapy and zero-rating for cancer-treatment devices — not yet law
This change is proposed and is not law. The rules below describe what would change if it is adopted.
This page records one dated change. For the rules in Canada as they stand today, see the Canada guide →
- Jurisdiction
- Canada
- Tax
- GST/HST
- Change type
- Rate change
- Status
- Proposed
- Impact
- Watch
- Announced
- 5 November 2026
- Effective
- 6 November 2026
- Authority
- Department of Finance Canada
- Systems
- Invoicing, Reporting
- Verified
- Fetched from official source · high confidence
Massage therapists and clinics supplying qualifying massage therapy services, and suppliers and purchasers of devices specially designed to treat cancer using alternating electric field therapy; nothing changes until implementing legislation is enacted.
Massage therapy providers should assess whether they meet the provincial licensing or equivalency requirement for the exemption and prepare to stop charging GST/HST on eligible services; businesses acquiring qualifying cancer-treatment devices should track acquisition dates.
InvoicingReporting
Canada's federal Budget 2026, tabled on 5 November 2026, proposes to exempt qualifying massage therapy services from GST/HST and to zero-rate devices specially designed to treat cancer using alternating electric field therapy. The measures are proposals and require implementing legislation.
What changed in detail
This is a budget proposal, not law. Canada’s federal Budget 2026, tabled on 5 November 2026, lists a measure titled “GST/HST health measures” in the table of proposed tax measures in Chapter 6. The measure proposes two changes to the GST/HST treatment of health-related supplies:
- the supply of qualifying massage therapy services would become exempt from GST/HST; and
- devices specially designed to treat cancer using alternating electric field therapy would become zero-rated.
The budget table costs the measure at 20, 41, 46, 46 and 46 (CAD millions) across the projection years, 199 in total. The Budget’s tax-measures supplement states that the measures would apply to qualifying supplies made after Budget Day, that is, from 6 November 2026. The measures require implementing legislation (no Budget Implementation Act had been tabled as of 11 November 2026), and the proposals may change before enactment.
What it means
Exempt and zero-rated are not the same outcome. Massage therapists who become exempt stop charging GST/HST but also lose input tax credits on their own costs, so the exemption is not a straight saving for a clinic with large fit-out or equipment spend. Zero-rating the cancer-treatment devices keeps the supplier’s credits intact. Clinics should check whether their therapists meet the licensing or equivalency condition the government ties to “qualifying” services before planning to stop charging tax, and should not change invoicing until the legislation is introduced and its wording is known.
Proof
This measure proposes to exempt the supply of qualifying massage therapy services and zero-rate devices specially designed to treat cancer using alternating electric field therapy for GST/HST purposes.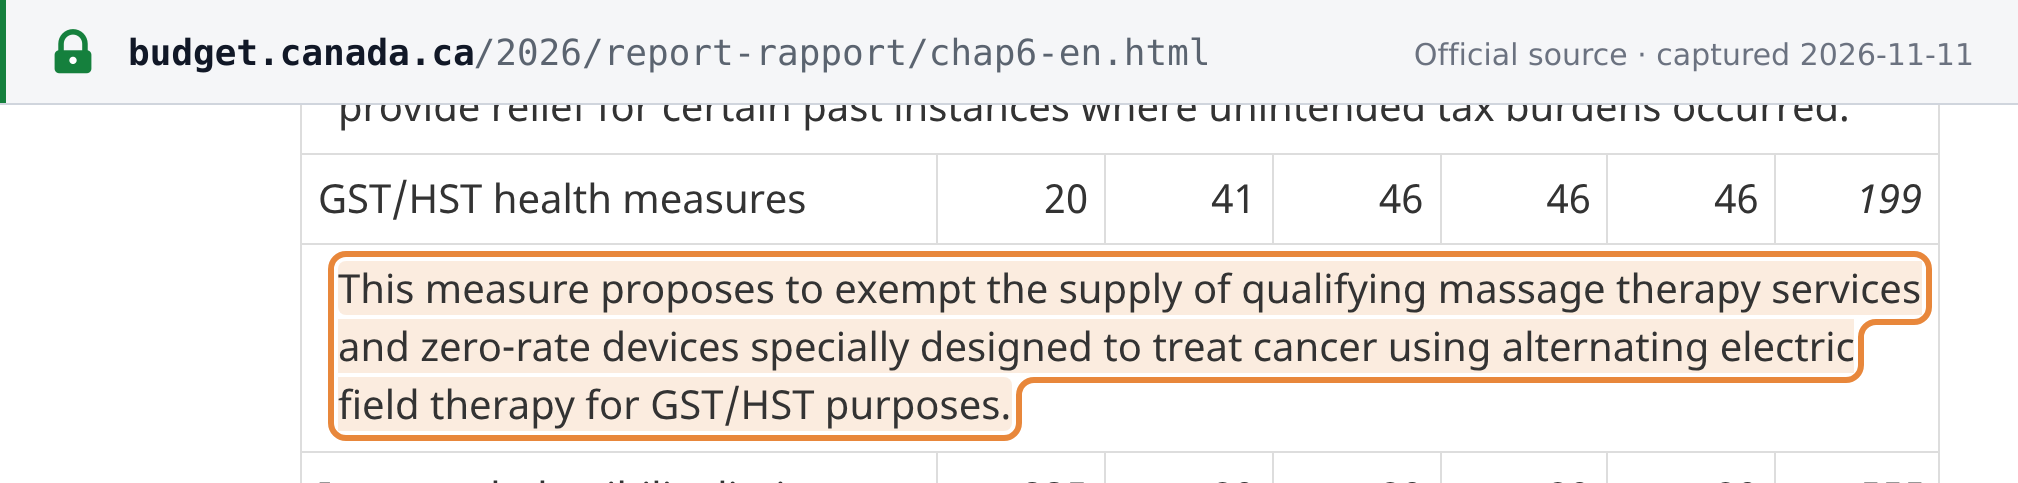 Source snapshot of the official page. Open full size ↗