Canada enacts a GST rebate of up to $50,000 for first-time buyers of new homes, deemed in force from 20 March 2025
This page records one dated change. For the rules in Canada as they stand today, see the Canada guide →
- Jurisdiction
- Canada
- Tax
- GST/HST
- Change type
- Rate change
- Status
- In force
- Impact
- Action required
- Announced
- 12 March 2026
- Effective
- 20 March 2025
- Instrument
- CA-ACT-OF-PARLIAMENT-S-C-2026-c-2
- Authority
- Department of Justice Canada (Justice Laws Website)
- Verified
- Fetched from official source · high confidence
First-time home buyers (18 or older, Canadian citizens or permanent residents) of new or substantially renovated homes, owner-builders and co-op housing members, plus builders who credit the rebate at closing; agreements after 19 March 2025 and before 2031.
Builders and sellers of new homes should check first-time home buyer eligibility on agreements entered into after March 19, 2025 and before 2031, and apply the rebate rules (up to $50,000 GST/federal HST) on qualifying sales; buyers who have not received it through the builder should claim it from the CRA within the rebate deadlines.
The Making Life More Affordable for Canadians Act (S.C. 2026, c. 2), assented to March 12, 2026, adds a temporary first-time home buyers' GST new housing rebate to the Excise Tax Act: up to $50,000 (the lesser of $50,000 and the tax paid) on a new single-unit home or condominium unit with total consideration of $1,000,000 or less, phased out to zero at $1,500,000, with parallel rebates for building-only, cooperative housing (4.77% of consideration, capped at $50,000) and owner-built homes. The buyer must be 18 or older, a Canadian citizen or permanent resident, and must not have lived in a home owned by them or their spouse as a primary residence in the current or previous four calendar years; the agreement must be entered into after March 19, 2025 and before 2031, with construction beginning before 2031 and substantially completed before 2036. The measures are deemed in force March 20, 2025.
What changed in detail
The Making Life More Affordable for Canadians Act (S.C. 2026, c. 2) received Royal Assent on 12 March 2026. Sections 3 to 7 add a first-time home buyers’ GST new housing rebate to the Excise Tax Act.
- Section 3 defines a first-time home buyer in s. 123(1): an individual aged 18 or older, a Canadian citizen or permanent resident, who in the current year and the four preceding calendar years did not live, as a primary residence, in a home owned by them or by their spouse or common-law partner.
- Section 4 replaces s. 254(2.01) to (2.1). Where the agreement of purchase and sale is entered into after 19 March 2025 and before 2031, construction begins before 2031 and is substantially completed before 2036, ownership passes before 2036, and the buyer is the first occupant and buys it as a primary residence, the Minister pays an additional rebate. Up to $1,000,000 of total consideration, it is the lesser of $50,000 and the tax paid, less any ordinary new housing rebate. Between $1,000,000 and $1,500,000 it phases out to zero.
- Sections 5 to 7 add parallel rebates for building-only purchases, co-op housing shares and owner-built homes; each is 4.77% of the consideration, capped at $50,000 and phased out from $1,050,000 to $1,575,000.
Each provision is deemed to have come into force on 20 March 2025, almost a year before assent.
What it means
The rebate is in force and open until agreements made in 2030. Because the law was passed a year after its start date, buyers who closed between March 2025 and March 2026 without the rebate credited at closing have to claim it from the CRA within the rebate deadlines.
The test looks back over the current year and four calendar years, so a buyer who sold a former home recently may not qualify. A spouse’s ownership counts too.
Ontario now adds its own matching rebate of the 8% provincial HST component. It is set out in SOR/2026-94, published 17 June 2026, and is deemed in force from 20 March 2025. The federal rebate itself covers only the GST, or the federal part of the HST.
Proof
the Minister shall, subject to subsection (3), pay a rebate to the particular individual, in addition to the rebate, if any, payable under subsection (2) to the particular individual, equal to (f) if the total consideration, within the meaning of paragraph (2)(c), in respect of the residential complex is not more than $1,000,000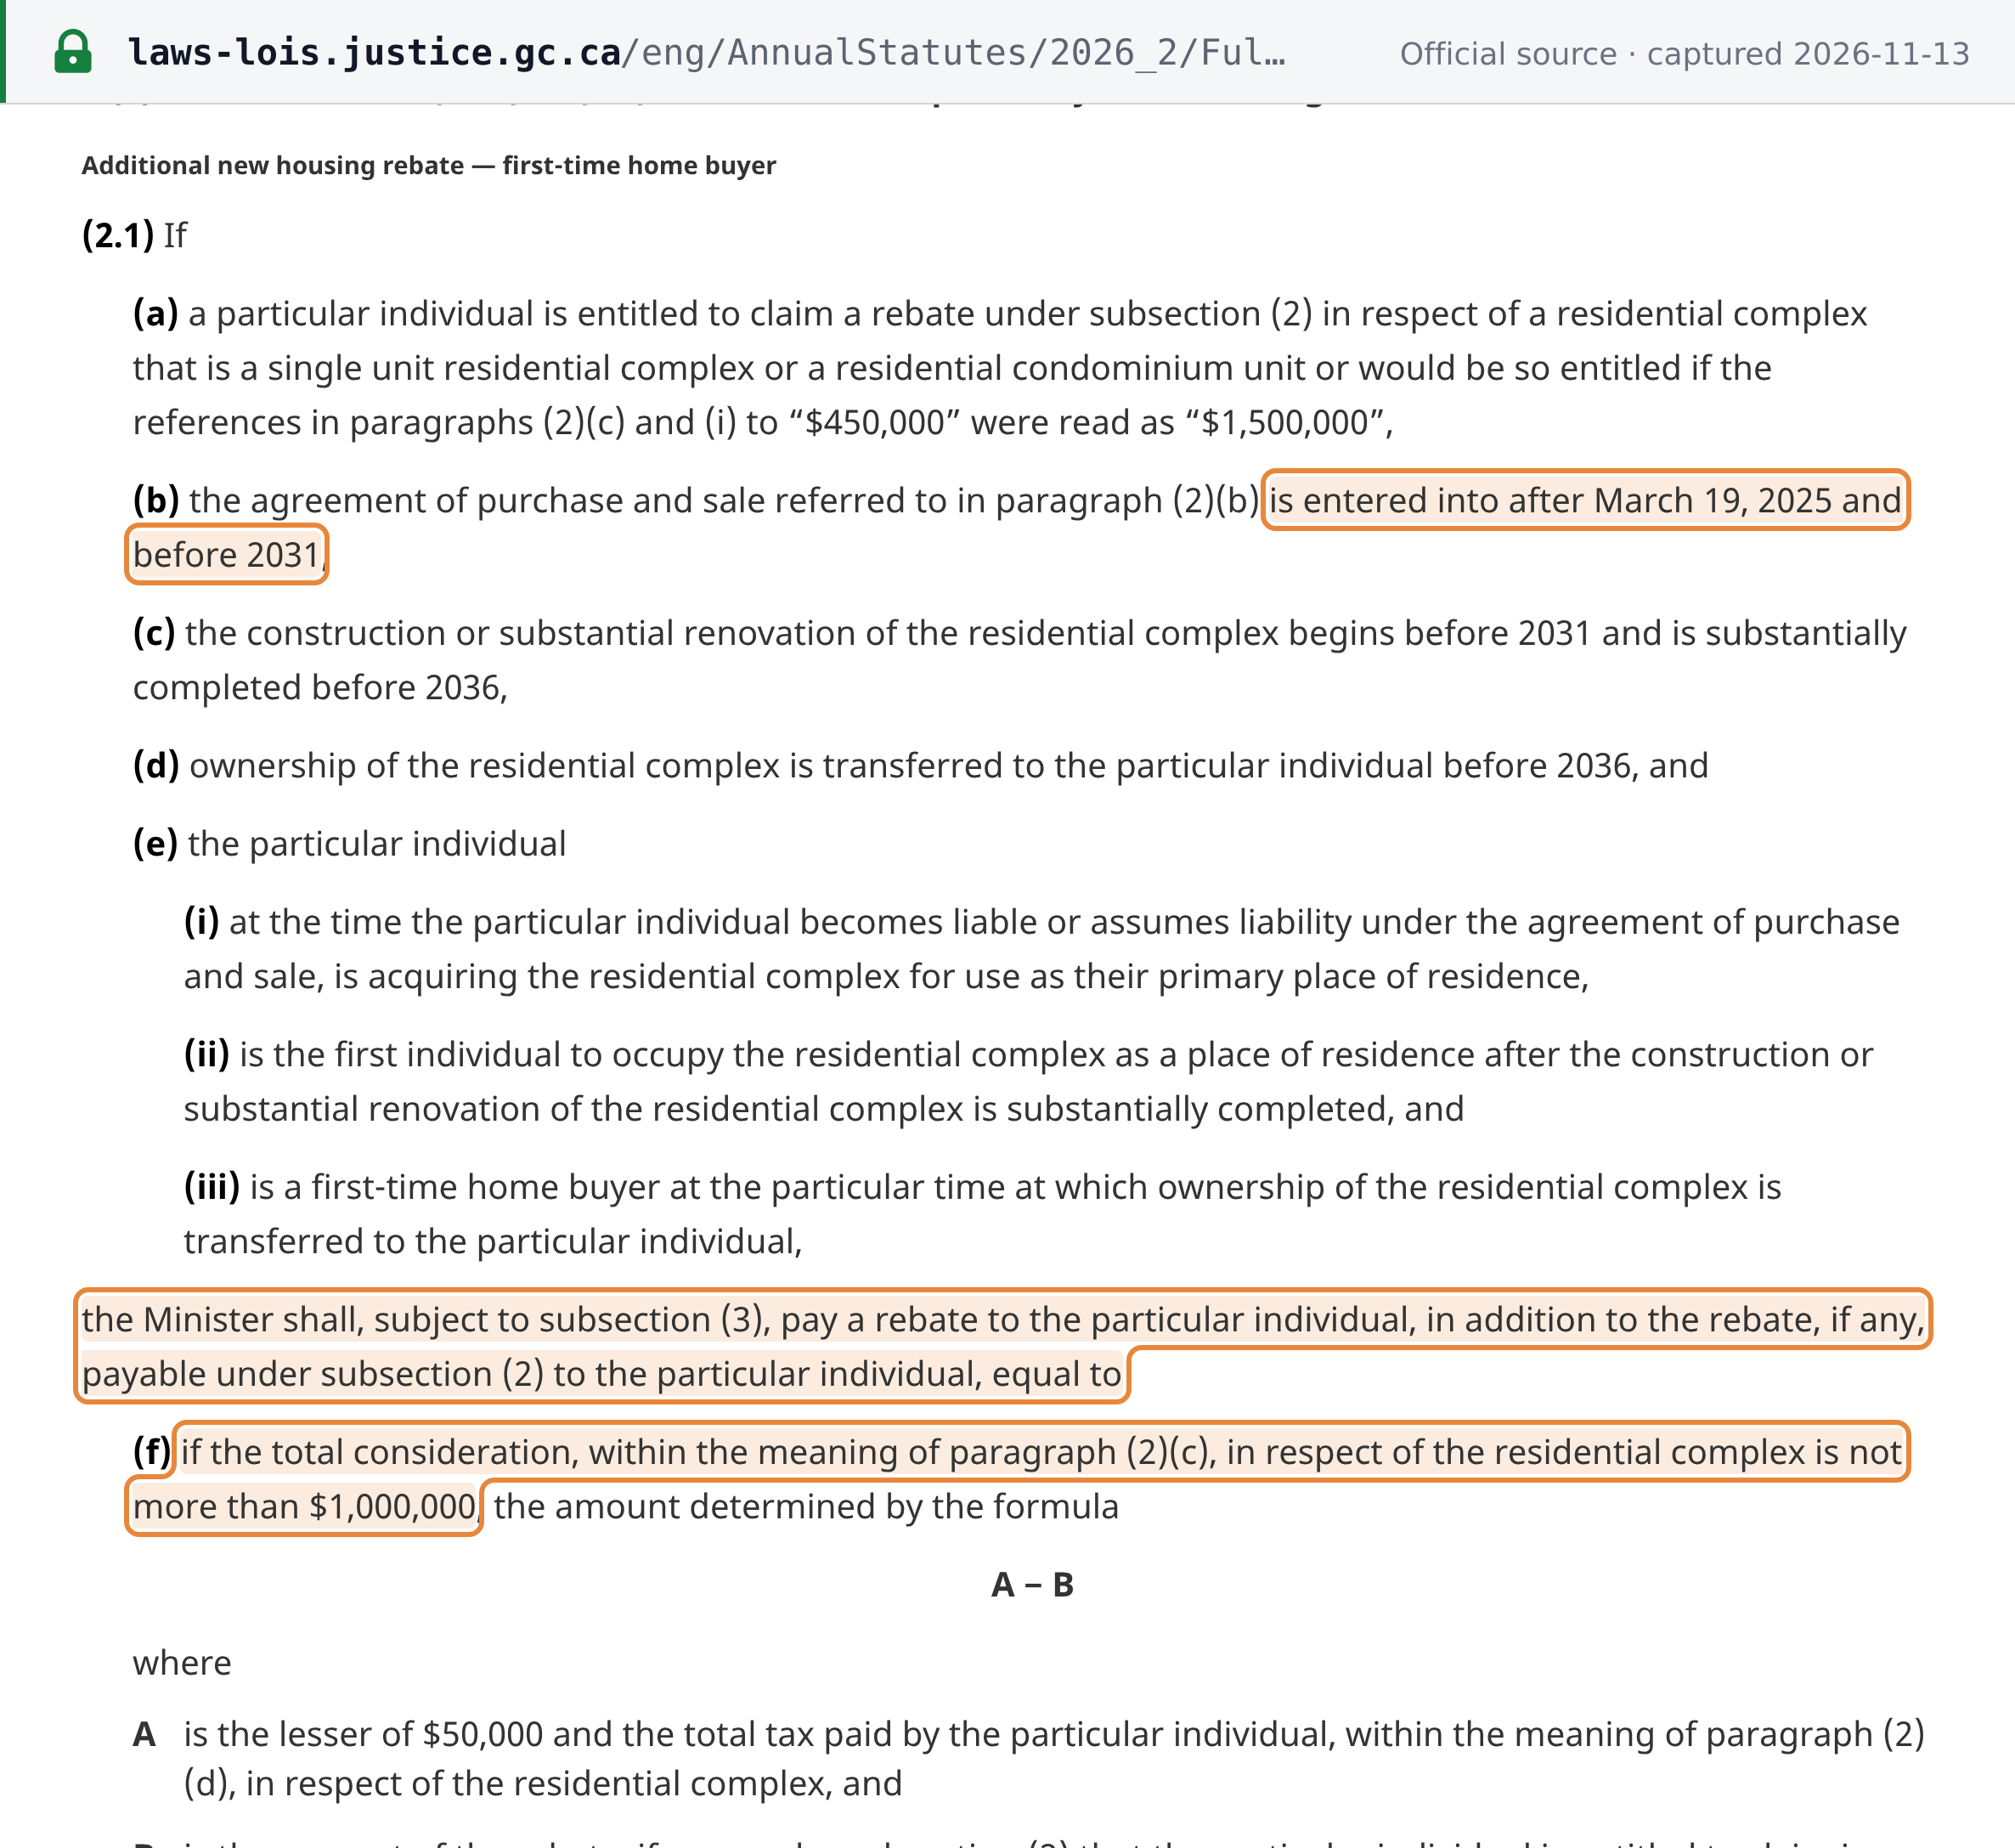 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Making Life More Affordable for Canadians Act, S.C. 2026, c. 2 (annual statute, Justice Laws Website PDF) · laws-lois.justice.gc.ca