China restates export VAT refund rules under the VAT Law and adds a 36-month claim limit (Announcement No. 11 of 2026)
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- Action required
- Announced
- 30 January 2026
- Effective
- 1 January 2026
- Instrument
- CN-JOINT-ANNOUNCEMENT-2026-11
- Authority
- 财政部 税务总局 (Ministry of Finance and State Taxation Administration of the People's Republic of China)
- Verified
- Fetched from official source · high confidence
Exporters of goods from China and suppliers of zero-rated or exempt cross-border services and intangible assets.
Exporters must file refund or exemption claims within 36 months (goods: from the export date; services and intangibles: from the tax point) for business from 1 January 2026; unclaimed amounts become taxable domestic sales.
MOF and STA Announcement No. 11 of 2026 (财政部 税务总局公告2026年第11号), issued 30 January 2026 and effective 1 January 2026, restates the export VAT and consumption-tax refund, exemption and taxation rules under the VAT Law, keeping the existing refund methods and rates. It introduces a 36-month limit (calendar days). Exported goods not claimed by 30 April of the following year may still be claimed, with proof of foreign-exchange receipt, up to 36 months after export. Cross-border services and intangibles must be claimed within 36 months of the tax point. Exports, services or intangibles not claimed within the 36 months are treated as domestic sales and taxed the day after the limit expires, except supplies by or between taxpayers in special customs supervision zones and sales by approved duty-free shops (Part IV 4(6)); exempt cases deemed domestic sales keep the exemption (4(7)). The limit does not apply to export business on or before 31 December 2025. Caishui [2012] No. 39, Caishui [2014] No. 98 and Article 4 of MOF/STA Announcement No. 2 of 2020 are repealed.
What changed in detail
The Ministry of Finance and the State Taxation Administration issued Announcement No. 11 of 2026 (财政部 税务总局公告2026年第11号) on 30 January 2026. It applies from 1 January 2026. It restates, under the VAT Law, which exports and cross-border services get a refund (exemption), which are exempt and which are taxed. It keeps the existing exempt-credit-refund and exempt-refund methods. The refund rate is the applicable VAT rate unless MOF and STA set another rate.
The new element is a 36-month limit, counted in calendar days:
- Goods (declared, non-declared and bonded-zone exports). Claims are normally due by 30 April of the following year. A late claim, with proof of foreign-exchange receipt, can still be filed up to 36 months after export.
- Cross-border services and intangibles. Claims must be filed within 36 months of the tax point.
- Unclaimed after 36 months. Goods, services or intangibles are treated as domestic sales, and VAT and consumption tax are due the day after the limit expires. Exempt exports not declared in time are treated the same way. The deemed-sale rule has exceptions (Part IV 4(6)): exports and processing by taxpayers in special customs supervision zones, sales between taxpayers in those zones, and sales by approved duty-free shops.
Export business on or before 31 December 2025 stays under the old rules and is not subject to the 36-month deemed-sale rule. Caishui [2012] No. 39, Caishui [2014] No. 98 and Article 4 of MOF/STA Announcement No. 2 of 2020 are repealed.
What it means
The framework is in force at November 2026. The 36-month clock started with exports made on or after 1 January 2026, so the first deemed-sale charges cannot arise before early 2029. Exporters should track unclaimed items from now on, because a lapsed claim becomes output tax, not just a lost refund. The announcement fixes the refund method, not the rates. Rates change by separate notice, as with the December 2024 refund-rate cuts. Since then: battery refunds are cut in 2026 and abolished from 2027, and the NEV refund falls to 9% from April 2027.
Proof
自纳税义务发生之日起36个月内,未申报退(免)税的,视同向境内销售服务、无形资产。If no refund (exemption) has been claimed within 36 months of the date the tax obligation arose, the transaction is treated as a domestic sale of services or intangible assets.
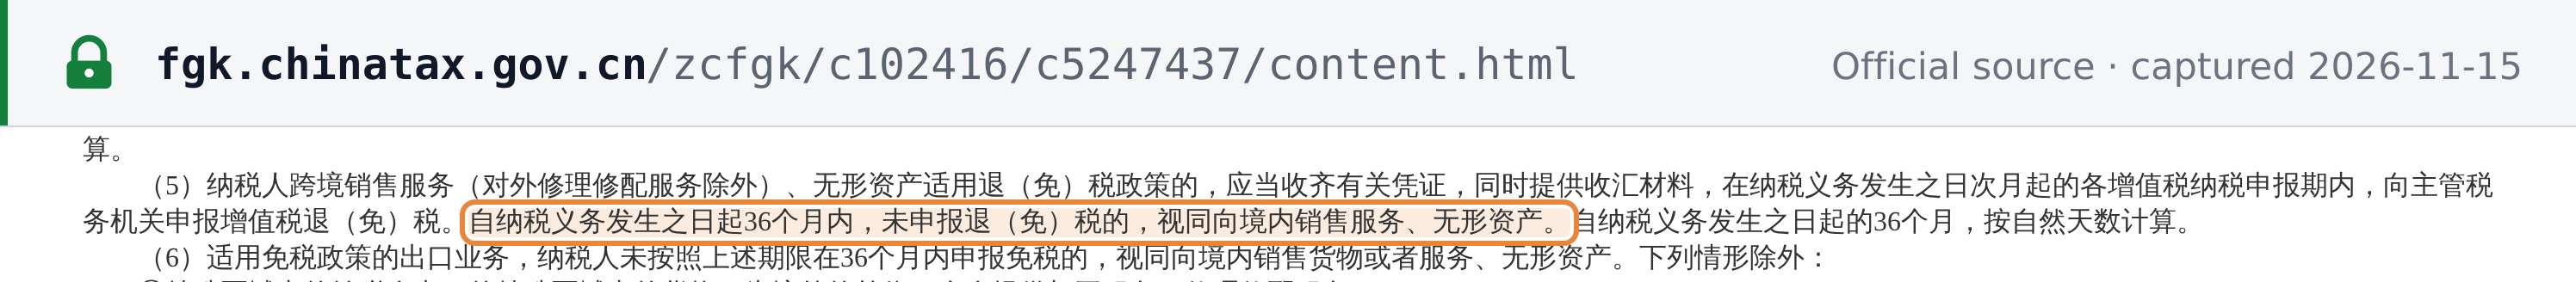 Source snapshot of the official page. Open full size ↗