China resets general-taxpayer VAT registration under the VAT Law and abolishes the counselling period (STA Announcement No. 2 of 2026)
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Registration
- Status
- In force
- Impact
- Action required
- Announced
- 1 January 2026
- Effective
- 1 January 2026
- Instrument
- CN-STA-ANNOUNCEMENT-2026-2
- Authority
- 国家税务总局 (State Taxation Administration of the People's Republic of China)
- Verified
- Fetched from official source · high confidence
VAT taxpayers in China whose taxable sales over any 12 consecutive months or four quarters exceed the small-scale taxpayer standard.
Businesses approaching or exceeding the VAT small-scale taxpayer annual sales threshold should confirm general-taxpayer registration requirements under the new VAT Law framework. STA Order No. 43 (the old registration rules) is repealed; apply the new criteria from 1 January 2026.
STA Announcement No. 2 of 2026 (国家税务总局公告2026年第2号), issued and effective 1 January 2026, sets general-taxpayer registration rules under the VAT Law. Taxpayers whose annual taxable sales (any 12 consecutive months or four quarters) exceed the small-scale standard must register as general taxpayers, by the next filing deadline (or within 10 working days where an adjustment pushes them over). Status takes effect from the first day of the period in which the standard was exceeded. Exceptions are natural persons and non-enterprise units that rarely make taxable supplies and elect small-scale treatment. The general-taxpayer counselling period (辅导期) is abolished from 1 January 2026. The announcement repeals STA Announcement No. 6 of 2018 and Guoshuifa [2010] No. 40, and STA Order No. 62 repeals the 2017 registration measures (STA Order No. 43) from the same date.
What changed in detail
The State Taxation Administration issued Announcement No. 2 of 2026 (国家税务总局公告2026年第2号) on 1 January 2026, the day the VAT Law took effect. It applies from the same day.
Who must register. A taxpayer whose annual taxable sales exceed the small-scale standard under the VAT Law must register as a general taxpayer. Annual sales are cumulative sales over any period of up to 12 consecutive months or four quarters. Two cases are excepted: natural persons, and non-enterprise units that rarely make taxable supplies and elect small-scale treatment. Occasional sales of intangibles or immovable property are left out of the count. Smaller taxpayers with sound accounts may register voluntarily.
Deadlines and effect. Registration is due within the filing period of the month after the standard is exceeded. Where sales are pushed over the standard by a self-correction, risk review or audit, it is due within 10 working days of the adjustment. General-taxpayer status takes effect from the first day of the period in which the standard was exceeded. Periods already filed as small-scale must then be corrected. A taxpayer that misses the deadline is managed as a general taxpayer from 5 working days after it.
Transition and repeals. The general-taxpayer counselling period (辅导期) ends on 1 January 2026, and leftover prepaid VAT from it can be offset or refunded. STA Announcement No. 6 of 2018 and Guoshuifa [2010] No. 40 are repealed. STA Order No. 62 repeals the 2017 registration measures (STA Order No. 43) from the same date.
What it means
The rules are in force at November 2026. The test is cumulative sales over a rolling period of up to 12 months, measured against the standard in the VAT Law and the Implementation Regulations. Status is backdated to the start of the period in which the line was crossed. A business that notices late has to refile earlier periods as a general taxpayer, so it needs to watch its rolling sales, not only its year-end total. Ending the 辅导期 removes the old probation, which capped special-invoice supplies and required prepayments for new general taxpayers. The small-scale rate and threshold that sit beside these rules are in Announcement No. 10 of 2026.
Proof
一、增值税纳税人(以下简称纳税人)年应征增值税销售额超过增值税法规定的小规模纳税人标准(以下简称规定标准)的,除以下两类情形外,应办理一般纳税人登记。1. VAT taxpayers ("taxpayers") whose annual taxable VAT sales exceed the small-scale taxpayer standard set under the VAT Law ("the standard") must register as general taxpayers, except in the following two cases.
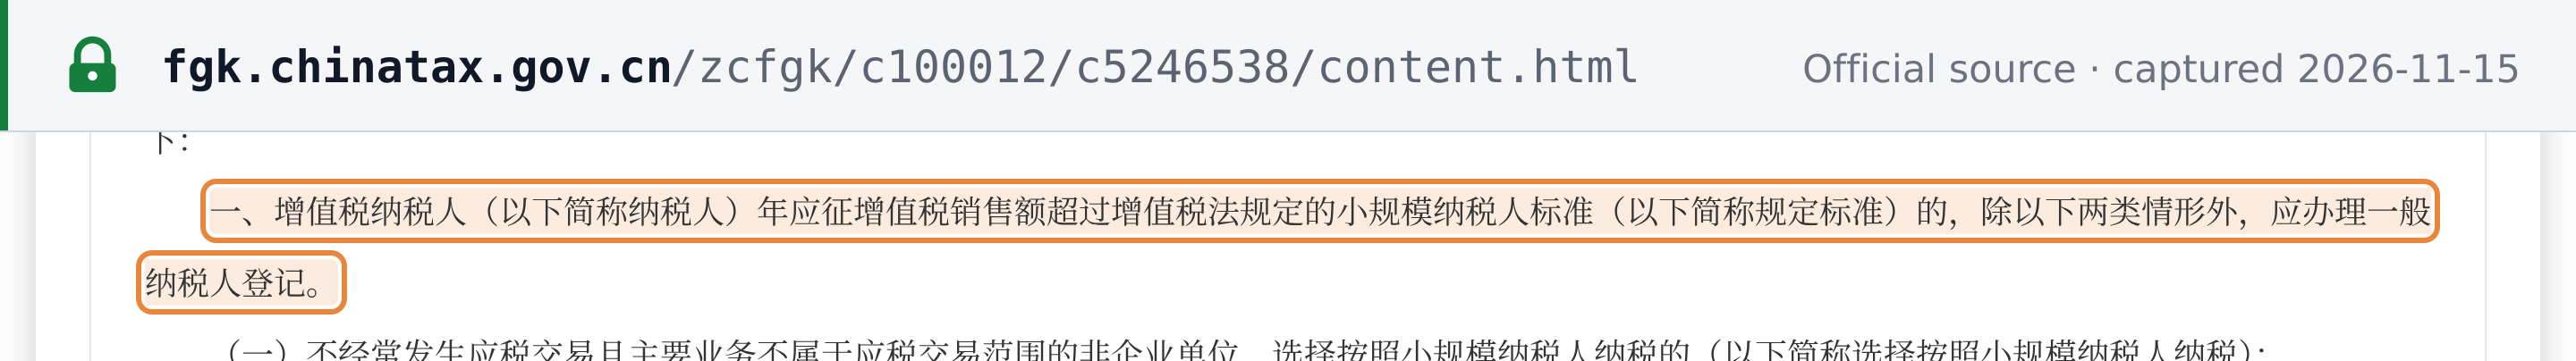 Source snapshot of the official page. Open full size ↗