China lets resource-recovery enterprises issue "reverse invoices" to individuals selling scrap, from 29 April 2024
This page records one dated change. For the rules in China as they stand today, see the China guide →
- Jurisdiction
- China
- Tax
- VAT
- Change type
- Invoice rules
- Status
- In force
- Impact
- Action required
- Announced
- 24 April 2024
- Effective
- 29 April 2024
- Instrument
- CN-STA-ANNOUNCEMENT-2024-5
- Authority
- 国家税务总局 (State Taxation Administration of the People's Republic of China)
- Verified
- Fetched from official source · high confidence
Resource-recovery enterprises holding a hazardous-waste licence, a scrap-vehicle recycling certificate or a commerce-department recycling filing, and natural persons selling them scrap (up to RMB 5 million over 12 months).
Resource recovery enterprises purchasing scrap from natural persons should determine whether they qualify for the reverse-invoicing scheme (licence/registration requirements in Article 2). If qualifying, establish procedures for issuing invoices via the electronic invoice platform on behalf of sellers, and comply with agency-filing obligations when any seller's monthly sales exceed RMB 100,000.
STA Announcement No. 5 of 2024 (国家税务总局公告2024年第5号), issued 24 April 2024 and effective 29 April 2024, introduces "reverse invoicing" (反向开票): qualifying resource-recovery enterprises (holding a hazardous-waste licence, a scrap-vehicle recycling certificate, or a commerce-department recycling-operator filing) may issue invoices, marked "报废产品收购", to natural persons who sell them scrap products. This applies while the seller's reverse-invoiced sales stay within RMB 5 million (excluding VAT) over any 12 consecutive months. The enterprise must file and pay, as agent, the seller's VAT, surtaxes and individual income tax. Sellers keep the small-scale relief (monthly sales up to RMB 100,000 exempt; 1% rate). Where a seller's monthly sales exceed RMB 100,000, each enterprise declares VAT on the amount it invoiced.
What changed in detail
The State Taxation Administration issued Announcement No. 5 of 2024 (国家税务总局公告2024年第5号), dated 24 April 2024. From 29 April 2024, a qualifying resource-recovery enterprise may issue the invoice itself when it buys scrap products from a natural person. This is called reverse invoicing (反向开票).
- Who may issue (Article 2): units and individual businesses actually in resource recovery that hold a hazardous-waste operating licence, a scrap-vehicle recycling and dismantling certificate, or (for other recyclables) a business registration and a commerce-department recycling-operator filing. They apply to their tax office first (Article 4).
- Which sellers (Articles 1 and 3): natural persons whose reverse-invoiced sales stay within RMB 5 million (excluding VAT) over any 12 consecutive months. Above that the enterprise must stop and the seller should register a business.
- How (Article 5): online, through the electronic invoice service platform or the VAT invoice system, marked 报废产品收购.
- Agency filing (Articles 11 and 13): the enterprise files and pays the seller’s VAT, surtaxes and individual income tax. Sellers keep the small-scale relief (monthly sales up to RMB 100,000 exempt; 1% rate). Where a seller’s monthly sales exceed RMB 100,000, each enterprise declares VAT on the amount it invoiced.
- Income tax (Article 14): sellers prepay individual income tax at 0.5% of sales and file an annual return by 31 March.
What it means
The scheme is still in force; the STA policy library marks the announcement 全文有效 (fully valid) as of November 2026. Article 13 ties the sellers’ relief to the small-scale taxpayer rules as later adjusted. Since 1 January 2026 those are set under the VAT Law by MOF/STA Announcement No. 10 of 2026 (cn-small-taxpayer-vat-law-2026): a threshold of RMB 100,000 a month and 1% instead of 3%, through 31 December 2027. Recyclers should check that their agency filings use those figures, and keep the purchase evidence Article 17 requires (contracts, weighbridge slips, payment records). That evidence is what supports the input VAT and the corporate income tax deduction on a reverse invoice.
Proof
一、自2024年4月29日起,自然人报废产品出售者(以下简称出售者)向资源回收企业销售报废产品,符合条件的资源回收企业可以向出售者开具发票(以下称“反向开票”)。1. From 29 April 2024, where natural persons selling scrap products ("sellers") sell scrap products to resource-recovery enterprises, qualifying resource-recovery enterprises may issue invoices to the sellers ("reverse invoicing").
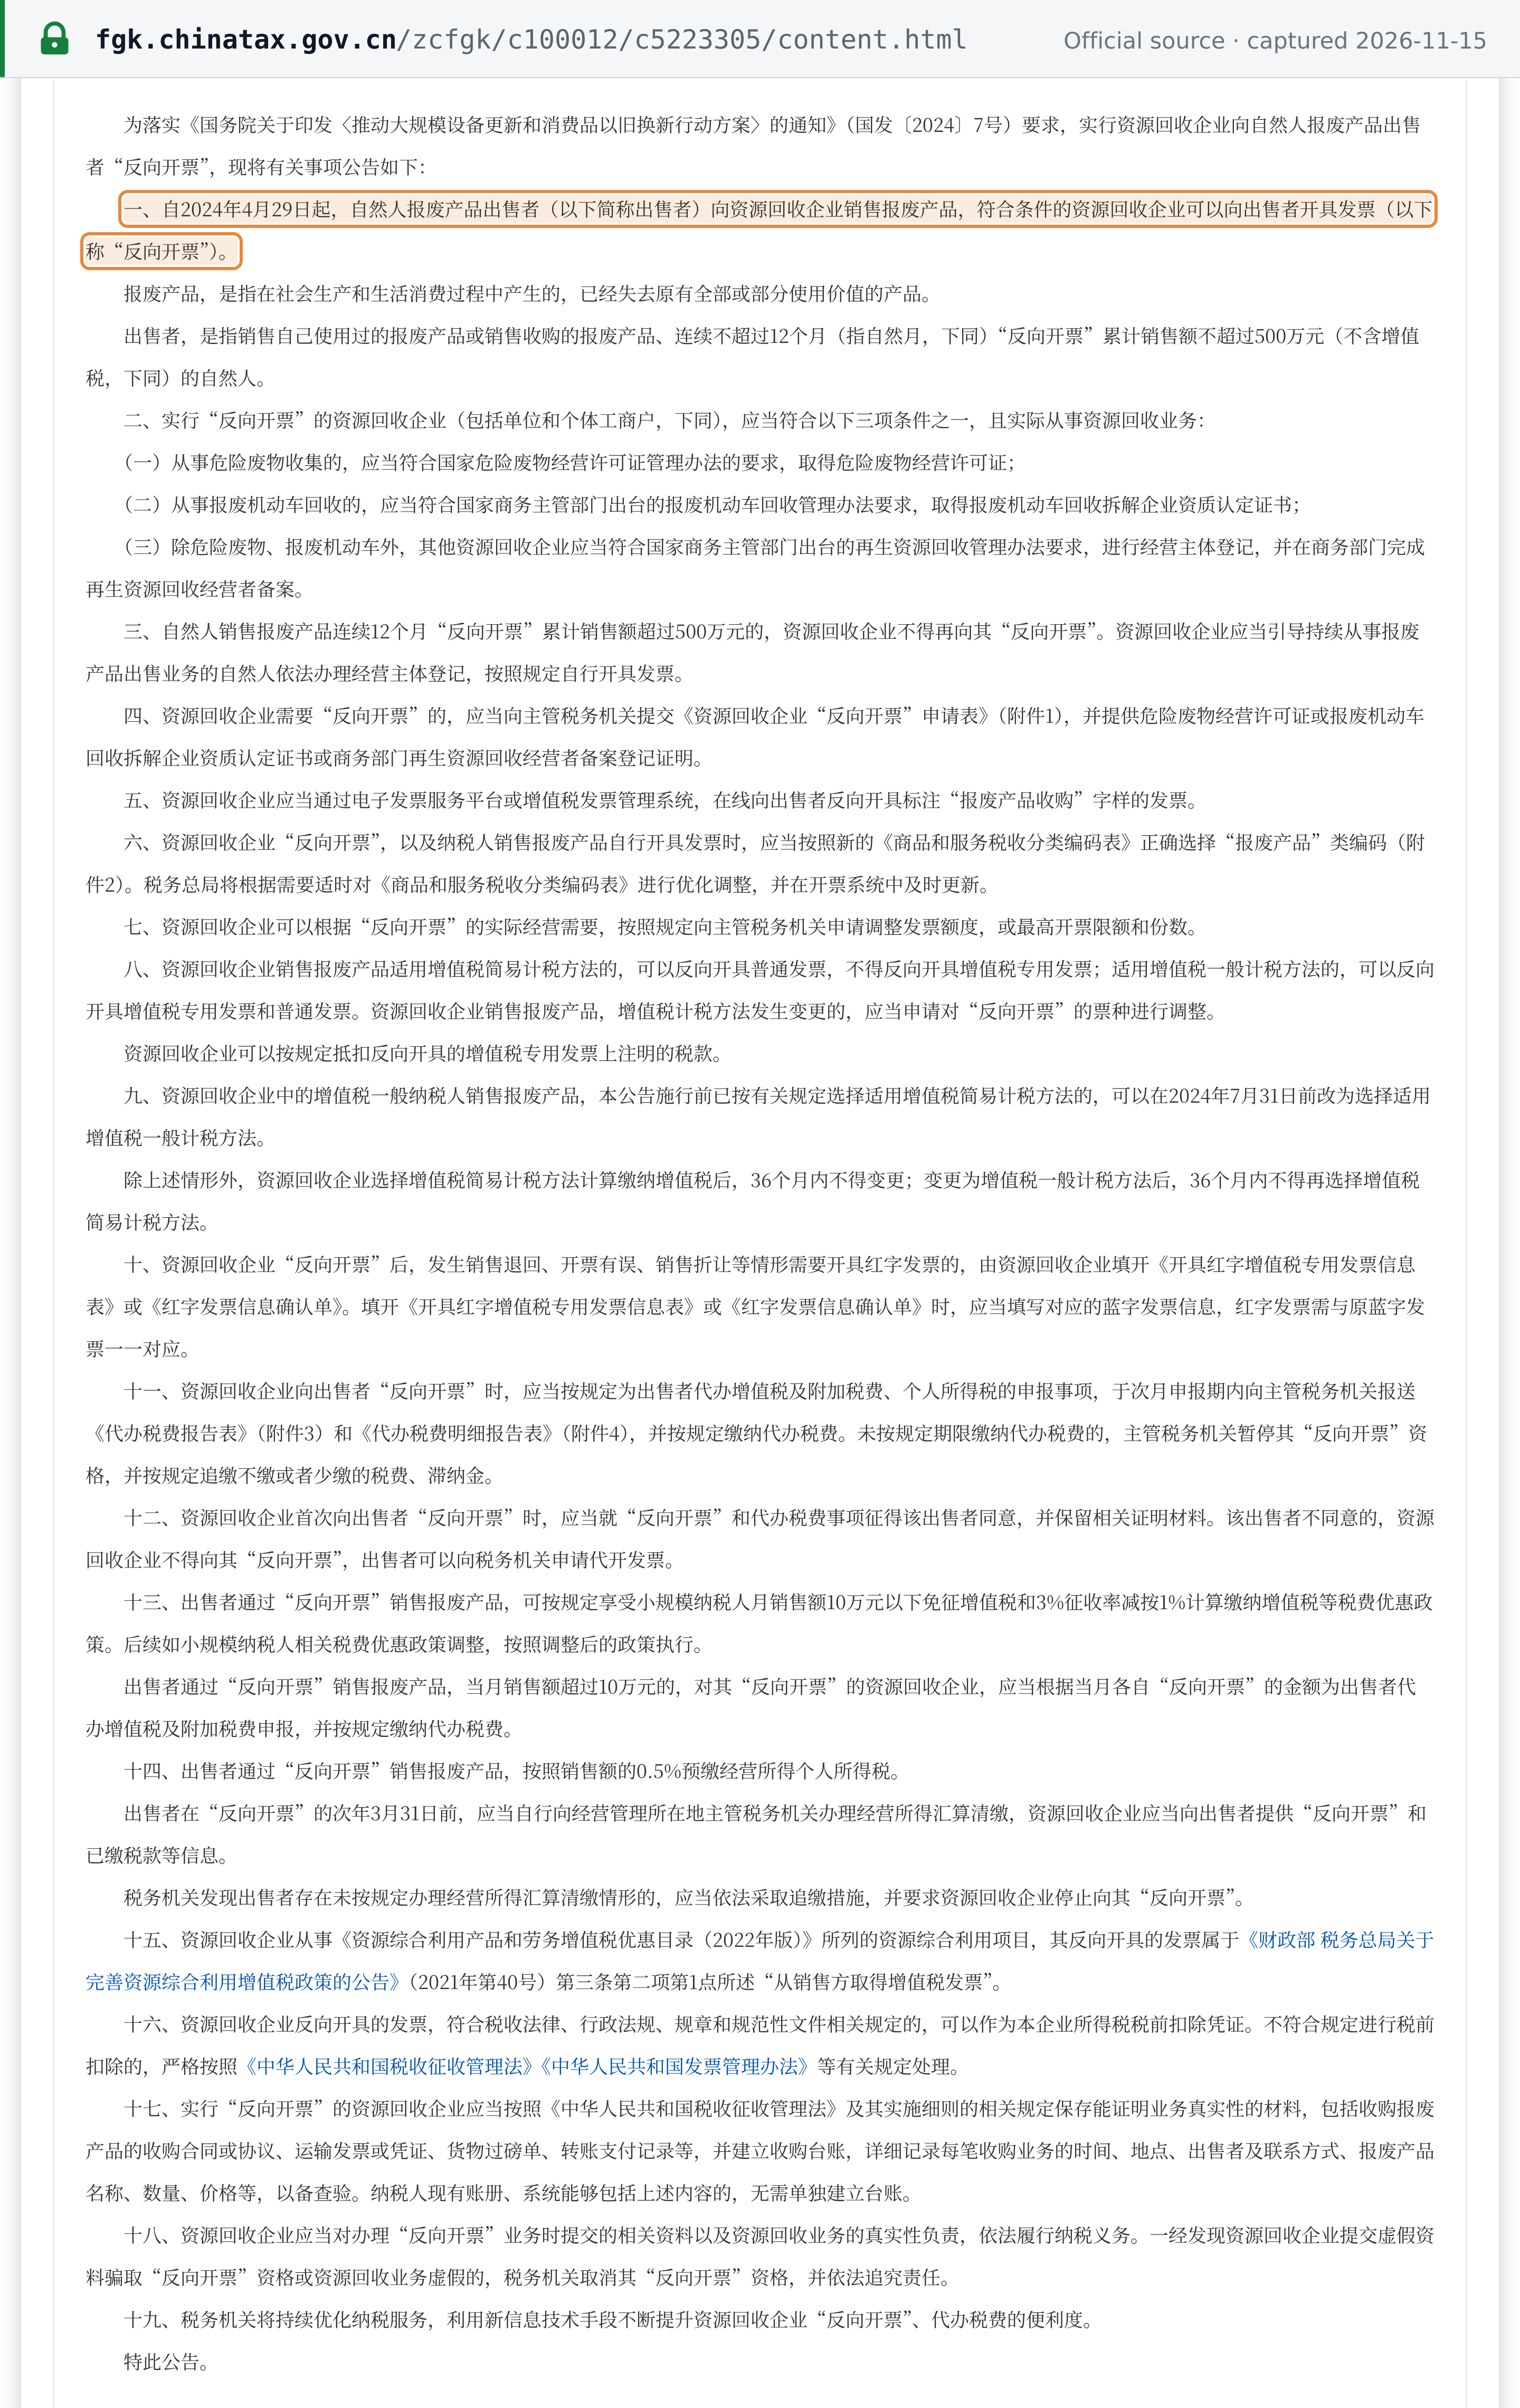 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 国家税务总局公告2024年第5号(成文日期 2024-04-24),第一条 · fgk.chinatax.gov.cn