Congo-Brazzaville overhauls its VAT law for 2024: 18% general rate, 5% reduced rate and a FCFA 100 million threshold
This page records one dated change. For the rules in Republic of the Congo as they stand today, see the Republic of the Congo guide →
- Jurisdiction
- Republic of the Congo
- Tax
- TVA
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 29 December 2023
- Effective
- 1 January 2024
- Instrument
- CG-ACT-39-2023
- Authority
- Secrétariat Général du Gouvernement, République du Congo (Journal officiel)
- Verified
- Fetched from official source · high confidence
All legal persons carrying on taxable activities in Congo-Brazzaville, whatever their turnover; natural persons with annual turnover of FCFA 100,000,000 or more.
No action — the 2024 TVA reform has been in force since 1 January 2024.
Loi n° 39-2023 du 29 décembre 2023 portant loi de finances pour l'année 2024 comprehensively overhauled the TVA regime, transposing CEMAC Directive n°11/22. Article 22(2)(a) sets the general TVA rate at 18%. Article 38 A creates centimes additionnels at 5% of the TVA collected, payable to local authorities (effective combined burden 18.9%). Article 22(2)(c) establishes a 5% reduced rate for basic consumer goods (milk, bakery products, rice, flour, fertilizers, pesticides) and SEZ operators. Article 5 sets the TVA registration threshold for natural persons at FCFA 100,000,000 turnover per annum; legal persons are automatically subject regardless of turnover. Loi n° 47-2024 (LF 2025) later rewrote Article 22(2)(c); its 5% list no longer includes fertilizers and pesticides.
What changed in detail
Loi n° 39-2023 du 29 décembre 2023, the finance law for 2024, was published in the Journal officiel, Édition spéciale N° 6-2023, on 29 December 2023. It rewrites the TVA law, transposing CEMAC Directive n° 11/22. It applies for the 2024 budget year, so from 1 January 2024; the text sets no separate start date.
The main rules:
- Rates (article 22(2)):
- 18% general rate;
- 0% for exports and international transport;
- 5% reduced rate for listed basic consumer goods and for operators in special economic zones. The list covers milk, bakery products, rice, wheat flour, fertilisers and pesticides.
- Centimes additionnels (article 38 A): a surcharge of 5% of the TVA collected, paid to local authorities. The combined burden at the general rate is therefore 18.9%.
- Who is liable (article 5): a natural person must account for TVA once turnover reaches FCFA 100,000,000 a year. Legal persons are liable whatever their turnover.
What it means
The 18% general rate is still in force. It is the rate applied to non-resident digital services from July 2026. The 5% list, however, has changed.
Loi n° 47-2024, the finance law for 2025, rewrote article 22(2)(c) from 1 January 2025. Its new 5% list keeps milk, bakery products, rice and wheat flour, but drops fertilisers and pesticides from the 5% list. They are listed in Annexe 3 (exempt first-necessity goods) in the 2026 finance law text; check the annex for the period concerned. The same law extended the TVA exemptions and made the certified e-invoicing system (SFEC) mandatory.
When pricing goods at 5%, check them against the 2025 list, not the 2024 one.
Proof
Taux général : 18 % applicable à toutes les opérations taxables à l’exclusion des opérations soumises aux taux réduit et zéroGeneral rate: 18% applicable to all taxable transactions except transactions subject to the reduced and zero rates
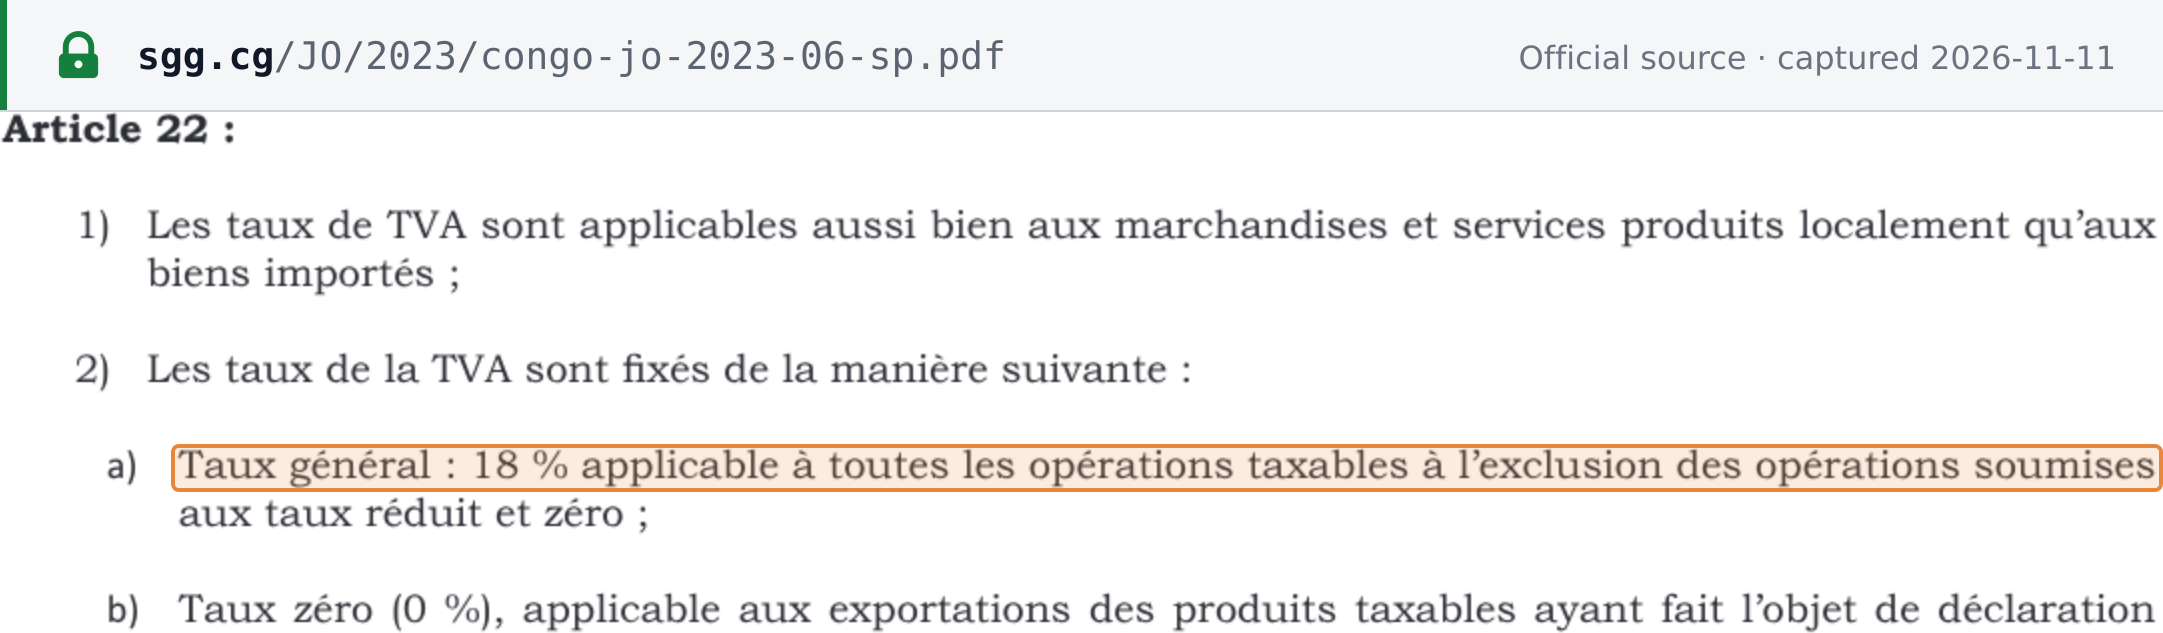 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Journal officiel de la République du Congo, Édition spéciale N° 6-2023 (29 décembre 2023): Loi n° 39-2023 portant loi de finances pour l'année 2024 · www.sgg.cg