Côte d’Ivoire makes VAT mandatory for public transport companies under the real regime
- Jurisdiction
- Côte d'Ivoire
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 18 December 2023
- Effective
- 1 January 2024
- Instrument
- CI-FINANCE-LAW-2023-1000
- Authority
- Direction Générale du Budget et des Finances, Côte d’Ivoire
- Verified
- Fetched from official source · high confidence
Public passenger and goods transport companies in Côte d’Ivoire under the régime réel d’imposition (annual turnover including taxes above CFA 200 million).
No action — monitoring only.
Finance Law 2024 (Loi n° 2023-1000 du 18 décembre 2023, Article 3) made TVA mandatory for public transport companies (persons and/or goods) operating under the régime réel d'imposition with annual turnover exceeding CFA 200 million, removing the previous optional election (opt-in). Effective 1 January 2024.
What changed in detail
Article 3 of the fiscal annex to Loi de finances n° 2023-1000 du 18 décembre 2023 (the budget law for 2024) changes how Côte d’Ivoire’s TVA treats public transport.
Before the change, article 355-8 of the Code Général des Impôts exempted transport activities from TVA, apart from deliveries of materials extracted in Côte d’Ivoire including transport and specialised transport such as cash convoying, towing and express document and parcel delivery. Public transport companies under a real taxation regime could opt into TVA under article 348.
The annex’s statement of reasons says the exemption did not conform to UEMOA Council decision n° 02/CM/2019/UEMOA of 21 June 2019. The text then:
- adds to article 344 of the CGI, among persons liable to TVA, “les entreprises de transport public de personnes et/ou de marchandises, relevant d’un régime réel d’imposition”;
- deletes the option in article 348 and the transport exemption in article 355-8.
The statement of reasons identifies the companies concerned as those whose annual turnover including all taxes exceeds CFA 200 million. The change applies with the 2024 budget year, from 1 January 2024.
What it means
The obligation is still in force. The 2025 Finance Law (Loi n° 2024-1109, Article 1) made what it called technical corrections to the measure: it allows full deduction of the TVA on fuel used in public transport vehicles of real-regime companies, and makes TVA on vehicles those companies acquire for public transport deductible.
For operators above the threshold, TVA is no longer a choice to weigh but a standing obligation: fares carry TVA, returns are due, and input tax becomes recoverable. Smaller operators outside the real regime remain outside the measure.
Proof
il est proposé de soumettre obligatoirement à la TVA, le transport public de personnes et/ou de marchandises lorsqu’il est effectué par des entreprises relevant d’un régime réel d’imposition, à savoir celles dont le chiffre d’affaires annuel toutes taxes comprises est supérieur à 200 millions de francs CFAit is proposed to make public transport of persons and/or goods compulsorily subject to VAT when carried out by businesses under a real taxation regime, namely those whose annual turnover including all taxes exceeds CFA 200 million
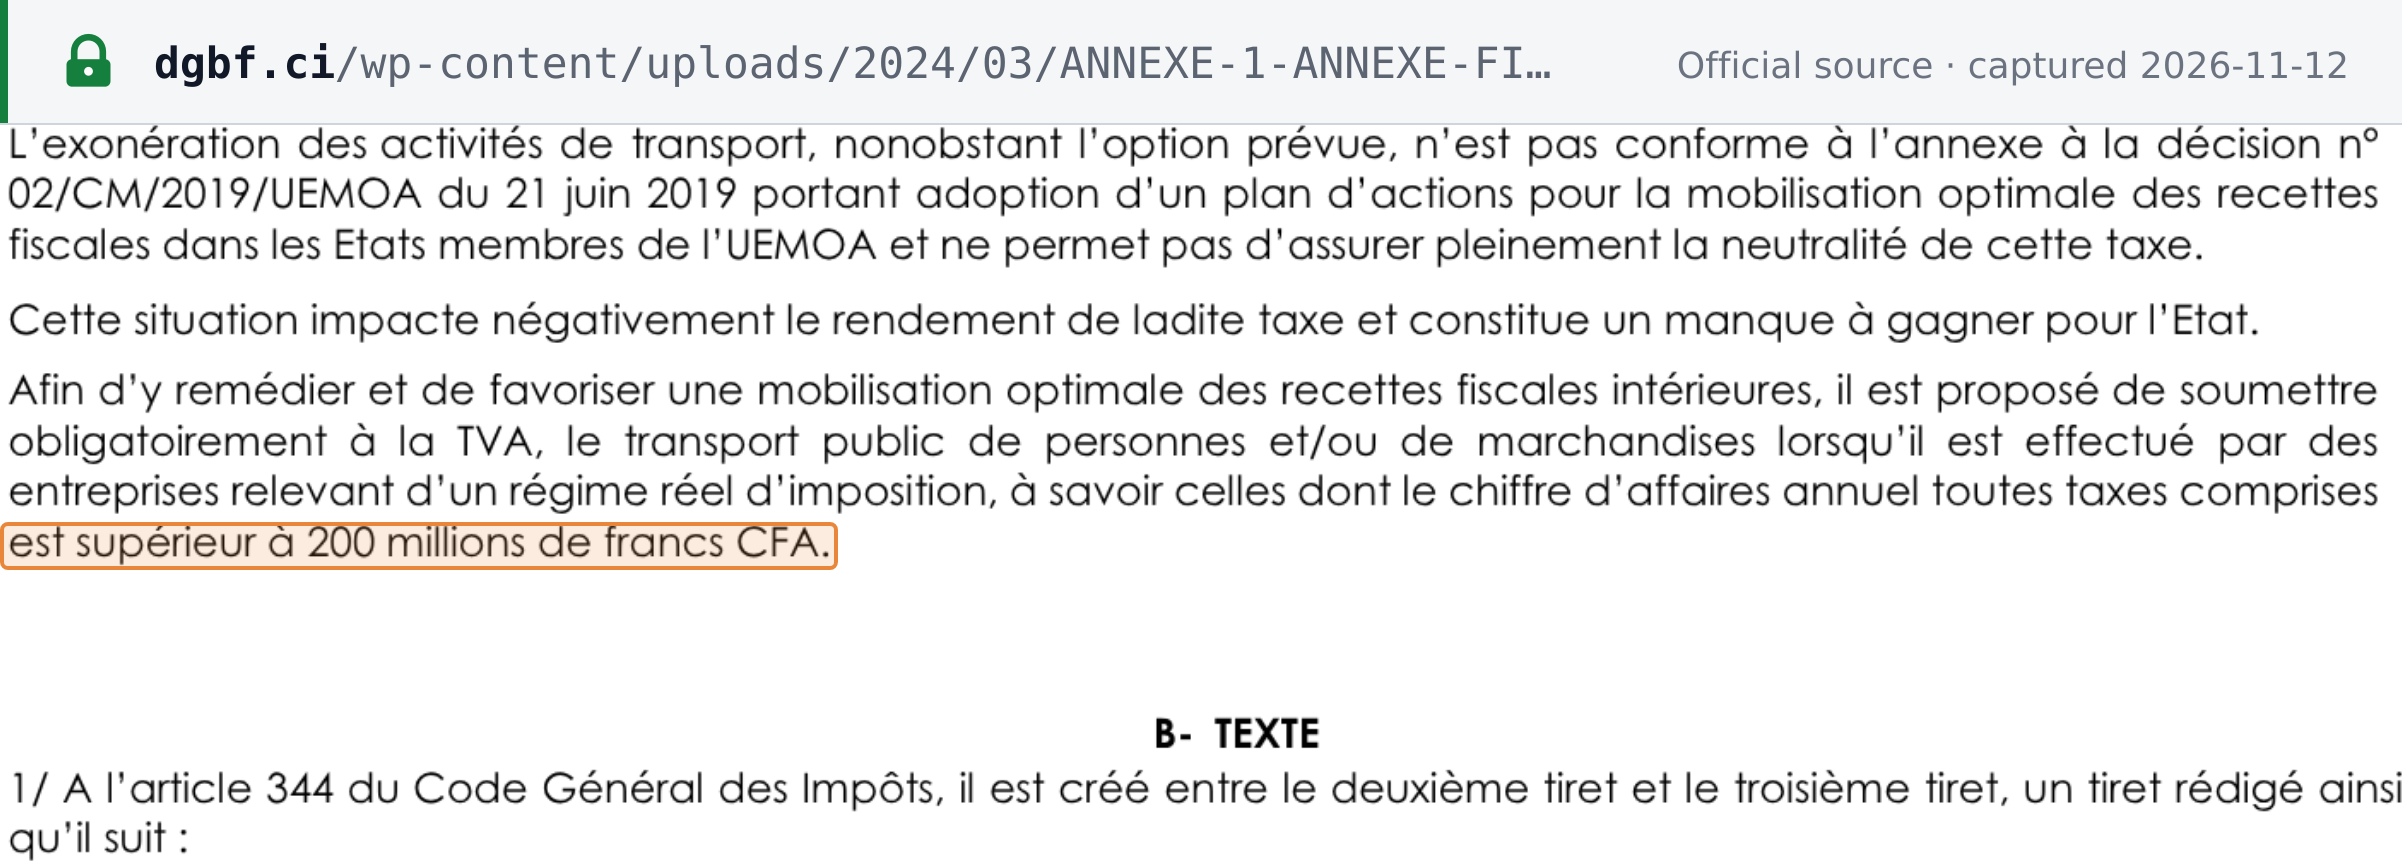 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Loi de finances n° 2023-1000 du 18 décembre 2023 portant budget de l’Etat pour l’année 2024, Annexe 1 : Annexe fiscale · www.dgbf.ci