Czech Republic exempts books from VAT with the right to deduct from 1 January 2024
This page records one dated change. For the rules in Czech Republic as they stand today, see the Czech Republic guide →
- Jurisdiction
- Czech Republic
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 12 December 2023
- Effective
- 1 January 2024
- Authority
- Generální finanční ředitelství (General Financial Directorate), Czech Republic
- Verified
- Fetched from official source · high confidence
Czech VAT payers selling printed books and other printed matter, or supplying e-books for download, by e-mail or for online reading, including lending and rental.
No action — historical reference. Books and printed publications are zero-rated in the Czech Republic from 1 January 2024.
Zákon č. 349/2023 Sb. (published 12 December 2023), effective 1 January 2024, moved the supply of books from the abolished 10% second reduced VAT rate to an exemption with the right to deduct input VAT (§ 71i of the VAT Act). This works as a zero rate. It covers printed books and other printed matter, and 'services similar to the supply of books' such as e-books supplied for download, by e-mail or for online reading, including lending and rental. Newspapers and periodicals fall under the single 12% reduced rate.
What changed in detail
Act No. 349/2023 Sb., published on 12 December 2023, abolished the Czech 10% second reduced VAT rate from 1 January 2024. Books, which had been taxed at that rate, did not move to the new 12% rate. Instead the Act inserted § 71i into the VAT Act, which exempts the supply of books from VAT with the right to deduct input tax. Legally this is an exemption, not a 0% rate, though it has the same economic effect.
According to the GFŘ’s Information on VAT rate changes from 1 January 2024, section 4, the exemption covers:
- printed books and other printed matter;
- services defined in § 71i(2) as similar to the supply of books, typically e-books for download, sent by e-mail or made available for online reading, including lending and rental.
The GFŘ also states:
- The exemption extends to incidental costs under § 36(4), mainly packaging and transport.
- It applies under the special margin scheme of § 90.
- Exempt supplies are reported on line 26 of the VAT return.
- Under § 71i(3), the exemptions in § 51, § 64, § 66 and § 71h take precedence, and so does § 61, so those supplies stay exempt without the right to deduct.
Newspapers and periodicals were not moved into § 71i. They take the single 12% reduced rate.
What it means
The § 71i exemption is still in force. A bookseller charges no VAT but keeps its input-tax deduction. Because the supply is an exemption rather than a rate, it is reported as an exempt supply with the right to deduct, on line 26 of the return. A system set up with a “0%” rate for books should be checked against that.
For the rest of the rate reform, see the consolidation into a single 12% rate.
Proof
Od daně s nárokem na odpočet daně je nově osvobozeno dodání knih a poskytnutí obdobných služeb za podmínek vymezených v § 71i zákona o DPH. Tímto dochází k přesunu daných plnění ze zdanitelných plnění ve druhé snížené sazbě daně do plnění osvobozených od daně s nárokem na odpočet daně.The supply of books and the provision of similar services are newly exempt with the right to deduct, under the conditions of § 71i of the VAT Act. These supplies thus move from taxable supplies at the second reduced rate to supplies exempt with the right to deduct.
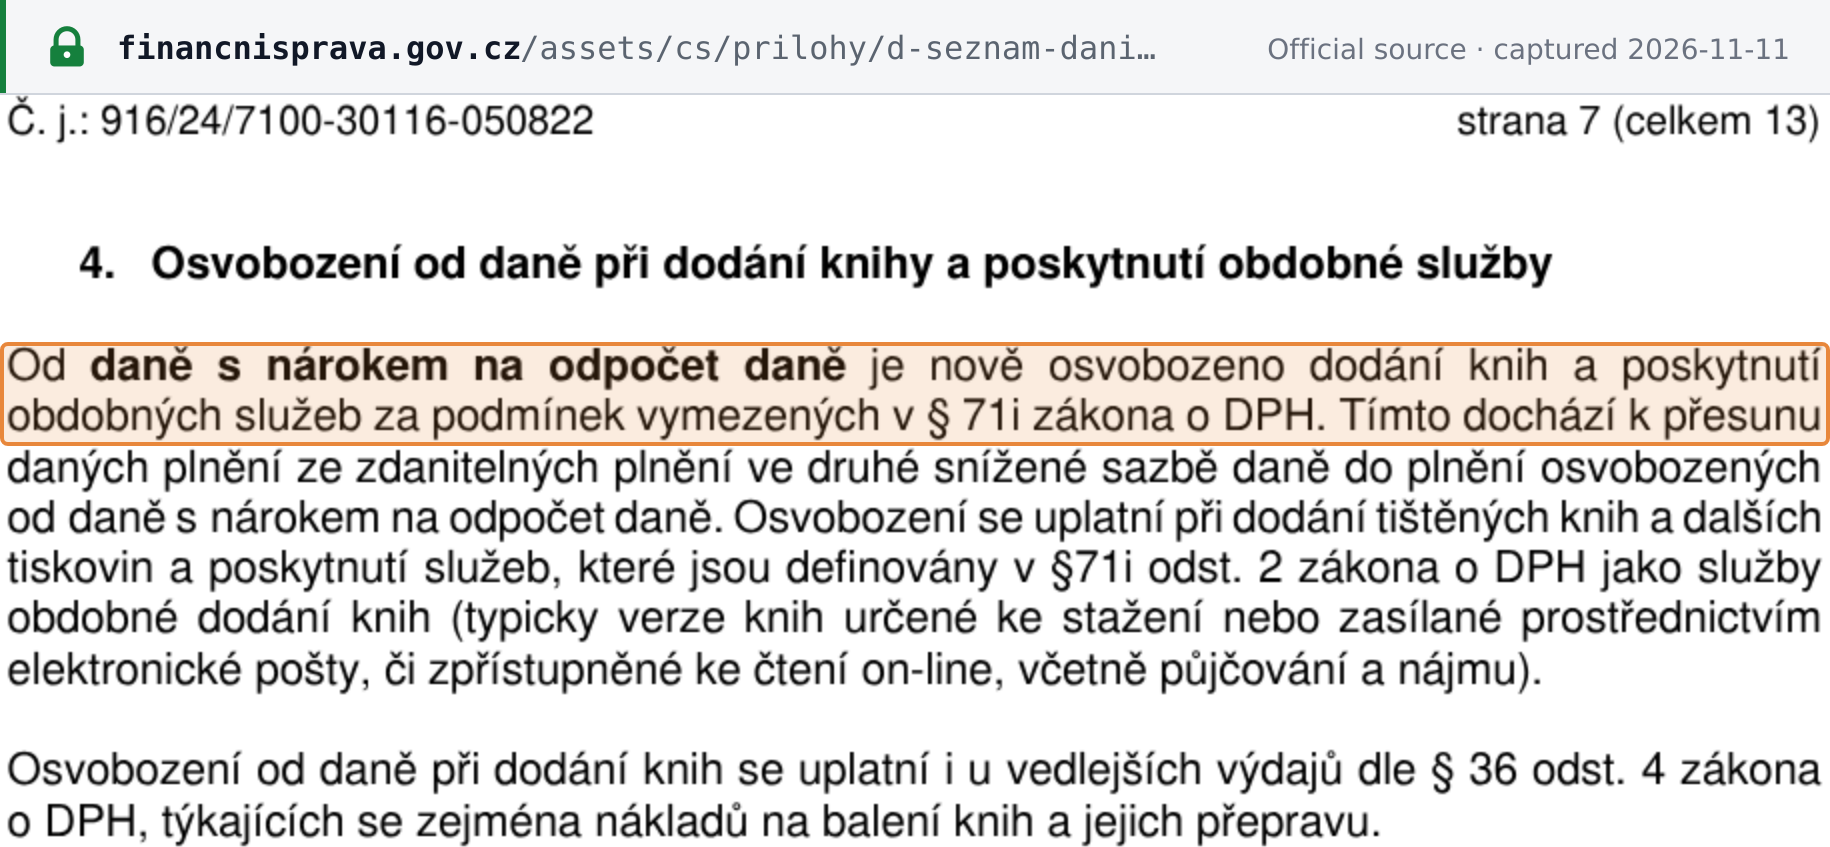 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Informace GFŘ ke změnám sazeb DPH od 1. 1. 2024, Č. j. 916/24/7100-30116-050822 (Generální finanční ředitelství), section 4 · financnisprava.gov.cz