Ecuador raises its general IVA rate to 13% and lets the President set it anywhere from 13% to 15%
This page records one dated change. For the rules in Ecuador as they stand today, see the Ecuador guide →
- Jurisdiction
- Ecuador
- Tax
- IVA
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 12 March 2024
- Effective
- 1 April 2024
- Authority
- Asamblea Nacional del Ecuador
- Verified
- Fetched from official source · medium confidence
All IVA-registered suppliers and importers in Ecuador; a separate 5% rate applies to construction materials and inputs.
No action — historical reference. This law established the legal band (13-15%) that enabled Decree 198 to raise the rate to 15%.
The Ley Orgánica para Enfrentar el Conflicto Armado Interno, la Crisis Social y Económica (Suplemento del Registro Oficial 516, 12 March 2024) permanently raised Ecuador's general IVA rate from 12% to 13%. It allows the President, after a favourable opinion from the Ministry of Finance, to set the general rate between 13% and 15% by executive decree. The law's IVA rate provisions (including 5% on construction materials) applied from 1 April 2024.
What changed in detail
The Ley Orgánica para Enfrentar el Conflicto Armado Interno, la Crisis Social y Económica was published on 12 March 2024 in the Suplemento del Registro Oficial No. 516.
It set Ecuador’s general IVA rate at 13%, up from 12%, and wrote a new power into the law: based on public-finance and balance-of-payments conditions, the President may modify the general IVA rate after a favourable opinion from the governing body of public finances (the Ministry of Economy and Finance). In no case may the rate be lower than 13% or higher than 15%, except as the law itself provides. The Ministry describes the increase as three points in total: one permanent point (12% to 13%) and two temporary points within the executive’s competence.
The same law introduced a differentiated 5% IVA rate for materials and inputs used in construction and real-estate development. Its other fiscal measures were outside IVA: the currency-outflow tax (ISD) rose to 5%, a one-off 3.25% security contribution applied to 2022 taxable profits, and a temporary contribution of 5% to 25% applied to the profits of banks and savings cooperatives.
According to the SRI, the law’s IVA rate provisions, including the 5% construction rate, apply from 1 April 2024.
What it means
This law created the 13–15% band. The 15% rate itself came from a decree: Decreto Ejecutivo 198 applied it for 2024, and Decreto Ejecutivo 470 kept it for 2025. An SRI circular of 2 April 2026 (NAC-DGECCGC26-00000005) still calls 15% the rate in force.
The band is still law, so the general rate can move anywhere between 13% and 15% by executive decree, without a new statute. Invoicing and ERP systems should treat the general rate as a parameter that can change at short notice. The pre-2024 12% rate is gone: 13% is now the floor.
Proof
En ningún caso la tarifa podrá ser inferior al 13% ni mayor al 15%, salvo las excepciones previstas en esta ley.In no case may the rate be lower than 13% or higher than 15%, save for the exceptions provided in this law.
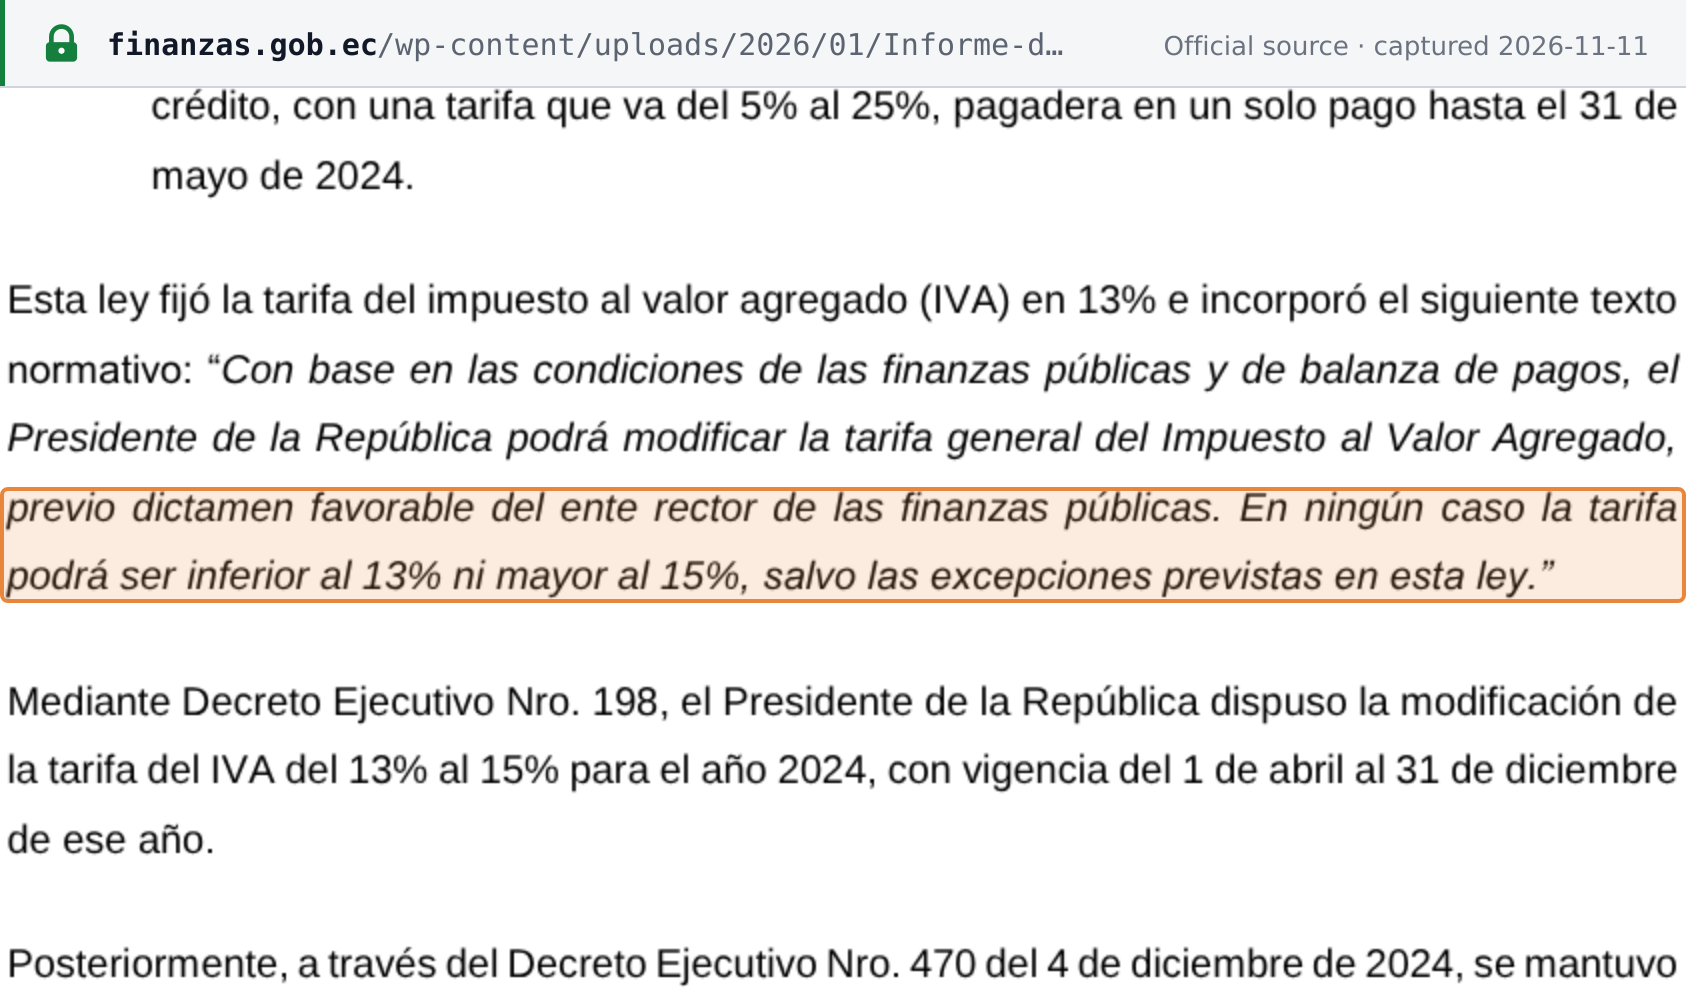 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Ministerio de Economía y Finanzas — Informe de Seguimiento al Plan de Fortalecimiento y Sostenibilidad Fiscal, julio 2025 (p. 6) · www.finanzas.gob.ec