Estonia repeals the Security Tax Act, cancelling the planned 2029 return of VAT to 22% and keeping the 24% rate
This page records one dated change. For the rules in Estonia as they stand today, see the Estonia guide →
- Jurisdiction
- Estonia
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 8 July 2025
- Effective
- 18 July 2025
- Instrument
- EE-ACT-RT-I-08-07-2025-1
- Authority
- Riigi Teataja
- Verified
- Fetched from official source · high confidence
All VAT-registered businesses in Estonia charging the standard rate, and anyone pricing contracts or systems that assumed a return to 22% in 2029.
No action — monitoring only. The 24% standard VAT rate is now permanent until further legislation.
Ettevõtlustulu lihtsustatud maksustamise seaduse ja tulumaksuseaduse muutmise ning julgeolekumaksu seaduse kehtetuks tunnistamise seadus, adopted by the Riigikogu on 18 June 2025, proclaimed 26 June 2025 (President's Resolution No. 575), published RT I, 08.07.2025, 1, in force 18 July 2025 (§ 2, by the general rule of 10 days after publication): repealed the Security Tax Act (Julgeolekumaksu seadus, RT I, 02.01.2025, 2). The Security Tax Act's § 21 had scheduled Estonia's standard VAT rate to return from 24% to 22% on 1 January 2029; that provision never entered into force and the 24% rate from 1 July 2025 has no statutory end date.
What changed in detail
The Ettevõtlustulu lihtsustatud maksustamise seaduse ja tulumaksuseaduse muutmise ning julgeolekumaksu seaduse kehtetuks tunnistamise seadus was adopted by the Riigikogu on 18 June 2025, proclaimed by the President on 26 June 2025 (Resolution No. 575) and published as RT I, 08.07.2025, 1.
Its § 2 repeals the Julgeolekumaksu seadus (Security Tax Act, RT I, 02.01.2025, 2). Under § 4(2), § 2 takes effect in the ordinary way, ten days after publication, but not before 2 July 2025, so the repeal took effect on 18 July 2025. The same Act’s §§ 1 and 3, which change income tax rates, take effect on 1 January 2026.
The Security Tax Act had amended the VAT Act through its § 21. Points 1, 3 and 5, which raised the standard rate from 22% to 24%, took effect on 1 July 2025 and are already part of the VAT Act. Points 2 and 4, which would have brought the rate back from 24% to 22%, were due on 1 January 2029. Repealing the Security Tax Act before that date means those points never enter into force.
What it means
The repeal is in force, and its effect is that Estonia’s 24% standard VAT rate has no end date. The rate rise itself is recorded separately (Estonia raises VAT to 24%); this record is why that rate is no longer temporary.
Anything built on the 2029 cut needs correcting: rate tables, long-term contracts with VAT-inclusive prices, and price forecasts. A future return to 22% would now need a new act of the Riigikogu.
Proof
Julgeolekumaksu seadus (RT I, 02.01.2025, 2) tunnistatakse kehtetuks.The Security Tax Act (RT I, 02.01.2025, 2) is repealed.
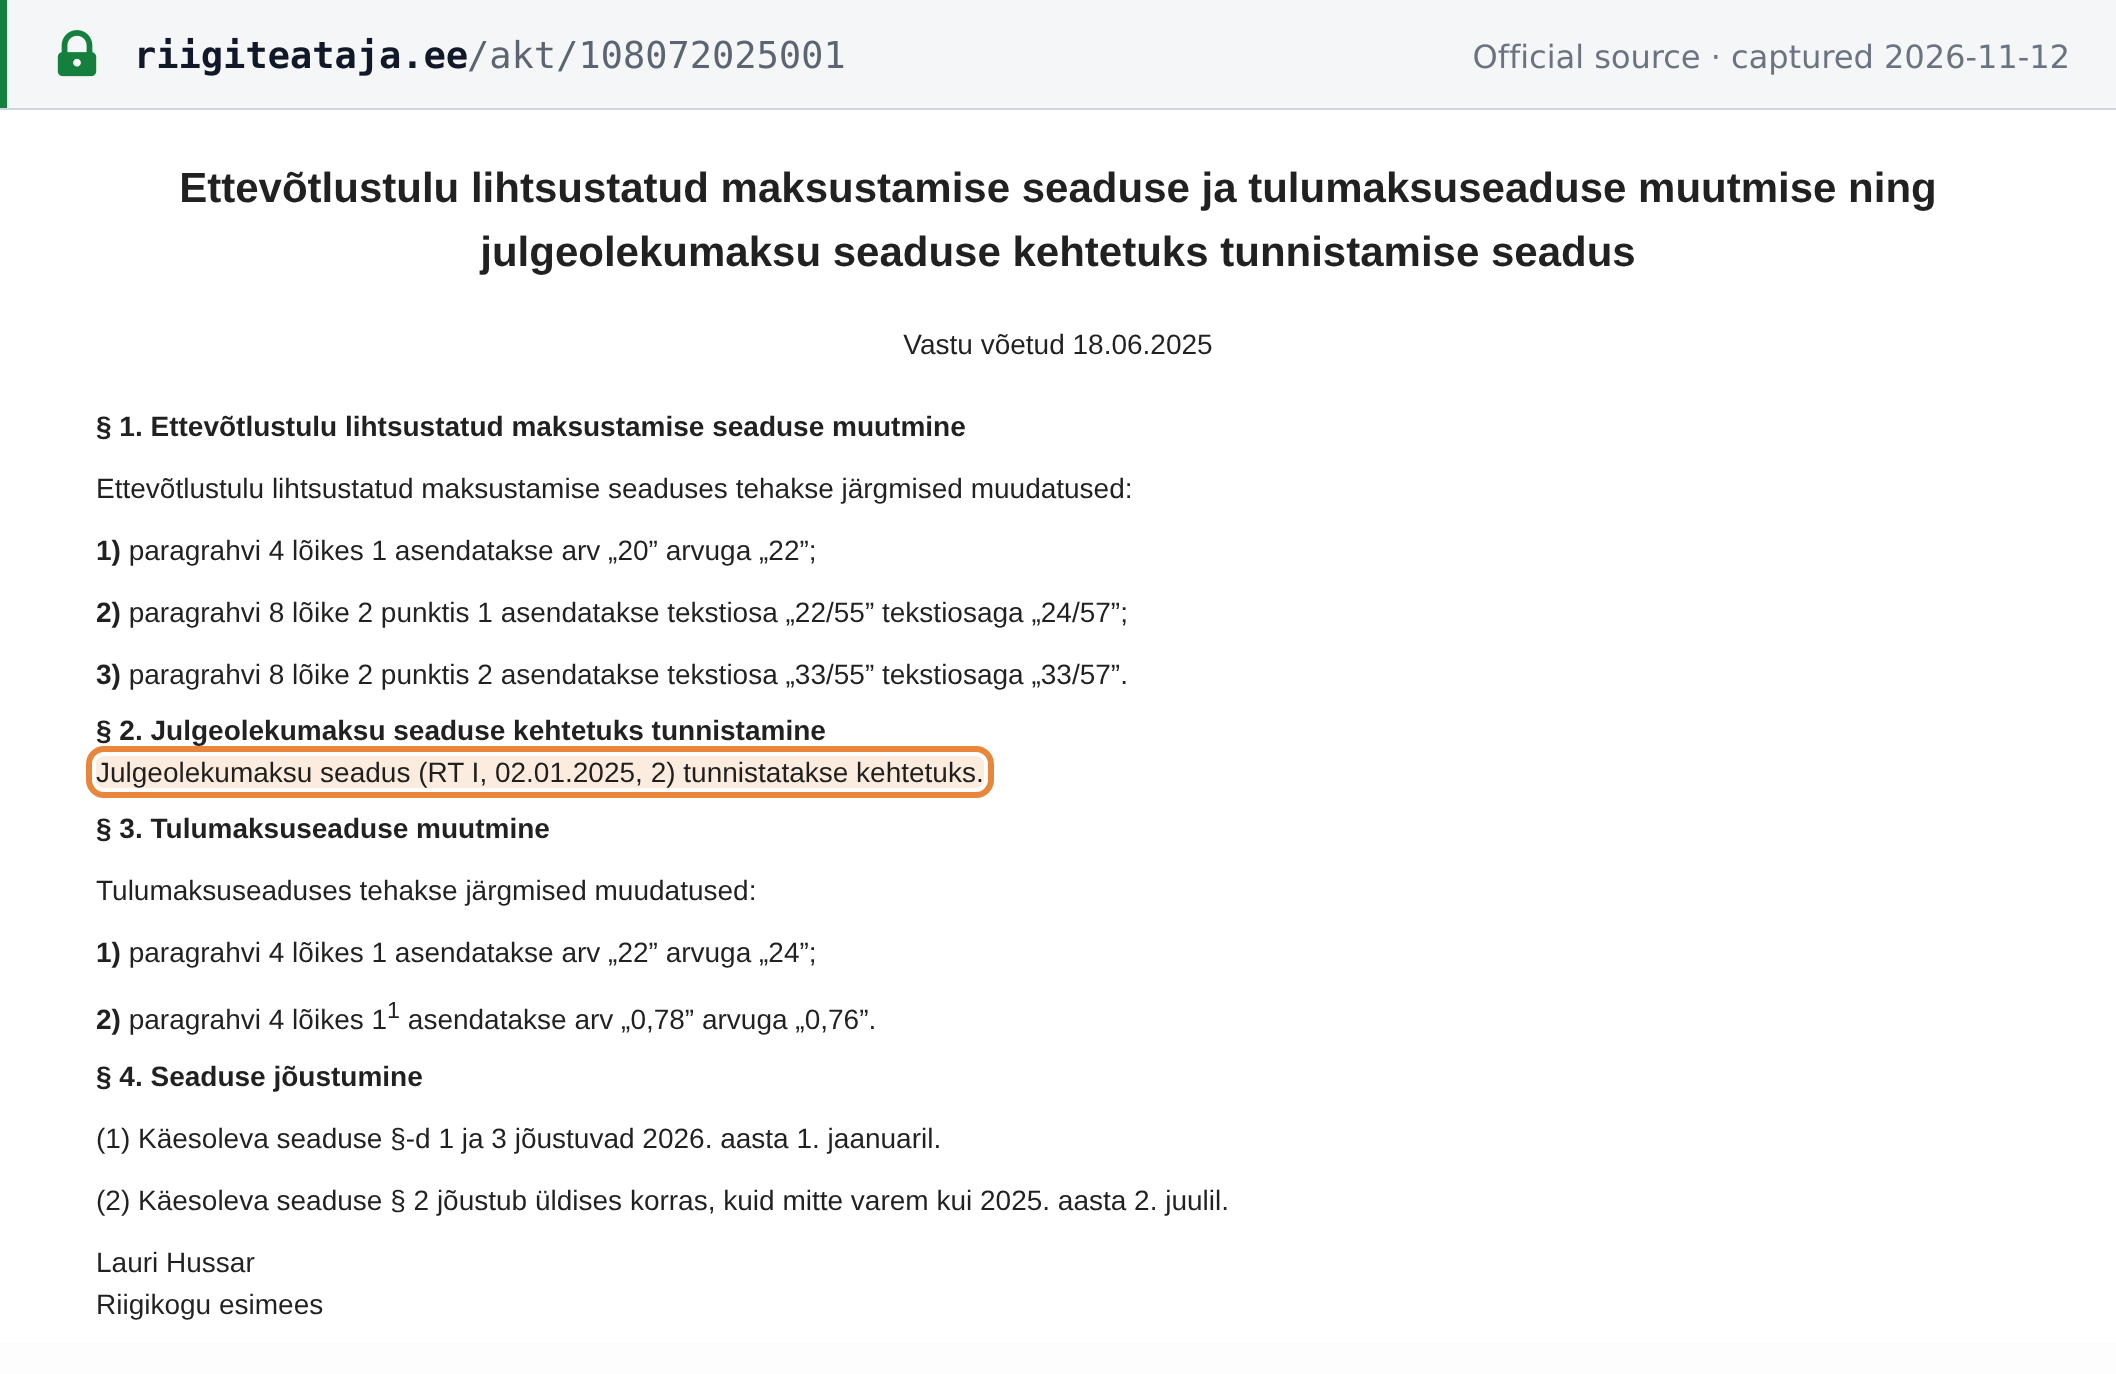 Source snapshot of the official page. Open full size ↗