Estonia’s Riigikogu passes the ViDA VAT Act amendments (992 SE): monthly VAT periods only, wider OSS from 2027 and 1 July 2028
This page records one dated change. For the rules in Estonia as they stand today, see the Estonia guide →
- Jurisdiction
- Estonia
- Tax
- VAT
- Change type
- Registration
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 12 November 2026
- Effective
- 1 January 2027
- Authority
- Riigikogu
- Systems
- Tax engine, Reporting
- Verified
- Fetched from official source · high confidence
Estonian businesses using the One Stop Shop for cross-border B2C sales, suppliers of gas, electricity, heating and cooling to consumers in other Member States, online marketplace and accommodation-booking platforms, and taxpayers using a VAT period longer than a month.
Businesses filing Estonian VAT returns for periods longer than a month, energy suppliers selling cross-border to consumers, and platforms: prepare for the 2027 changes and the 1 July 2028 OSS extension once the Act is proclaimed.
Tax engineReporting
Estonia's Riigikogu passed the Act on Amendments to the Value-Added Tax Act (992 SE) on 11 November 2026, with 58 members in favour. The Act transposes EU VAT Directive (ViDA) amendments: from 2027 the special scheme for distance sales extends to natural gas transmitted via the network and to electrical, thermal and cooling energy; from 1 July 2028 it may be used for goods sold at trade fairs, exhibitions and markets, goods requiring installation or assembly, and sales on board watercraft or aircraft. From 1 July 2028 it also taxes online marketplace services supplied to non-taxable customers where the underlying transaction takes place. It removes the option of a VAT taxable period longer than a calendar month, raises the exempt threshold for goods transferred for advertising purposes from EUR 10 to EUR 21, and exempts therapeutic services by qualified specialists outside a licensed healthcare facility.
What changed in detail
At its sitting that began on 11 November 2026, the Riigikogu passed the Act on Amendments to the Value-Added Tax Act (992 SE), initiated by the Government, with 58 members in favour. The Act still has to be proclaimed by the President and published in Riigi Teataja before it becomes law.
The Act transposes amendments to the EU VAT Directive from the VAT in the Digital Age (ViDA) package. According to the Riigikogu’s announcement of 12 November 2026, it:
- extends the special scheme for distance sales (One Stop Shop) from 2027 to natural gas transmitted via the network and to electrical, thermal and cooling energy;
- from 1 July 2028, allows the scheme to be used more broadly for sales of goods to consumers in another Member State, for example at trade fairs, exhibitions and markets, for goods requiring installation or assembly, and for sales on board watercraft or aircraft;
- from 1 July 2028, makes the place of supply of an online marketplace service supplied to a non-taxable customer the place where the underlying transaction takes place, so that an accommodation-booking platform’s service is taxed where the accommodation is provided rather than in the client’s country of residence;
- removes the option of a VAT taxable period longer than a calendar month;
- raises the exempt threshold for goods transferred for advertising purposes from EUR 10 to EUR 21.
A second-reading amendment exempts therapeutic services by qualified specialists from VAT even when they are provided outside a healthcare facility holding an operating licence.
What it means
The change most Estonian businesses will notice is the end of longer-than-monthly VAT periods: anyone filing on a longer cycle needs to move to monthly returns. Energy suppliers selling to consumers abroad can report through OSS from 2027 instead of registering in each country, and the 1 July 2028 extensions spare more goods sellers foreign registrations. Platforms need to re-map the place of supply for their own commission. The exact start dates for each item are fixed in the Act as published, so check Riigi Teataja once it is proclaimed.
Proof
From 1 July 2028, the special scheme may be used more broadly for the sale of goods to consumers in another Member State, for example, for sales of goods at trade fairs, exhibitions, and markets; for the sale of goods that require installation or assembly; and for sales taking place on board watercraft or aircraft.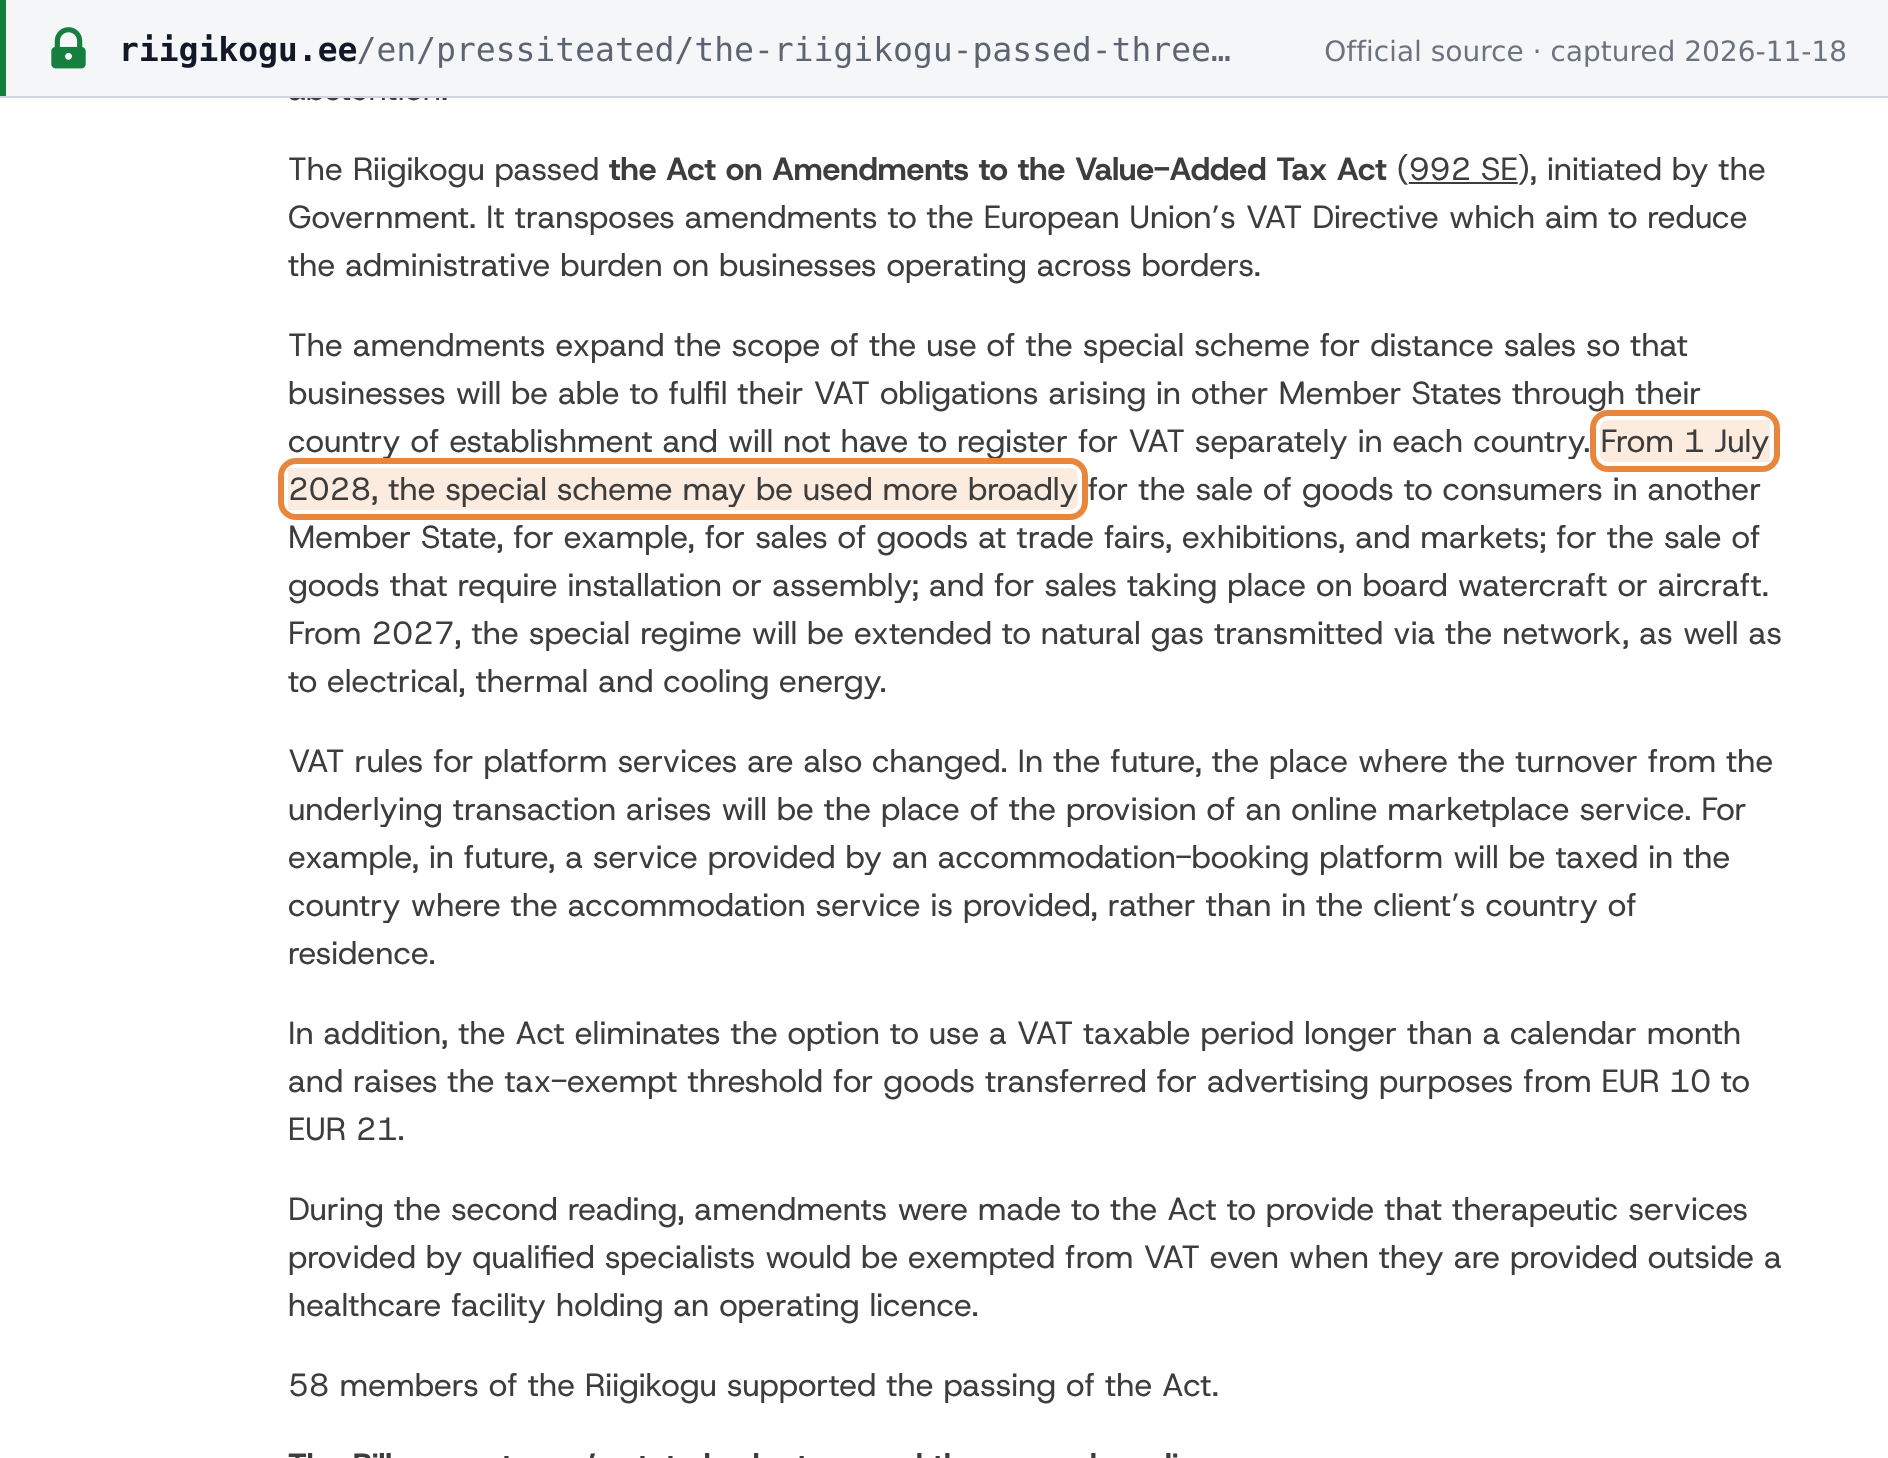 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Estonian ViDA bill 992 SE passes first reading; amendments due 12 October 2026 effective 1 January 2027