EAEU applies destination VAT to cross-border electronic services between member states from 4 March 2024
- Jurisdiction
- Eurasian Economic Union
- Tax
- VAT
- Change type
- Digital services
- Status
- In force
- Impact
- FYI
- Announced
- 4 March 2024
- Effective
- 4 March 2024
- Instrument
- EAEU-TREATY-PROTOCOL-Protocol-of-9-December-2022
- Authority
- Official Internet Portal of Legal Information (publication.pravo.gov.ru)
- Verified
- Fetched from official source · high confidence
Businesses in Armenia, Belarus, Kazakhstan, Kyrgyzstan or Russia supplying listed electronic services to buyers in another EAEU member state, and business buyers of those services.
No action — rules in force since 4 March 2024; businesses supplying e-services across EAEU borders should check whether the buyer's state requires them to register there or leaves the VAT to business buyers.
In force from 4 March 2024: the Protocol of 9 December 2022 amending the Treaty on the Eurasian Economic Union (signed in Bishkek by all five member states) applies destination-based VAT to cross-border supplies of electronic services within the EAEU, to businesses and consumers alike. A seller in one member state supplying listed e-services to a buyer in another must register and pay VAT there. The seller registers for VAT only where the buyer's state requires it; where that state does not, a business buyer (an organisation or individual entrepreneur) pays the VAT. The EEC Council approved the list of 14 covered services on 27 September 2023. The Protocol entered into force on 4 March 2024, when the depositary received the last ratification notice. Russia published it officially on 25 March 2024.
What changed in detail
The Protocol of 9 December 2022 amending the Treaty on the Eurasian Economic Union of 29 May 2014 sets the procedure for levying indirect taxes on services supplied in electronic form between member states. It was signed in Bishkek by all five members: Armenia, Belarus, Kazakhstan, Kyrgyzstan and Russia. Under its Article 2 it entered into force when the depositary received the last notification of ratification, which was 4 March 2024. Russia ratified it by Federal Law No. 328-FZ of 24 July 2023 and published it officially on 25 March 2024.
The annexed procedure taxes listed e-services where the buyer is:
- B2C (point 9). A seller of one member state supplying e-services to individuals located in another must register with that state’s tax authority, through its online registration resource or, where that state’s law allows, by conditional registration, and pay the VAT there.
- B2B (point 10). A seller supplying organisations or individual entrepreneurs in another member state registers there if that state’s law requires it. If it does not, the buyer organisations and individual entrepreneurs calculate and pay (withhold) the VAT themselves. Individuals never account for it.
- Covered services. The services are those on a list approved by the Council of the Eurasian Economic Commission; the Council approved a list of 14 services on 27 September 2023.
What it means
The rule has been in force since March 2024 and remains the EAEU framework for intra-union digital services. In practice a seller in one member state supplying a listed e-service to consumers in another registers and pays VAT in the consumer’s state. For B2B sales, whether the seller registers or the buyer self-accounts depends on each destination state’s domestic law, so the answer differs by country. Note that the in-force date is 4 March 2024: the protocol itself sets no later application date. Member states’ own platform and e-commerce VAT changes since 2024 sit alongside this protocol rather than amending it.
Proof
(ратифицирован Федеральным законом от 24 июля 2023 года № 328-ФЗ, вступил в силу для Российской Федерации 4 марта 2024 года)(ratified by Federal Law No. 328-FZ of 24 July 2023; entered into force for the Russian Federation on 4 March 2024)
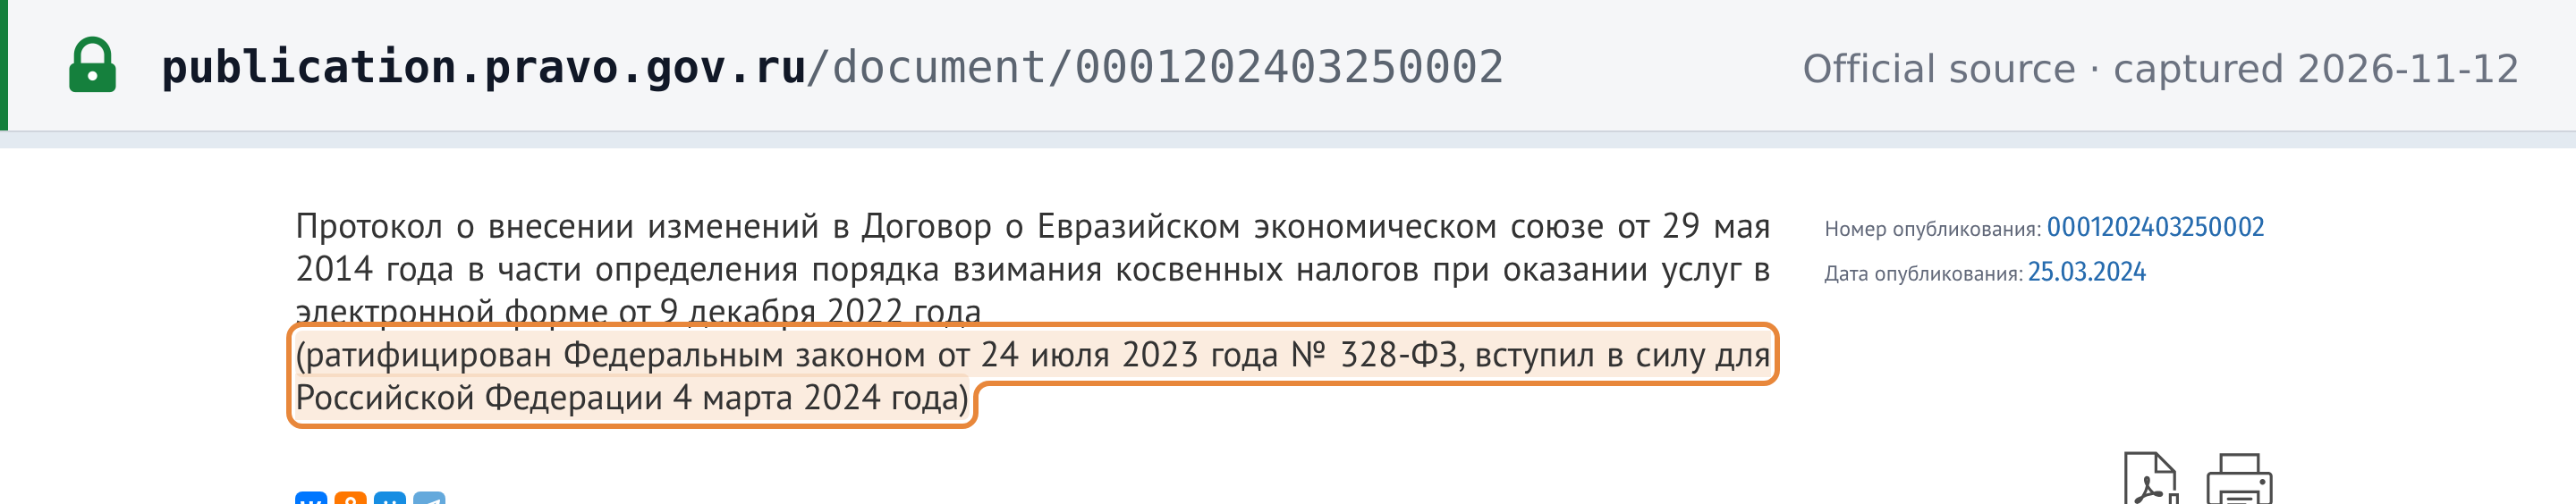 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Протокол от 9 декабря 2022 года о внесении изменений в Договор о ЕАЭС (услуги в электронной форме), номер опубликования 0001202403250002, 25.03.2024 · publication.pravo.gov.ru
9. В целях уплаты НДС налогоплательщик одного государства-члена, оказывающий услуги в электронной форме физическим лицам, местом осуществления деятельности которых признана территория другого государства-члена, подлежит постановке на учет в налоговом органе этого другого государства-члена, за исключением случаев, предусмотренных пунктом 11 настоящего Порядка.9. For the purposes of paying VAT, a taxpayer of one member state supplying services in electronic form to individuals whose place of activity is recognised as the territory of another member state is subject to registration with the tax authority of that other member state, except in the cases provided for in point 11 of this Procedure.
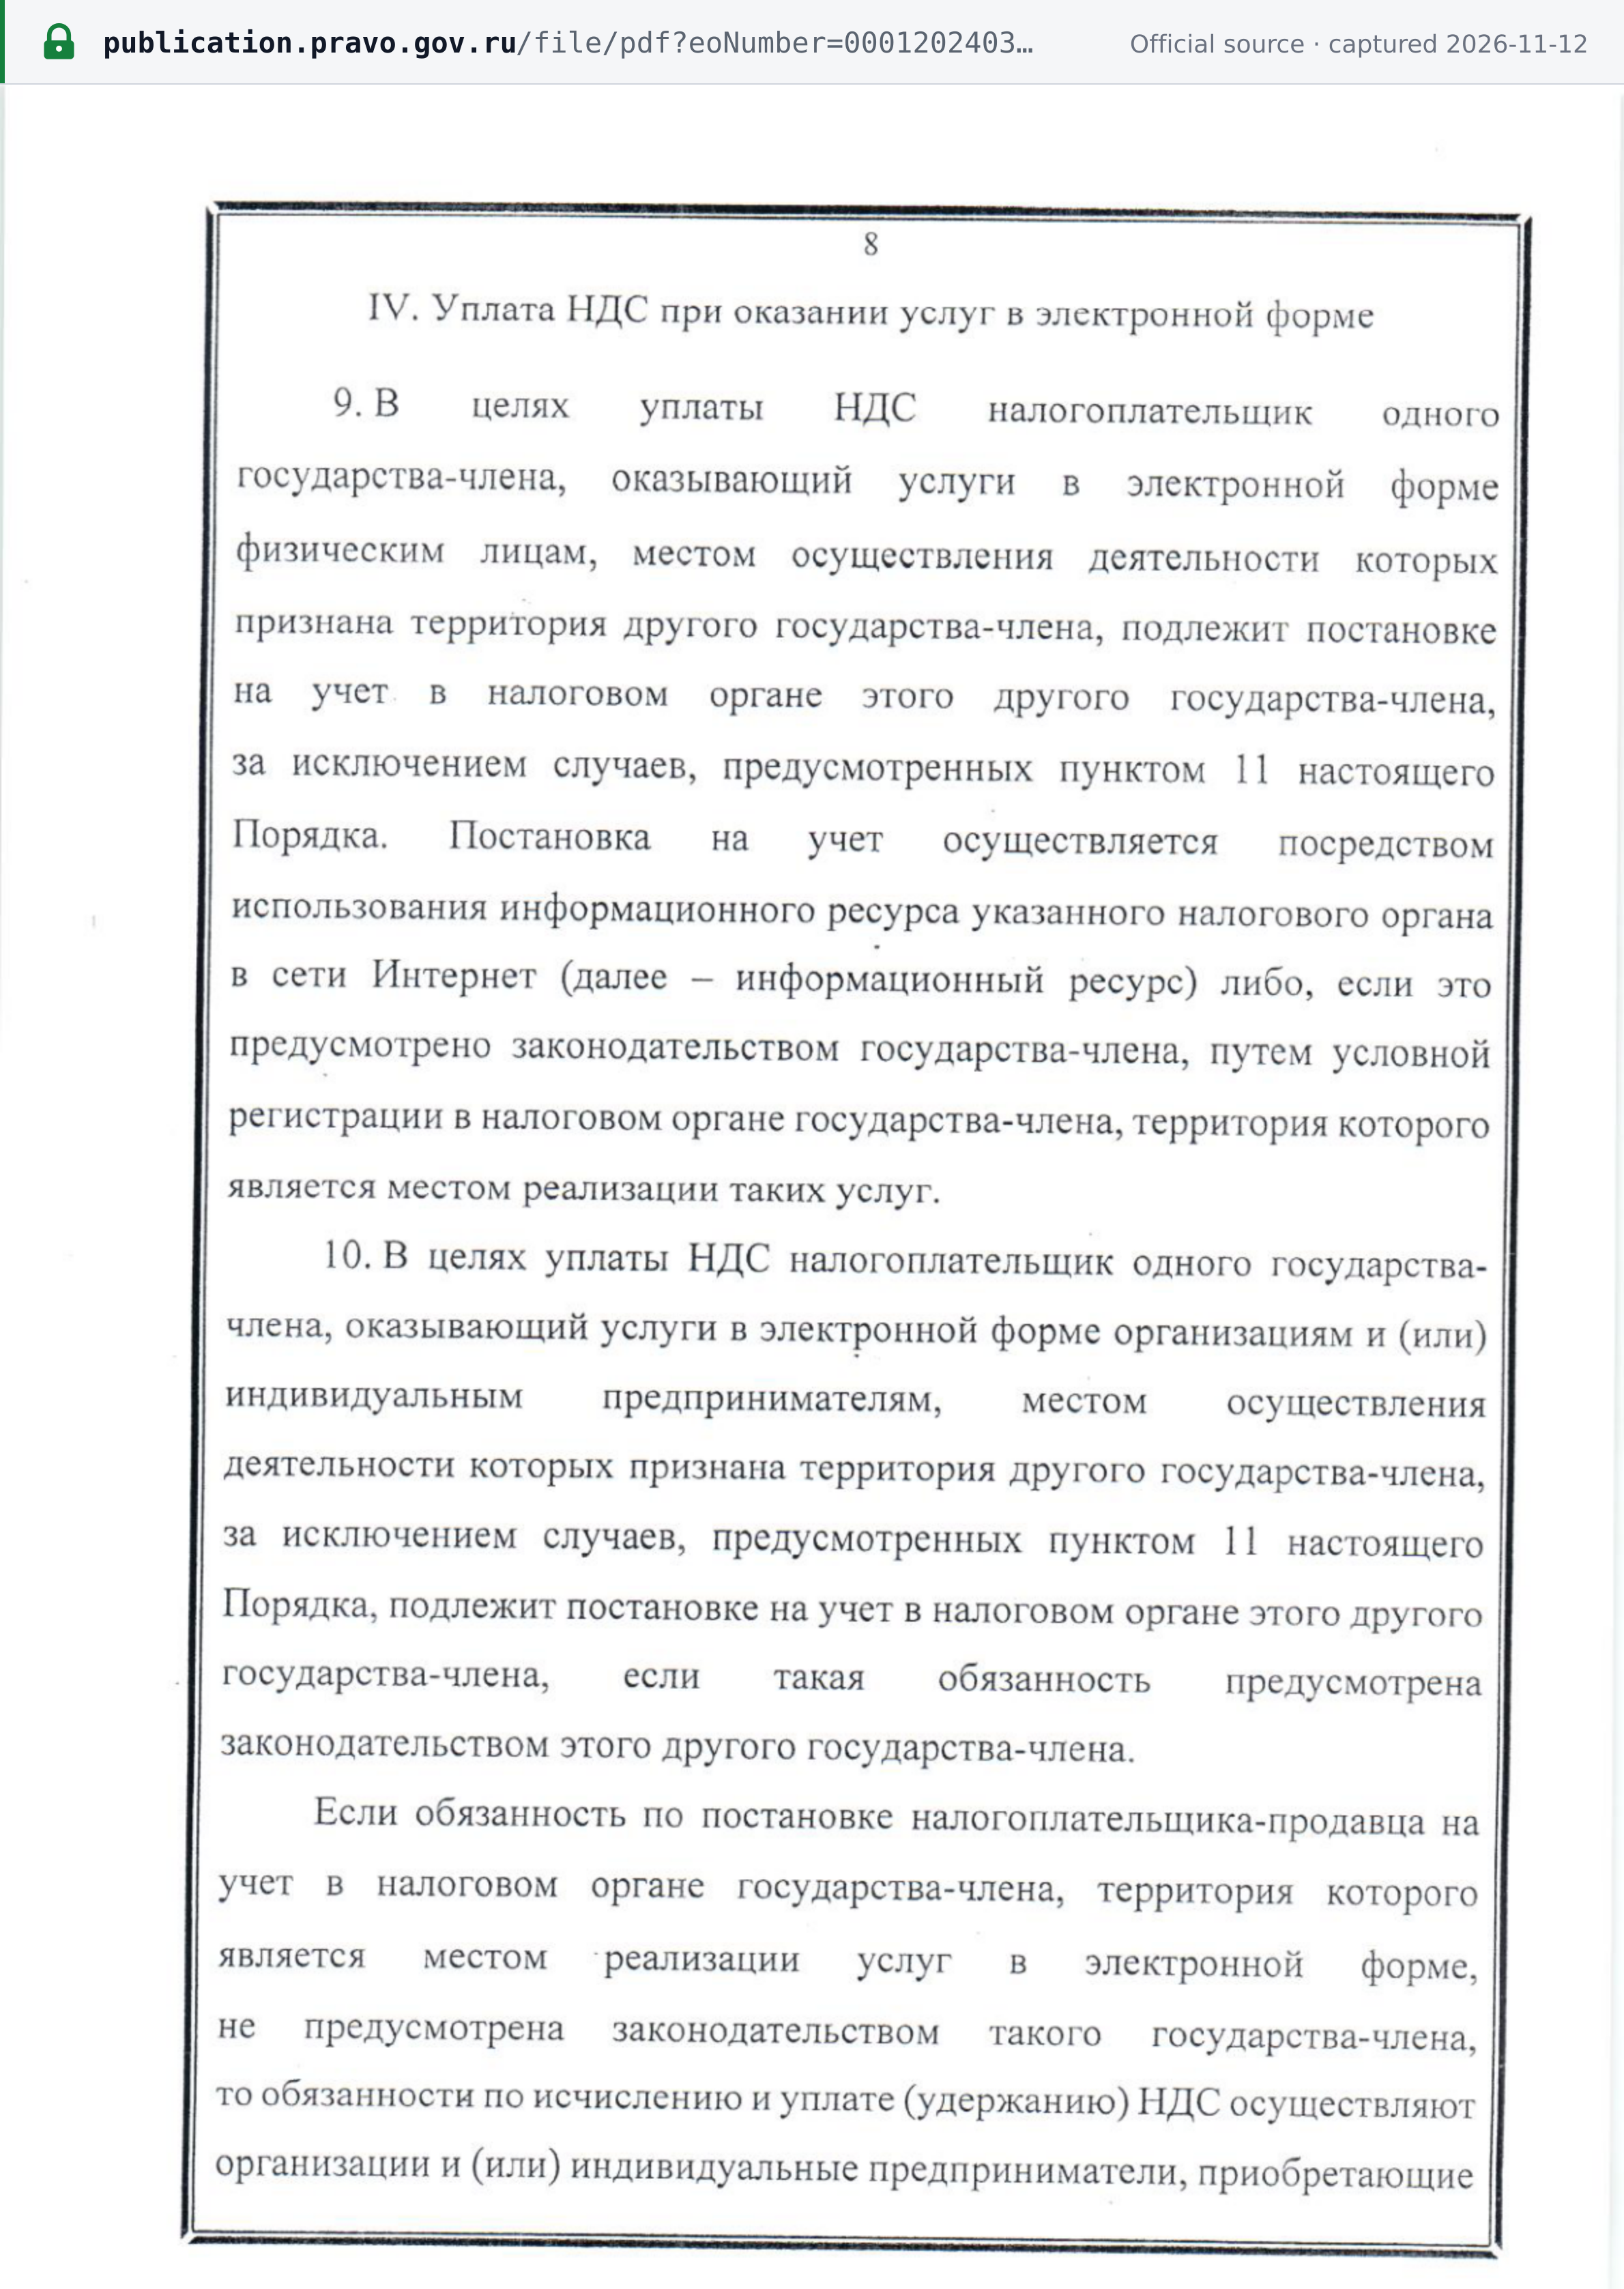 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Протокол от 9 декабря 2022 года о внесении изменений в Договор о ЕАЭС (услуги в электронной форме), номер опубликования 0001202403250002, 25.03.2024 · publication.pravo.gov.ru