Finland moves most 10% VAT items to the 14% reduced rate from 1 January 2025
This page records one dated change. For the rules in Finland as they stand today, see the Finland guide →
- Jurisdiction
- Finland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 9 December 2024
- Effective
- 1 January 2025
- Instrument
- FI-ACT-691-2024
- Authority
- Finlex (Finnish Ministry of Justice statute database, run by Oikeusrekisterikeskus)
- Verified
- Fetched from official source · high confidence
Finnish suppliers of passenger transport, accommodation, reimbursable medicines, books, sports and cultural admissions, performers' fees, certain works of art and collective copyright compensation, plus menstrual, incontinence and diaper products.
No action — monitoring only. The 14% reduced rate was superseded by the 13.5% rate from 1 January 2026 under Law 1358/2025.
Law 691/2024 (Laki arvonlisäverolain muuttamisesta), adopted on 5 December 2024 on government bill HE 141/2024 vp and published in the Finnish Statute Book on 9 December 2024, amends section 85 of the Value Added Tax Act 1501/1993 so that, from 1 January 2025, most goods and services previously taxed at 10% move to the 14% reduced rate: passenger transport; accommodation and visitor-harbour berths; reimbursable medicines; physical and electronic books; admission to sports events and use of sports facilities and lessons; admission to cultural events and venues (including streaming of them); performers' fees; certain works of art; and copyright compensation collected by collecting societies. Menstrual protection, incontinence products and children's diapers move from 25.5% to 14%. Newspapers and magazines and the state funding of public broadcasting remain at 10%.
What changed in detail
Law 691/2024 (Laki arvonlisäverolain muuttamisesta) was adopted on 5 December 2024 on government bill HE 141/2024 vp and published in the Finnish Statute Book on 9 December 2024. It rewrites section 85 of the Value Added Tax Act (1501/1993) and replaces section 85 a, with effect from 1 January 2025.
New points 4 to 12 of section 85(1) move these supplies to the 14% reduced rate:
- passenger transport;
- accommodation and visitor-harbour berths;
- reimbursable medicines;
- books on a physical medium or supplied electronically;
- admission to sports events and use of sports facilities and lessons, including streaming;
- admission to performances, theatres, concerts, museums, cinemas, exhibitions and similar cultural events and venues, including streaming;
- performers’ and athletes’ fees;
- certain works of art;
- copyright compensation received by collecting societies.
Point 6 also brings menstrual protection, incontinence products and children’s diapers into 14%, from the general 25.5% rate.
The new section 85 a keeps 10% for newspapers and magazines, physical or electronic, and for the state funding of Yleisradio and Ålands Radio och TV.
Publications consisting mainly of advertising, video or music are excluded from both the book rate and the 10% rate.
What it means
This 14% rate is spent. Law 1358/2025 lowered it to 13.5% from 1 January 2026, and the same list of goods and services now sits at 13.5%. The reclassification this law made still stands: books, medicines, transport, accommodation, culture and sport did not return to 10%. Invoices for 2025 supplies of these items should show 14%. Those from 2026 onwards should show 13.5%, with the general rate still at 25.5%.
Proof
Seuraavien palvelujen myynnistä sekä seuraavien tavaroiden myynnistä, yhteisöhankinnasta, siirrosta varastointimenettelystä ja maahantuonnista suoritettava vero on 14 prosenttia veron perusteesta:The tax payable on sales of the following services and on sales, intra-Community acquisitions, removals from warehousing and imports of the following goods is 14 per cent of the tax base:
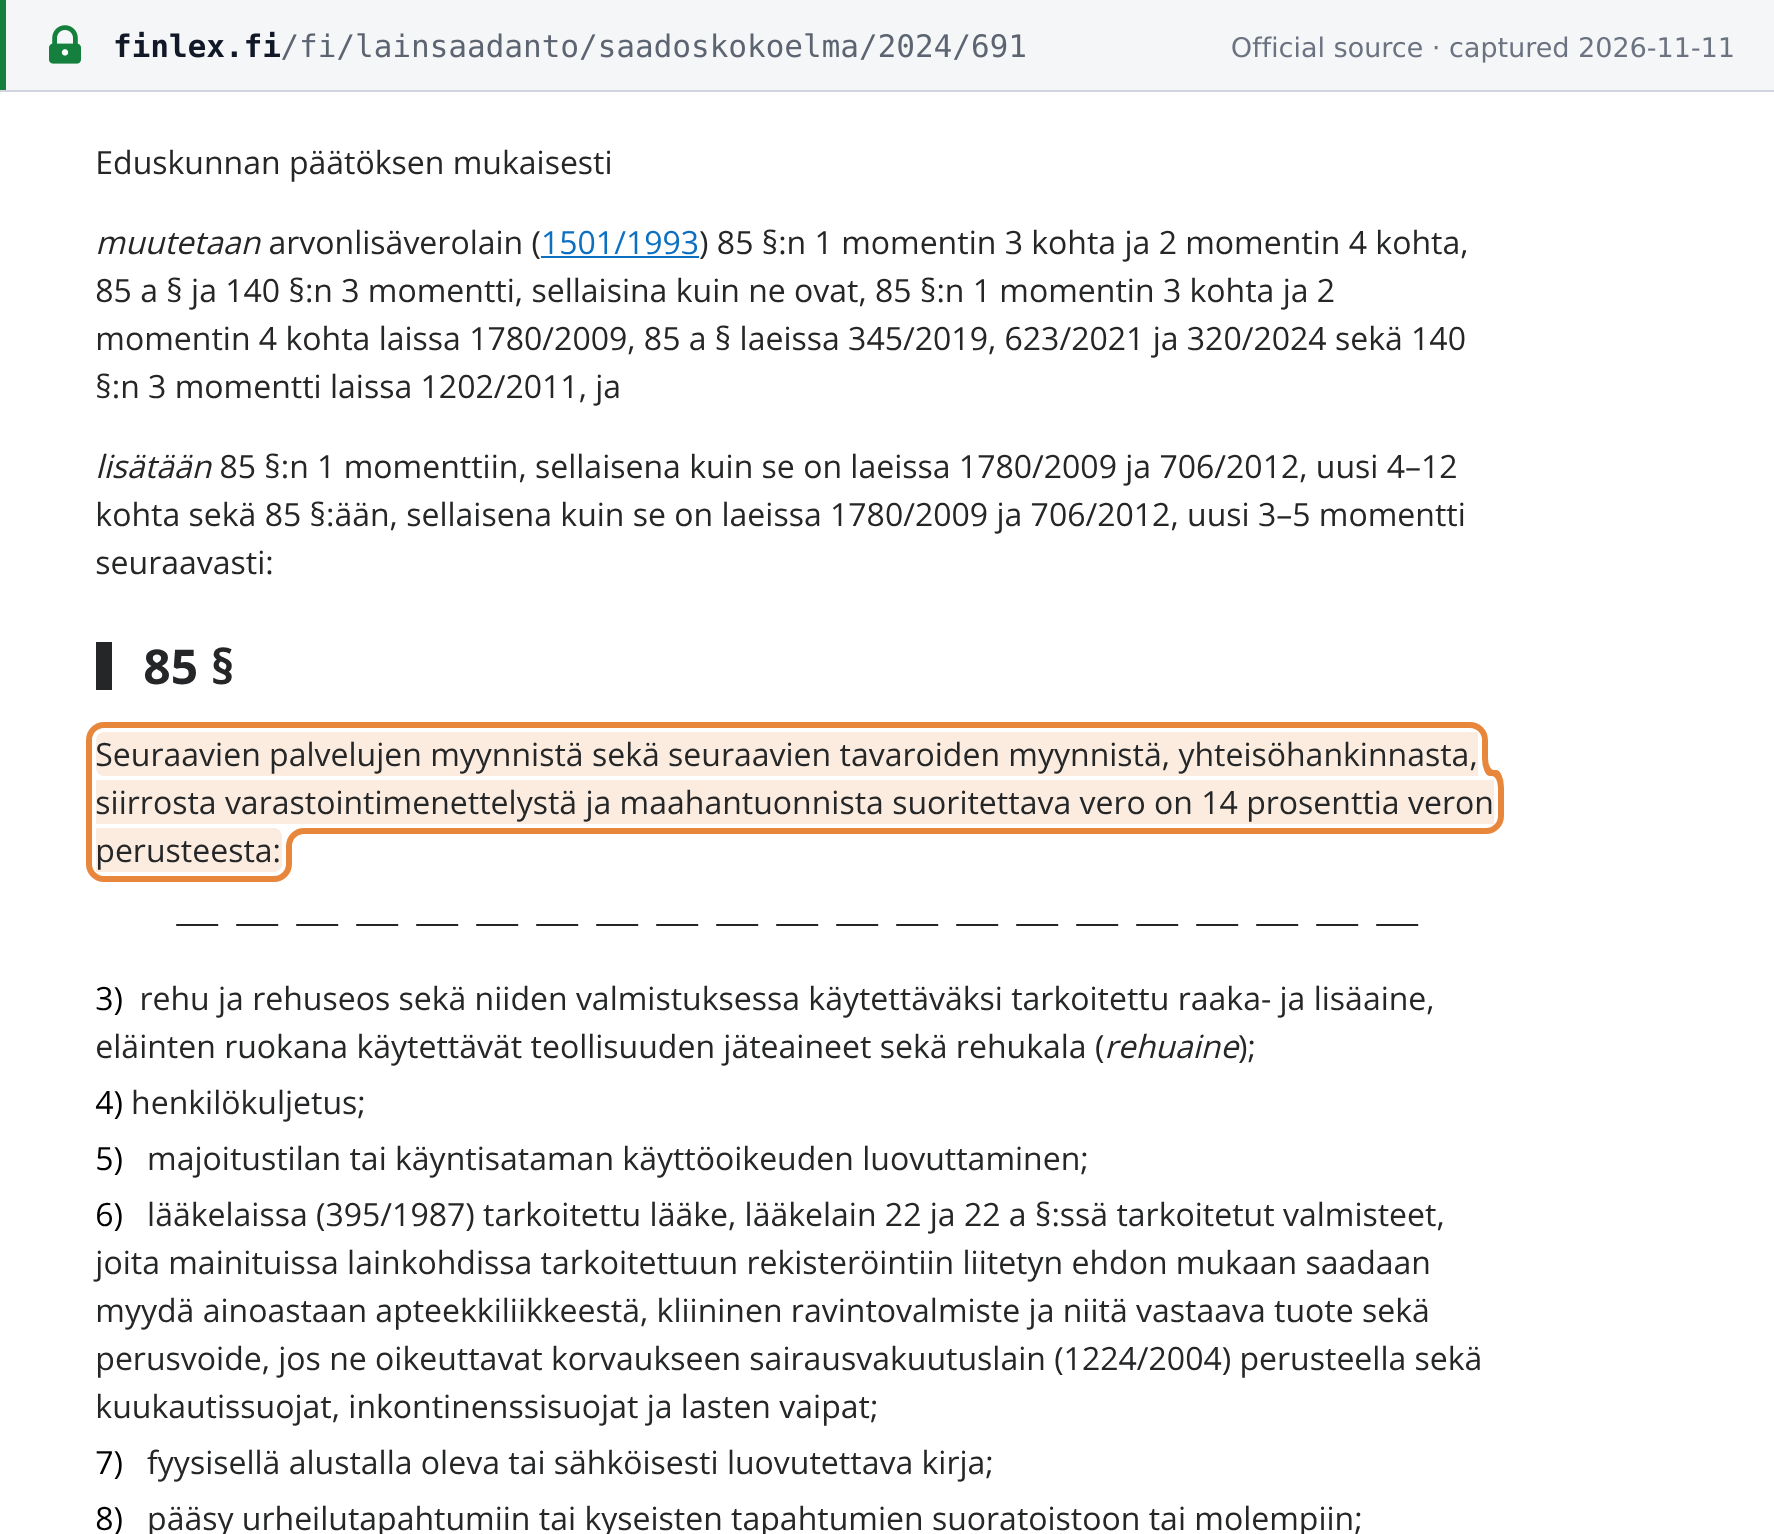 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Suomen säädöskokoelma 691/2024, Laki arvonlisäverolain muuttamisesta, julkaistu Helsingissä 9 päivänä joulukuuta 2024 · www.finlex.fi