France moves electricity and gas subscriptions from 5.5% to the 20% VAT rate from 1 August 2025
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 15 February 2025
- Effective
- 1 August 2025
- Instrument
- FR-LOI-2025-127
- Authority
- Direction générale des Finances publiques (DGFiP) — BOFiP
- Verified
- Fetched from official source · high confidence
Electricity suppliers (maximum power up to 36 kVA) and natural-gas suppliers billing network subscriptions in France, and the households and businesses they bill.
No action — monitoring only; in force since 1 August 2025.
Article 20 of Loi n° 2025-127 du 14 février 2025 (LF 2025) ended the 5.5% reduced VAT rate on subscriptions for electricity (maximum power ≤ 36 kVA) and natural gas supplied through networks. Those subscriptions moved to the 20% standard rate for periods beginning on or after 1 August 2025. Subscriptions for heat distributed by networks keep the reduced rate. DGFiP commented in BOFiP BOI-RES-TVA-000209 of 5 June 2025.
What changed in detail
Article 20 of Loi n° 2025-127 du 14 février 2025 de finances pour 2025 amends Article 278-0 bis of the Code général des impôts. It removes the 5.5% reduced VAT rate on subscriptions for electricity with a maximum power of 36 kVA or less and for natural gas fuel distributed through networks. Those subscriptions move to the 20% standard rate. Subscriptions for heat distributed by networks keep the reduced rate.
At the same time, the law lowers the excise duty on natural gas and on household electricity (Articles L. 312-36 and L. 312-37 of the Code des impositions sur les biens et services). The stated aim is to keep the overall tax on household gas and electricity offers broadly constant.
DGFiP’s rescrit BOI-RES-TVA-000209 of 5 June 2025 sets out the timing. Under B of XI of Article 20, the 20% rate applies to subscriptions relating to periods beginning on or after 1 August 2025. The excise change applies when the energy is supplied. The rescrit also explains how suppliers may split billing periods that straddle 1 August 2025, pro rata by days, and how VAT becomes chargeable where customers pay instalments against an annual schedule.
What it means
This change is in force and not reversed. Since 1 August 2025, electricity and gas subscription charges carry 20% VAT, while the energy consumed was already taxed at 20%. Businesses that recover VAT see little effect; households pay more VAT on the fixed part of the bill, offset by lower excise. The rule turns on the start date of the subscription period, not the invoice date. For “intercalary” billing periods that began before 1 August 2025 and ended after it, the rescrit lets suppliers apply the VAT increase and the excise cut pro rata by days, so 2025 invoices from different suppliers may legitimately treat the same dates differently.
Proof
le remplacement du taux de TVA de 5,5 % par le taux normal de 20 % s’applique aux abonnements se rapportant à des périodes débutant à compter du 1er août 2025the replacement of the 5.5% VAT rate by the 20% standard rate applies to subscriptions relating to periods beginning on or after 1 August 2025
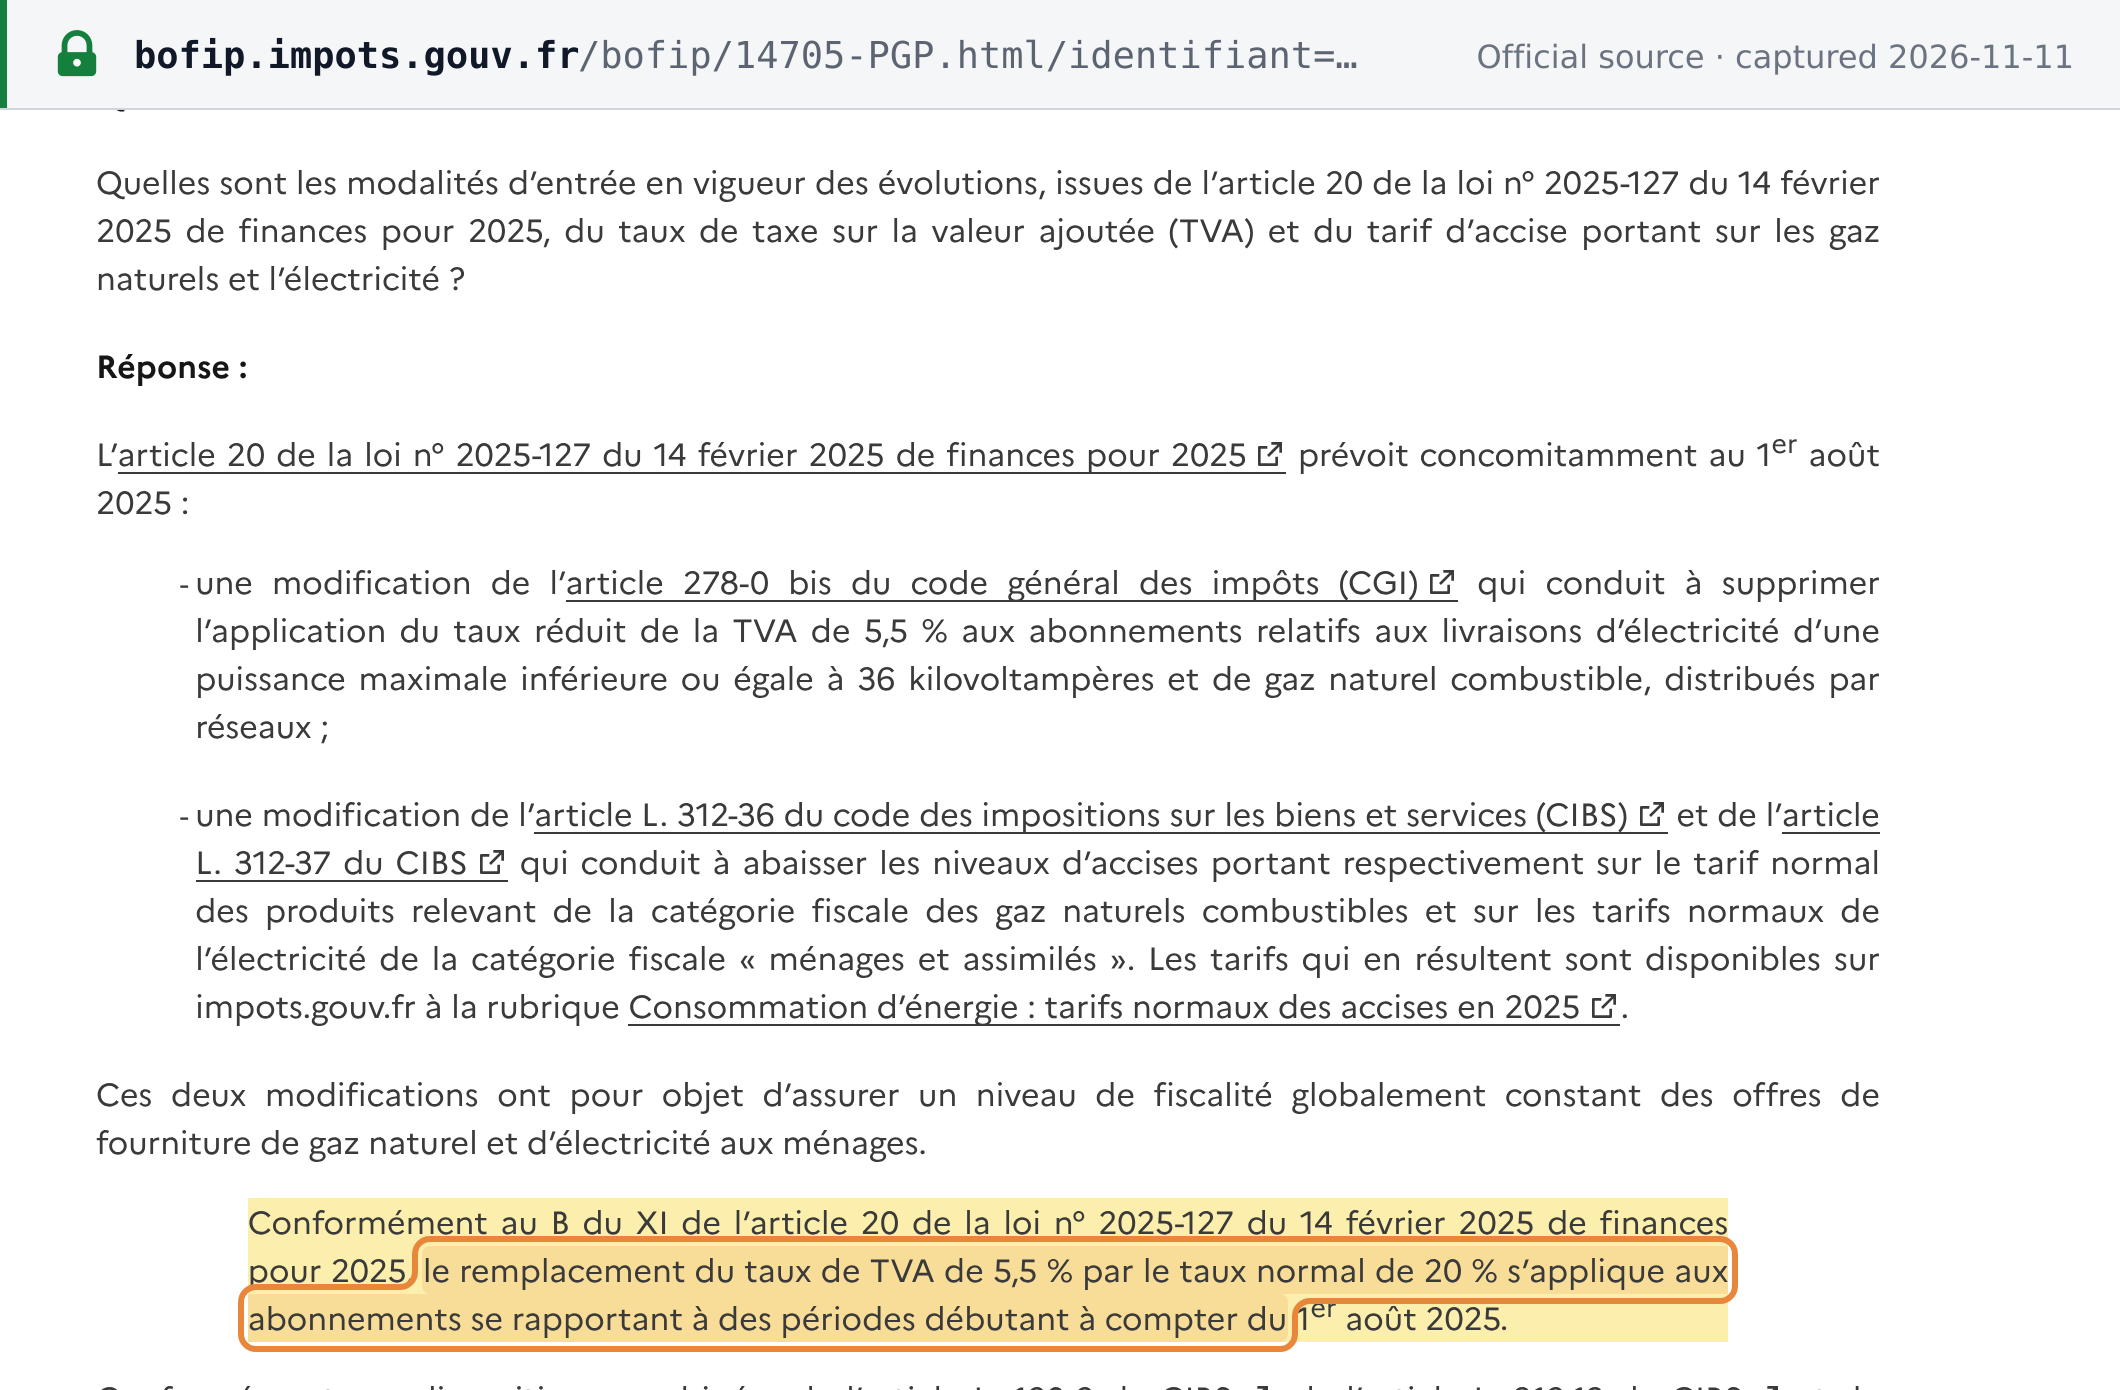 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BOI-RES-TVA-000209-20250605 (BOFiP-Impôts, 5 juin 2025) · bofip.impots.gouv.fr