France redefines taxable hotel accommodation and furnished lettings with services for VAT from 1 January 2024
This page records one dated change. For the rules in France as they stand today, see the France guide →
- Jurisdiction
- France
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 30 December 2023
- Effective
- 1 January 2024
- Instrument
- FR-LOI-Loi-n-2023-1322
- Authority
- Journal officiel de la République française (Légifrance)
- Verified
- Fetched from official source · high confidence
Hotels, aparthotels, serviced residences and landlords of furnished residential accommodation in France that provide breakfast, cleaning, linen or reception services.
No action required — the amended CGI art. 261 D has been in force since 1 January 2024. Operators of furnished short-stay or para-hotel accommodation should verify their VAT position under the revised rules.
Article 84 of Loi n° 2023-1322 du 29 décembre 2023 (LF 2024) rewrote CGI art. 261 D 4° to align the taxation of accommodation with EU law (Conseil d'État opinion of 5 July 2023), from 1 January 2024. Hotel-sector and similar accommodation is taxable when offered for no more than 30 nights with a furnished room and at least three of breakfast, regular cleaning, household linen and reception; furnished residential lettings in other sectors are taxable when they include at least three of those services. Both are taxed at the 10% rate under the rewritten art. 279 a.
What changed in detail
Article 84 of Loi n° 2023-1322 du 29 décembre 2023 de finances pour 2024, published in JORF n°0303 of 30 December 2023, rewrites 4° of Article 261 D of the Code général des impôts (CGI), which carves taxable accommodation out of the VAT exemption for letting furnished dwellings. It follows a Conseil d’État opinion of 5 July 2023 (n° 471877).
- The old a is repealed.
- New b: accommodation in the hotel sector or sectors with a similar function is taxable when it is offered for no more than 30 nights, renewals aside, and includes a furnished room and at least three of breakfast, regular cleaning, household linen and reception, even if not personalised.
- New b bis: furnished residential lettings in other sectors are taxable when they include at least three of those four services.
- Article 279 a is rewritten so that both b and b bis take the 10% rate.
The article has no commencement clause; Article 1 II 3° of the law applies it from 1 January 2024. DGFiP’s BOFiP update of 7 August 2024 (ACTU-2024-00069) confirms that date and reorganises its commentary on accommodation rates.
What it means
This is in force. It replaced a test built on how the operator ran its business with one built on the services the guest actually receives: a hotel-type stay of up to 30 nights, or a serviced let in any sector, with three of the four listed services is taxable at 10%; without them, the let stays exempt. Landlords of serviced furnished flats who were exempt before 2024 can now fall within VAT. DGFiP added further doctrine on 26 March 2025, so check the current BOFiP text before classifying a mixed offer. From 1 January 2027 the VAT provisions of the CGI move into the Code des impositions sur les biens et services (cibs-vat-transfer-moved-2027-ordonnance-671), so the article reference changes while the rule carries over.
Proof
« b bis. Aux locations de logements meublés à usage résidentiel dans le cadre de secteurs autres que ceux mentionnés au b qui sont assorties d'au moins trois des prestations suivantes : le petit déjeuner, le nettoyage régulier des locaux, la fourniture de linge de maison et la réception, même non personnalisée, de la clientèle ; »“b bis. To lettings of furnished residential accommodation in sectors other than those in b that include at least three of the following services: breakfast, regular cleaning of the premises, supply of household linen and reception of customers, even if not personalised;”
Archived from the official distribution · JORFARTI000048727437 (article 84) · JORFTEXT000048727345 · NOR ECOX2322957L · JORF n°0303 du 30 décembre 2023 · echanges.dila.gouv.fr
a modifié l’article 261 D du code général des impôts (CGI) afin de le mettre en conformité avec le droit européen à compter du 1er janvier 2024amended Article 261 D of the Code général des impôts (CGI) to bring it into line with EU law from 1 January 2024
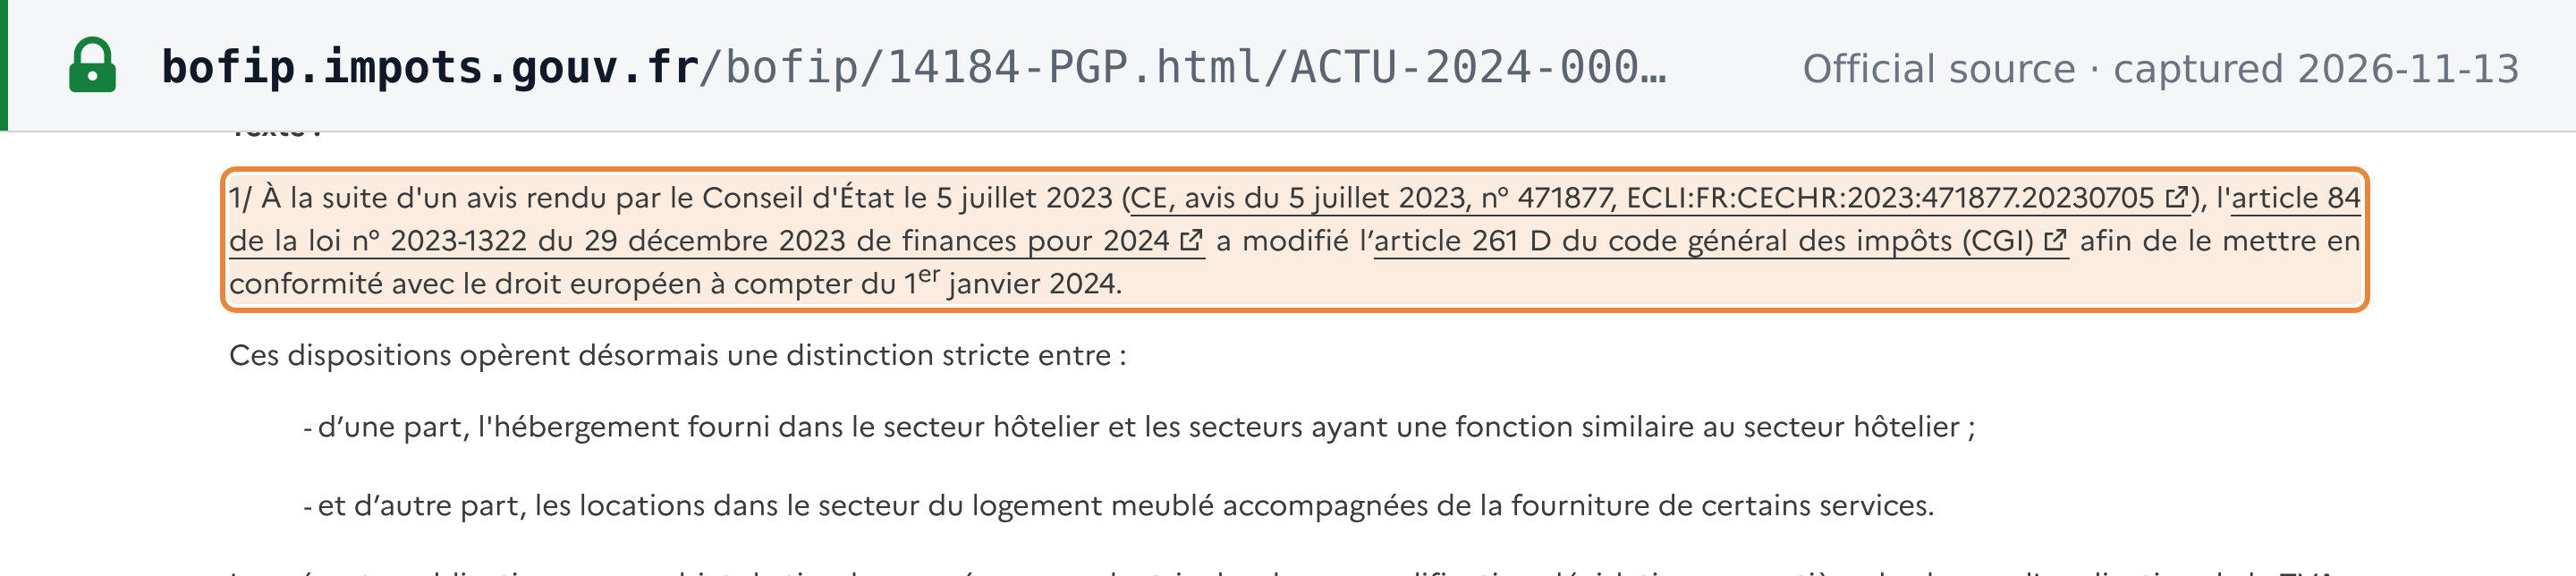 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · ACTU-2024-00069 (BOFiP-Impôts, 7 août 2024) · bofip.impots.gouv.fr