Georgia restates its real-estate VAT exemption to cover supplies made until 1 January 2029
This page records one dated change. For the rules in Georgia as they stand today, see the Georgia guide →
- Jurisdiction
- Georgia
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 14 November 2025
- Effective
- 1 January 2026
- Instrument
- GE-LAW-1061-IV-XI
- Authority
- Legislative Herald of Georgia (Matsne)
- Verified
- Fetched from official source · high confidence
Developers in Georgia holding the construction permit for wholly or partly residential buildings covered by pre-8 August 2008 permits or designs and listed under Tax Code Article 309(81).
No action — monitoring only.
Law No. 1061-IVმს-XIმპ, adopted on 12 November 2025, published on 14 November 2025 and in force 1 January 2026, restated Article 309(79) of the Georgian Tax Code: the supply of immovable property, and construction-installation services by the supplier related to that property, is exempt from VAT with the right of deduction where the supply is made between 1 January 2015 and 1 January 2029, the building was covered by a construction permit or approved design in force on 8 August 2008 (or a successor permit), the supplier holds the permit, the building is wholly or partly residential and is on the Article 309(81) list, and the occupancy (commissioning) act is issued before 1 January 2029. The law also restated Article 309(81^2), setting limitation periods of 14 down to 4 years for exempt supplies made in 2015-2025.
What changed in detail
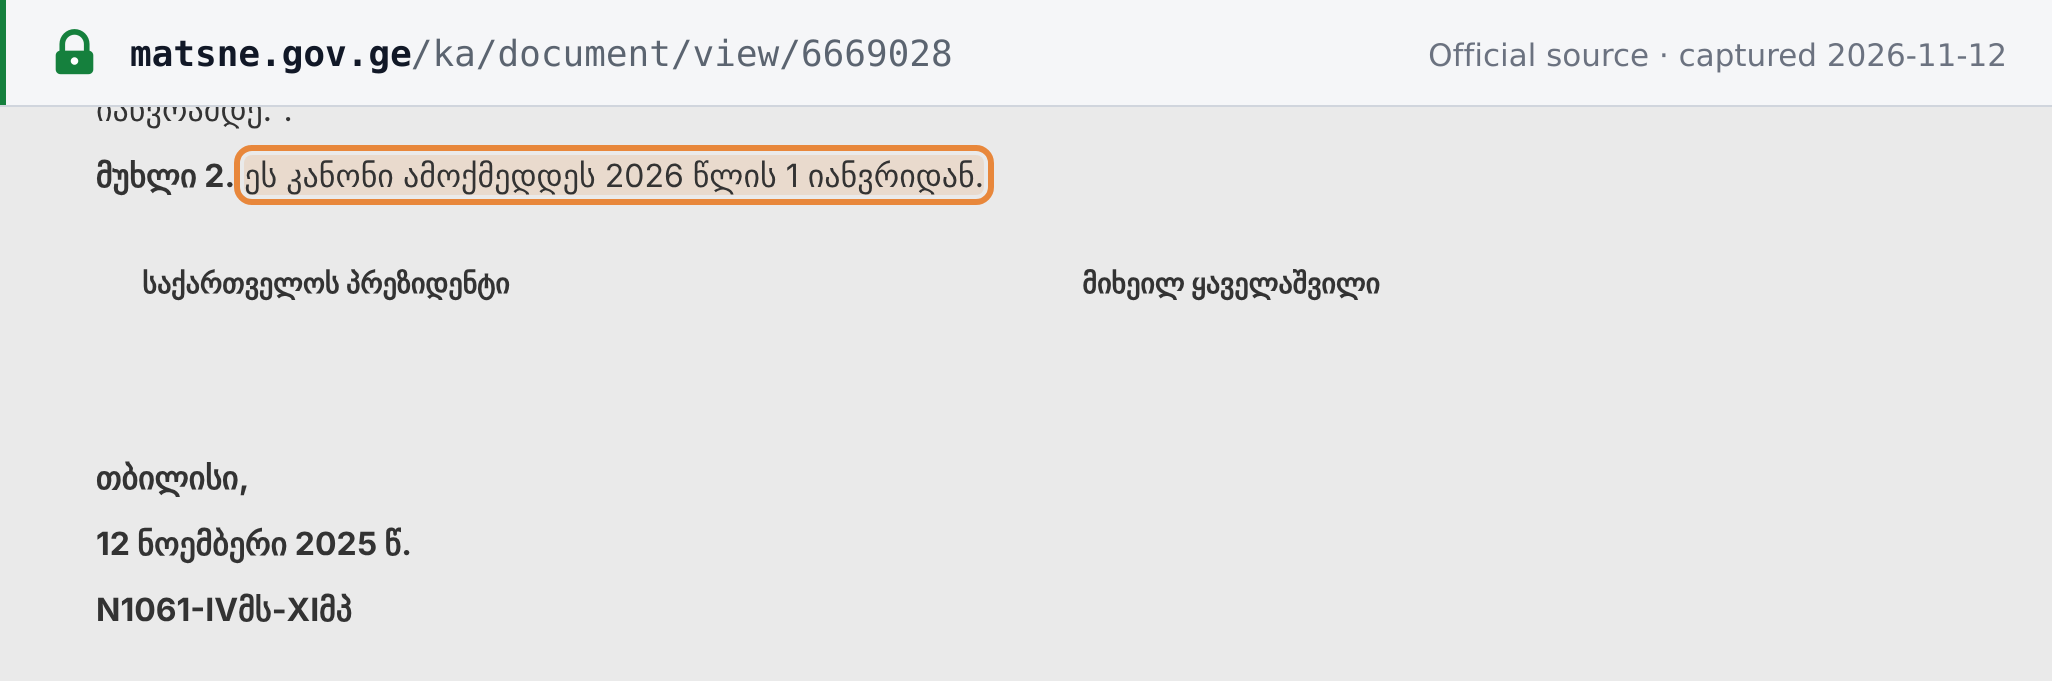
Law No. 1061-IVმს-XIმპ “On Amendments to the Tax Code of Georgia” was adopted by Parliament on 12 November 2025, published on the Legislative Herald website on 14 November 2025 and entered into force on 1 January 2026 (Article 2).
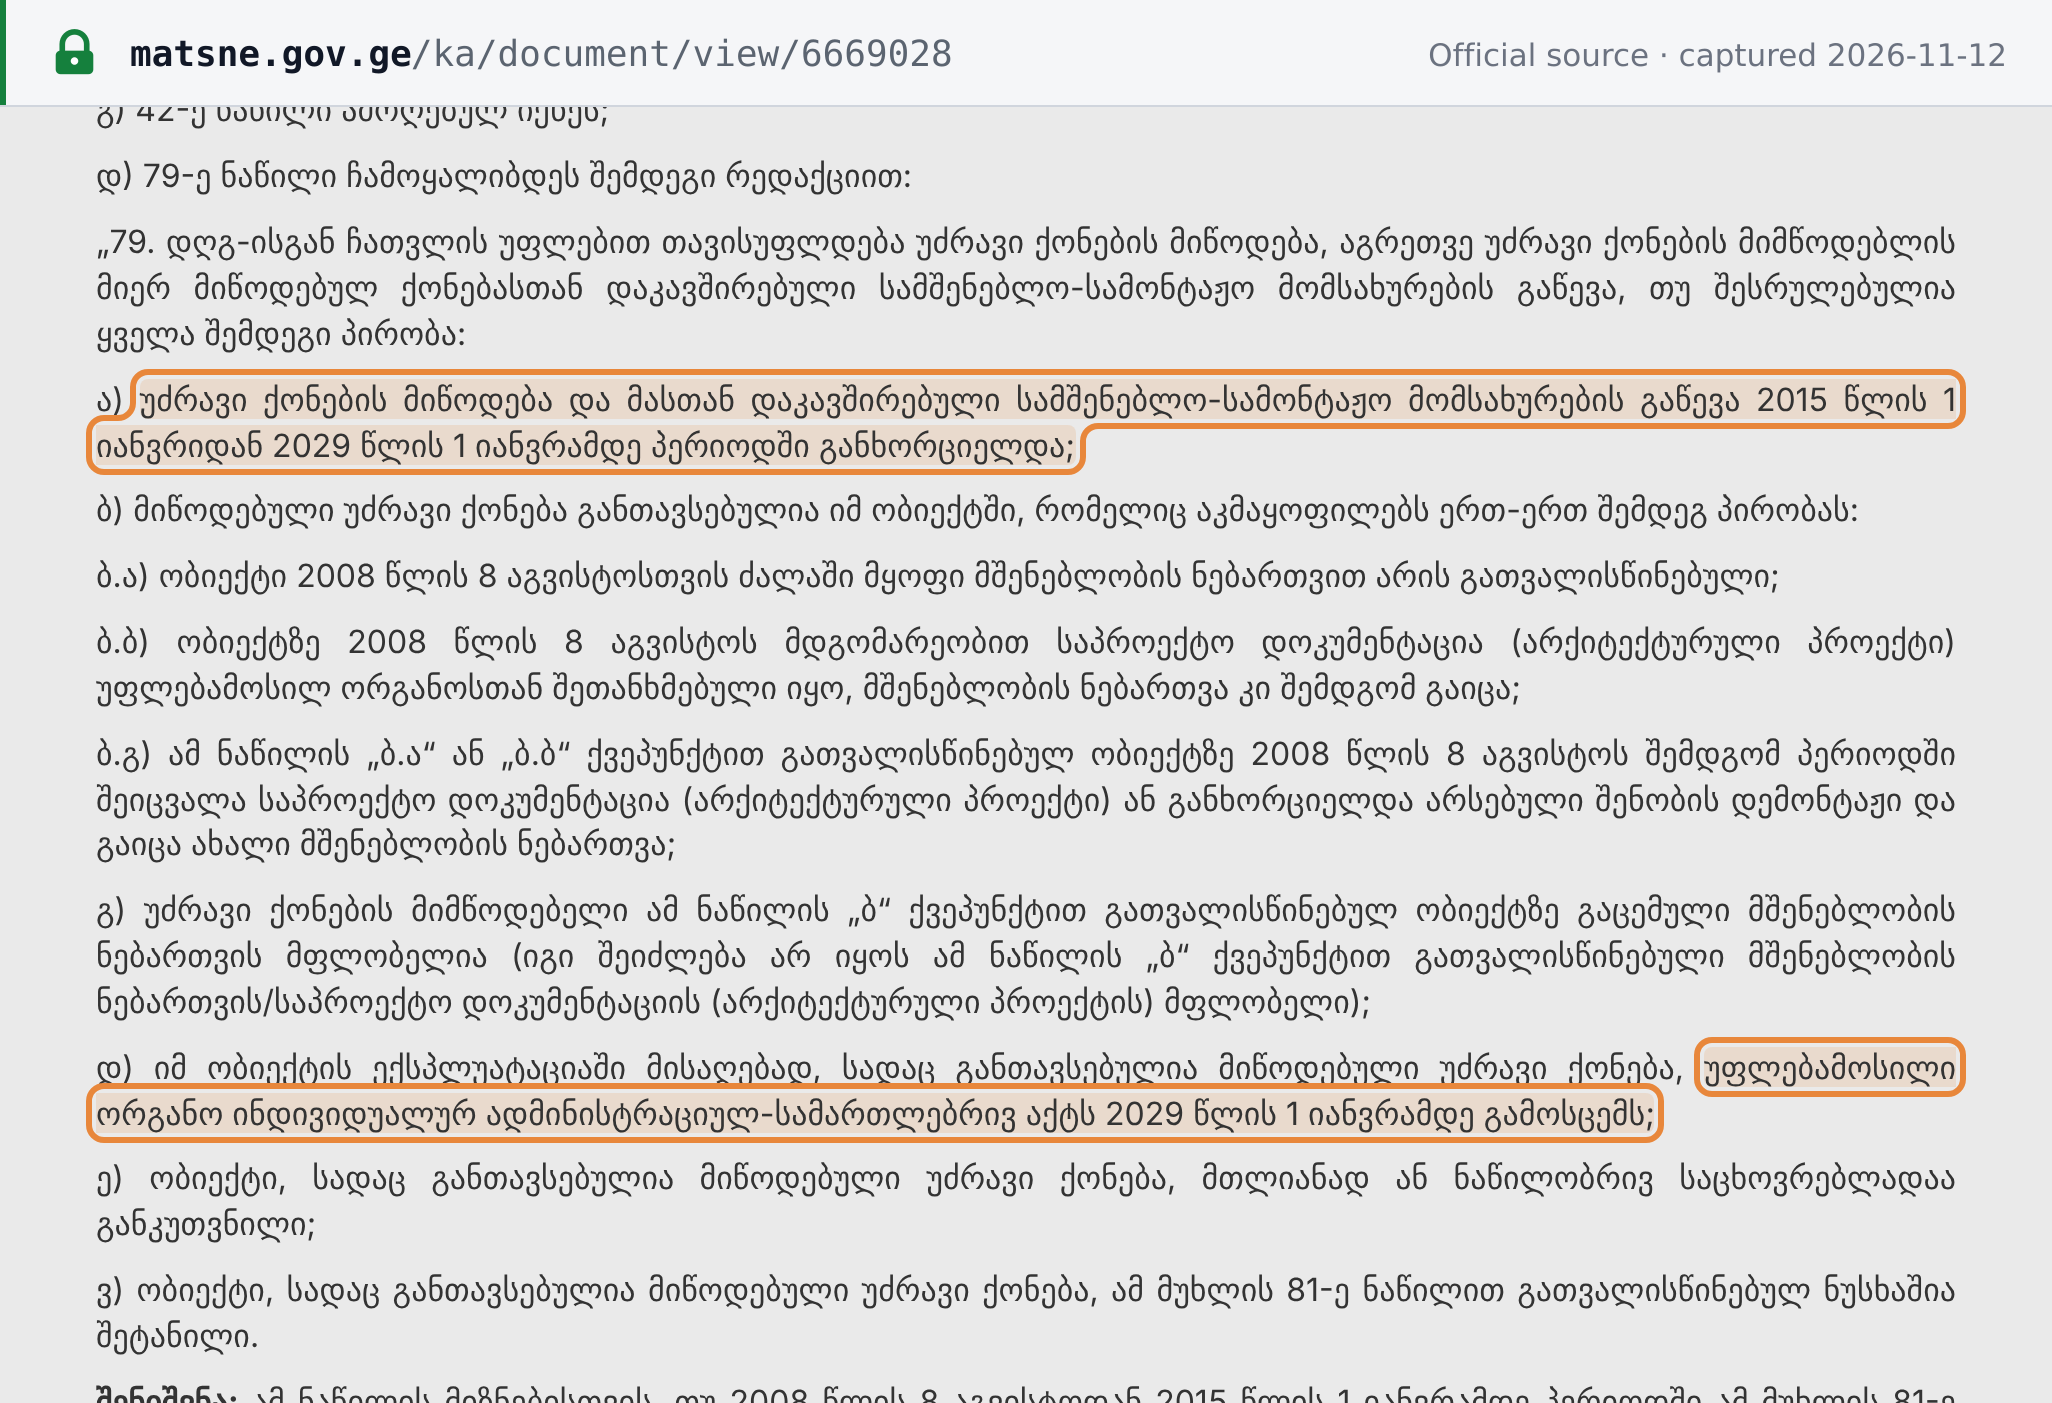
Article 1, point 17(დ), restates paragraph 79 of Article 309, the Tax Code’s transitional provisions. The supply of immovable property, and construction-installation services the supplier provides in connection with that property, are exempt from VAT with the right of deduction if all of these conditions are met:
- the supply is made between 1 January 2015 and 1 January 2029;
- the building was covered by a construction permit in force on 8 August 2008, or its design was approved by that date and the permit issued later, including where the design was changed or the building demolished and a new permit issued after that date;
- the supplier holds the construction permit for the building;
- the competent authority issues the act putting the building into operation before 1 January 2029;
- the building is wholly or partly residential; and
- the building is on the list under Article 309(81).
Point 17(ე) restates paragraph 81², which sets the limitation periods for exempt supplies made in the reporting periods from 2015 to 2025, running from 14 years down to 4 years.
What it means
This version of the rule is superseded. Law No. 1888-VIმს-XIმპ, in force on 16 October 2026, moved both 1 January 2029 dates in Article 309(79) to 1 January 2033 and restated the limitation table again (Georgia extends the exemption to 2033). The consolidated Tax Code now reads 2033.
The 2029 wording governed from 1 January to 15 October 2026. For developers it mattered because the exemption keeps input VAT recoverable, so the relief is worth more than an ordinary exemption. A project that could not get its occupancy act by the end of 2028 had to plan for VAT under this version; under the current text it has until the end of 2032.
Proof
ა) უძრავი ქონების მიწოდება და მასთან დაკავშირებული სამშენებლო-სამონტაჟო მომსახურების გაწევა 2015 წლის 1 იანვრიდან 2029 წლის 1 იანვრამდე პერიოდში განხორციელდა;(a) the supply of immovable property and the related construction-installation services took place in the period from 1 January 2015 to 1 January 2029;
 Source snapshot of the official page. Open full size ↗
ეს კანონი ამოქმედდეს 2026 წლის 1 იანვრიდან.This Law shall enter into force from 1 January 2026.
 Source snapshot of the official page. Open full size ↗