Germany raises the Kleinunternehmer VAT thresholds to EUR 25,000 and EUR 100,000 from 2025
This page records one dated change. For the rules in Germany as they stand today, see the Germany guide →
- Jurisdiction
- Germany
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 5 December 2024
- Effective
- 1 January 2025
- Instrument
- DE-ACT-BGBl-I-2024-Nr-387
- Authority
- Bundesministerium der Justiz (gesetze-im-internet.de)
- Verified
- Fetched from official source · high confidence
Small businesses established in Germany with total turnover of no more than EUR 25,000 in the previous year and EUR 100,000 in the current year, and German small businesses that want the exemption in another EU Member State.
No action — historical reference. The new Kleinunternehmer thresholds (EUR 25,000 prior-year / EUR 100,000 current-year) have been in force since 1 January 2025.
The Jahressteuergesetz 2024, published as BGBl. I 2024 Nr. 387 on 5 December 2024, amended § 19 UStG (Besteuerung der Kleinunternehmer) with effect from 1 January 2025: the prior-year turnover threshold rose from EUR 22,000 to EUR 25,000, and the current-year ceiling rose from EUR 50,000 to EUR 100,000. A new § 19a UStG implements the EU cross-border SME scheme (Directive 2020/285), allowing German small businesses to use the exemption in other EU member states and vice versa.
What changed in detail
The Jahressteuergesetz 2024 of 2 December 2024 was published on 5 December 2024 as BGBl. I 2024 Nr. 387. It rewrote § 19 UStG (Besteuerung der Kleinunternehmer) with effect from 1 January 2025.
Under the new § 19 Abs. 1, a supply by a business established in Germany is exempt where total turnover:
- did not exceed EUR 25,000 in the previous calendar year (previously EUR 22,000); and
- does not exceed EUR 100,000 in the current calendar year (previously EUR 50,000).
Two things changed besides the figures. The current-year limit is now a ceiling on actual turnover, measured during the year, where the old EUR 50,000 was a forecast made at the start of the year. And the relief is now a true exemption (“ist steuerfrei”) rather than VAT that is simply not collected.
The same Act implemented the EU SME scheme (Directive (EU) 2020/285). Under the new § 19a UStG, a German small business can use the small-business exemption of another Member State through a special notification procedure with the Bundeszentralamt für Steuern. It receives a Kleinunternehmer-Identifikationsnummer, provided its EU-wide annual turnover stays within EUR 100,000. In the other direction, § 19 Abs. 4 lets small businesses established in other Member States use the German exemption, if their EU-wide turnover stays within EUR 100,000 and their home state has issued them a Kleinunternehmer-Identifikationsnummer.
What it means
These thresholds are still in force. The consolidated § 19 UStG (last amended 29 June 2026) carries EUR 25,000 and EUR 100,000 unchanged, and the Jahressteuergesetz 2026 bill (Bundestag-Drucksache 21/8283) does not amend them.
The trap is the current-year ceiling. Under the pre-2025 rules a business could stay exempt for the whole year if its forecast was reasonable. Now the exemption depends on current-year turnover not exceeding EUR 100,000, so a business that crosses that line part-way through the year loses it from that point rather than at year end, and has to start invoicing with VAT. The cross-border scheme only helps a business whose EU-wide turnover stays within EUR 100,000.
Proof
ist steuerfrei, wenn der Gesamtumsatz nach Absatz 2 im vorangegangenen Kalenderjahr 25 000 Euro nicht überschritten hat und im laufenden Kalenderjahr 100 000 Euro nicht überschreitet.(A supply made by a business established in Germany …) is exempt if total turnover under paragraph 2 did not exceed EUR 25,000 in the previous calendar year and does not exceed EUR 100,000 in the current calendar year.
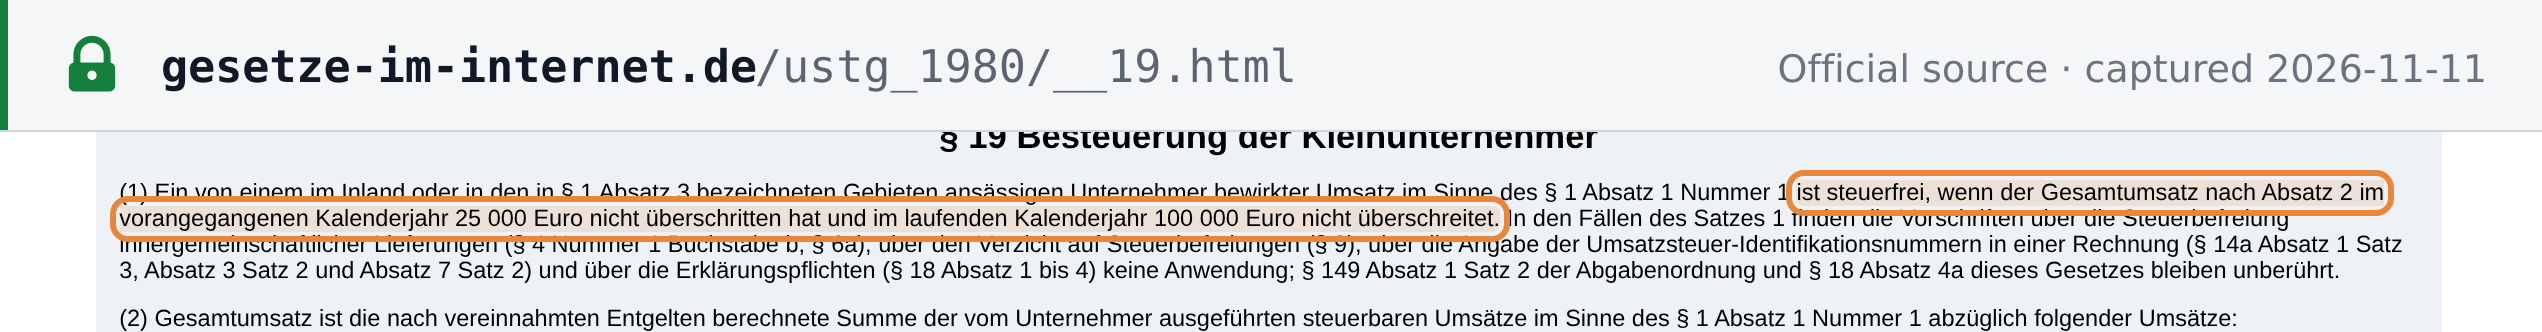 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Umsatzsteuergesetz § 19 Absatz 1 (consolidated text, Stand: zuletzt geändert durch Art. 5 G v. 29.6.2026 I Nr. 197) · www.gesetze-im-internet.de