Germany returns restaurant and catering food to the 19% VAT rate from 1 January 2024
This page records one dated change. For the rules in Germany as they stand today, see the Germany guide →
- Jurisdiction
- Germany
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 1 January 2024
- Effective
- 1 January 2024
- Authority
- Deutscher Bundestag
- Verified
- Fetched from official source · high confidence
Restaurants, cafés, caterers and other businesses in Germany supplying restaurant and catering services (food served for consumption on the spot); beverages were never covered by the 7% rate.
No action — historical reference. Restaurant and catering food (excluding beverages) reverted to 19% from 1 January 2024, then returned permanently to 7% from 1 January 2026 (see de-restaurant-vat-7pct-permanent-2025).
The temporary 7% VAT rate on restaurant and catering services (excluding beverages) applied from 1 July 2020 to 31 December 2023. It was last extended to 31 December 2023 by the Achtes Gesetz zur Änderung von Verbrauchsteuergesetzen of 24 October 2022 (BGBl. I 2022 Nr. 39, S. 1838). It expired on 31 December 2023, and from 1 January 2024 the 19% standard rate applied again. No new instrument was needed for the reversion.
What changed in detail
From 1 July 2020, as a pandemic crisis measure, Germany taxed restaurant and catering services at the 7% reduced rate under a time-limited § 12 Abs. 2 Nr. 15 UStG. Beverages were excluded throughout and stayed at 19%.
The measure was extended more than once. The last extension, to 31 December 2023, came from the Achtes Gesetz zur Änderung von Verbrauchsteuergesetzen of 24 October 2022 (BGBl. I 2022 Nr. 39, S. 1838).
No further extension was enacted. The reduced rate lapsed at the end of 2023, and from 1 January 2024 restaurant and catering services were taxed again at the 19% standard rate. No new instrument was needed for the reversion: it followed from the end date already written into the law.
The federal government’s own account of this history is in the explanatory memorandum to the Steueränderungsgesetz 2025 bill (Bundestag-Drucksache 21/1974). It states that these services were subject to the reduced rate from 1 July 2020 to 31 December 2023 and that the standard rate has applied again since 1 January 2024.
Food sold for takeaway or delivery without a significant service element was not affected. It was taxed at 7% as a supply of food under Anlage 2 both before and after 2024.
What it means
This 19% position is spent. It governed restaurant and catering food supplied in 2024 and 2025 only. The Steueränderungsgesetz 2025 (BGBl. I 2025 Nr. 363) put these services back at 7% for supplies after 31 December 2025, this time with no end date.
So the rate depends on when the meal was served: 7% from July 2020 to December 2023, 19% for 2024 and 2025, and 7% again from 1 January 2026. Drinks have been at 19% throughout. Corrections and audits of 2024–2025 invoices should still use 19%.
Proof
Als temporäre Krisenmaßnahme unterlagen Restaurant- und Verpflegungsdienstleistungen, mit Ausnahme der Abgabe von Getränken, bereits vom 1. Juli 2020 bis zum 31. Dezember 2023 dem ermäßigten Steuersatz. Seit dem 1. Januar 2024 gilt für diese Leistungen wieder der Regelsteuersatz.As a temporary crisis measure, restaurant and catering services, excluding the supply of beverages, were already subject to the reduced tax rate from 1 July 2020 to 31 December 2023. Since 1 January 2024 the standard tax rate has applied again to these services.
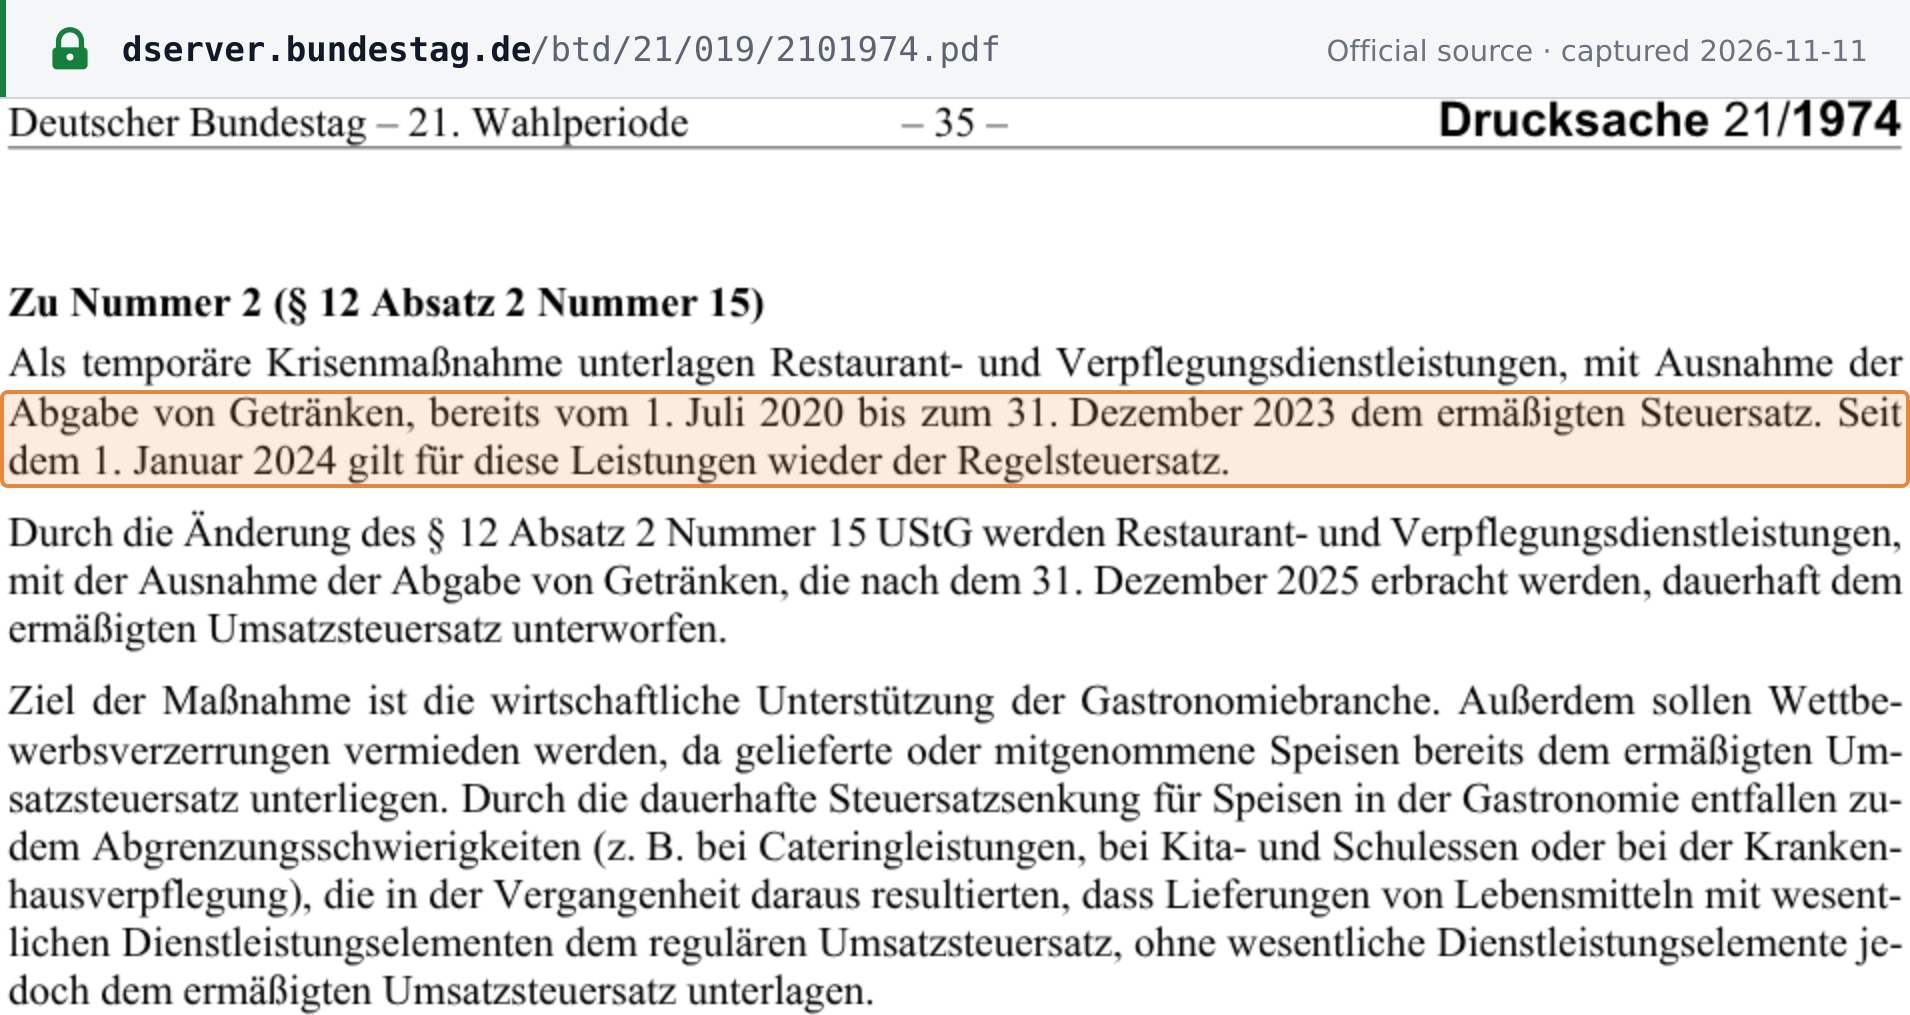 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · BT-Drucksache 21/1974, Entwurf eines Steueränderungsgesetzes 2025, Begründung zu Artikel 4 Nummer 2 (§ 12 Absatz 2 Nummer 15 UStG), p. 35 · dserver.bundestag.de