Greece moves sanitary towels, tampons and adult incontinence nappies to the reduced VAT list from 1 January 2027 (Law 5355/2026)
This page records one dated change. For the rules in Greece as they stand today, see the Greece guide →
- Jurisdiction
- Greece
- Tax
- VAT
- Change type
- Rate change
- Status
- Enacted
- Impact
- Action required
- Announced
- 13 November 2026
- Effective
- 1 January 2027
- Authority
- Εθνικό Τυπογραφείο (Εφημερίδα της Κυβερνήσεως)
- Systems
- Tax engine, POS
- Verified
- Fetched from official source · high confidence
Manufacturers, importers, wholesalers and retailers (including pharmacies and supermarkets) selling sanitary towels, tampons, similar hygiene articles and adult incontinence nappies in Greece.
Sellers of feminine-hygiene products and adult incontinence products in Greece: apply the Annex III reduced VAT rate from 1 January 2027 instead of the standard 24% rate.
Tax enginePOS
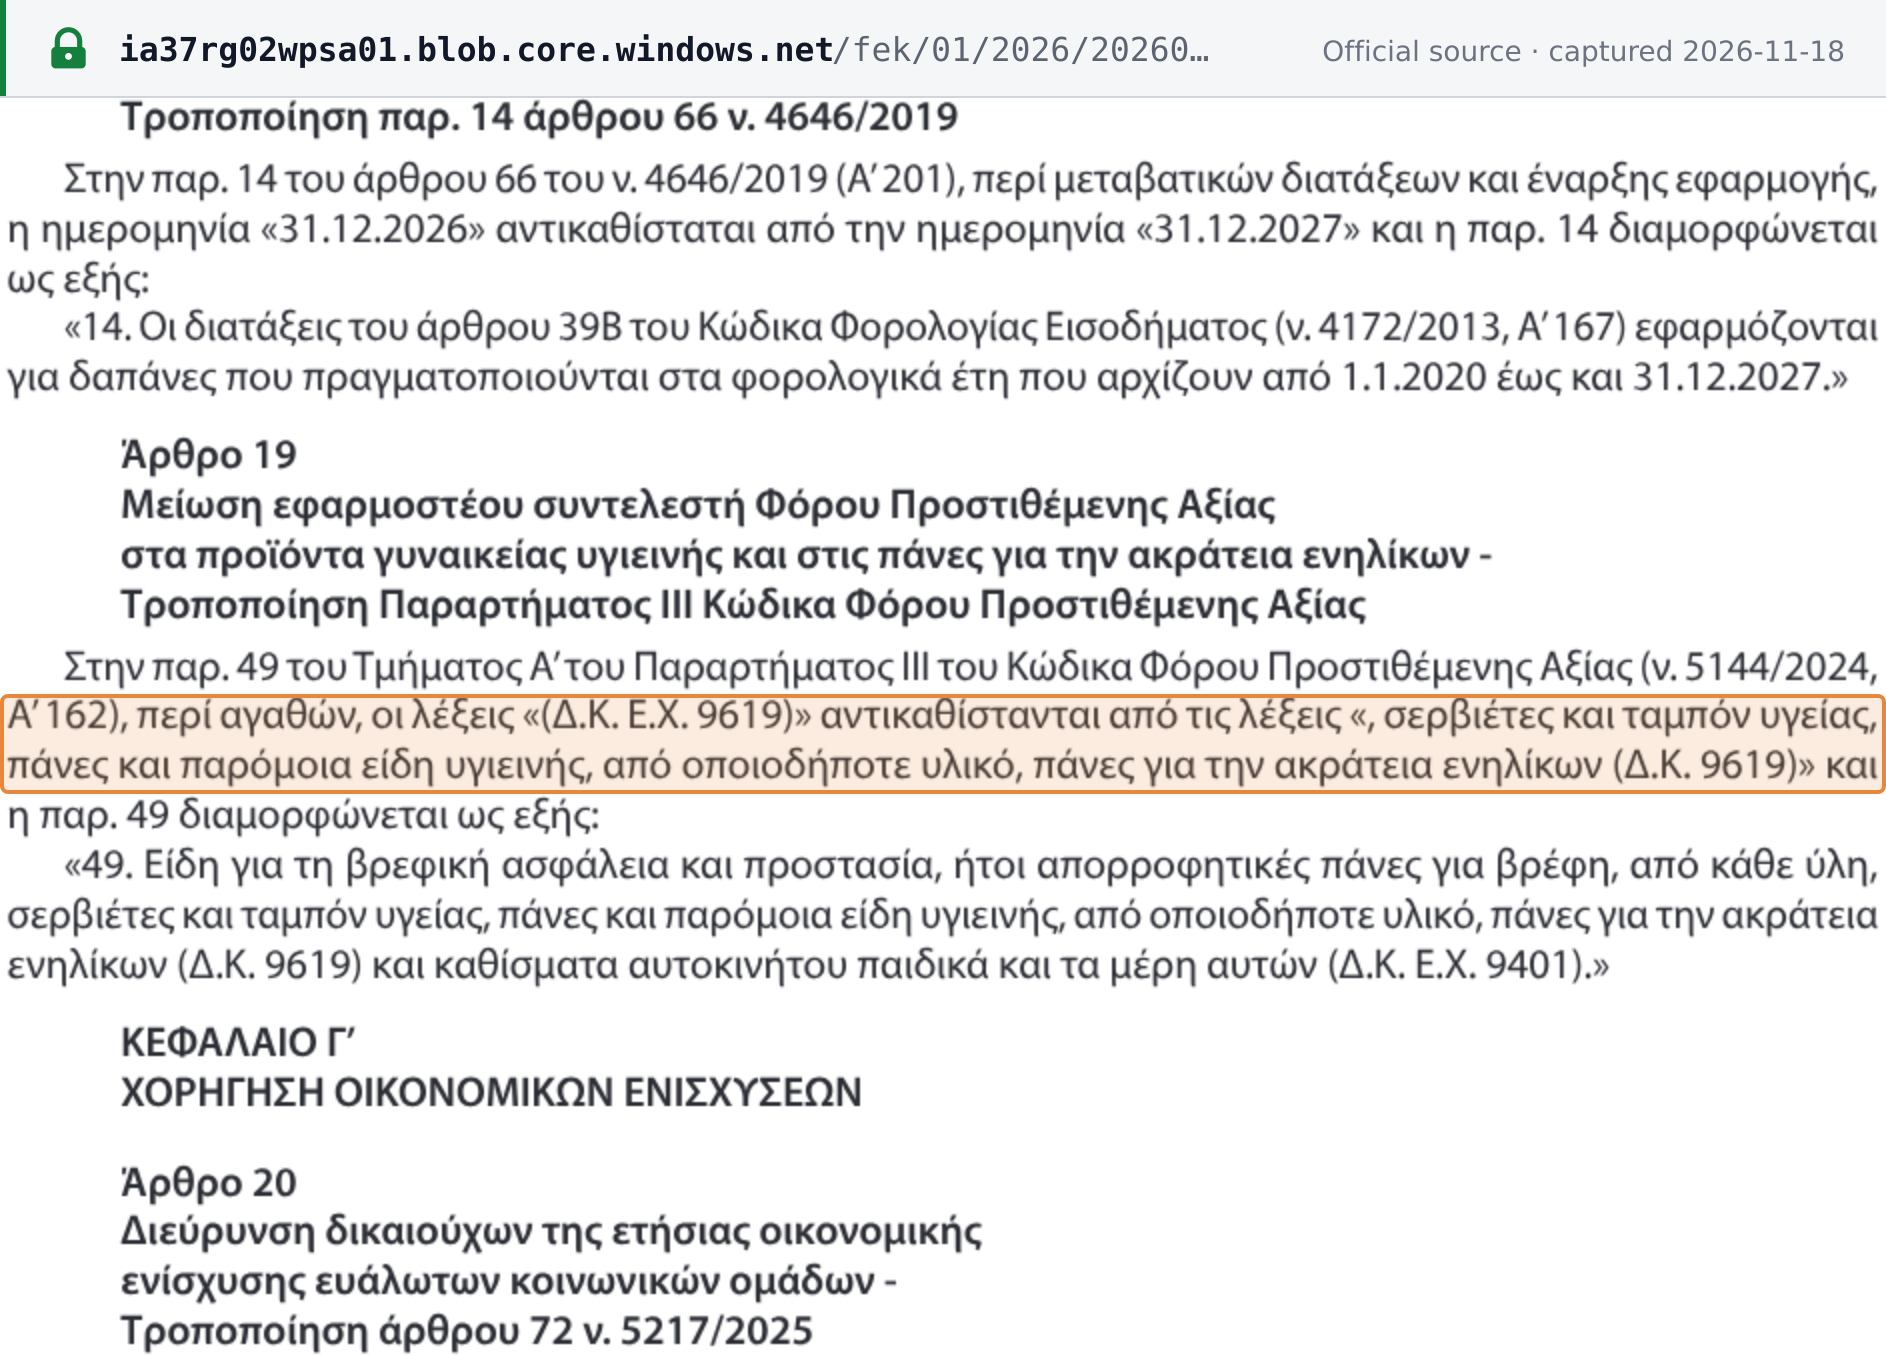
Greece's Law 5355/2026 (Government Gazette ΦΕΚ Α' 188, 13 November 2026), Article 19, amends paragraph 49 of Section A of Annex III of the VAT Code (Law 5144/2024) to add sanitary towels and tampons, nappies and similar hygiene articles of any material, and adult incontinence nappies, moving these feminine-hygiene and adult-incontinence products into Annex III (the reduced-rate list). Under Article 53(9), Article 19 applies from 1 January 2027.
What changed in detail
Law 5355/2026 was published in the Government Gazette (ΦΕΚ Α’ 188) on 13 November 2026. Its Article 19 is headed “Reduction of the applicable VAT rate on feminine-hygiene products and adult incontinence nappies – Amendment of Annex III of the VAT Code”.
Article 19 amends paragraph 49 of Section A (goods) of Annex III of the VAT Code (Law 5144/2024, Α’ 162). The words “(Δ.Κ. Ε.Χ. 9619)” are replaced by ”, sanitary towels and tampons, nappies and similar hygiene articles, of any material, adult incontinence nappies (Δ.Κ. 9619)”. Paragraph 49 now reads: articles for infant safety and protection, namely absorbent baby nappies of any material, sanitary towels and tampons, nappies and similar hygiene articles of any material, adult incontinence nappies (CN 9619), and child car seats and their parts (CN ex 9401).
Before the amendment paragraph 49 covered only the baby-nappy part of CN 9619 and child car seats, so the feminine-hygiene and adult-incontinence products added by Article 19 fell outside Annex III.
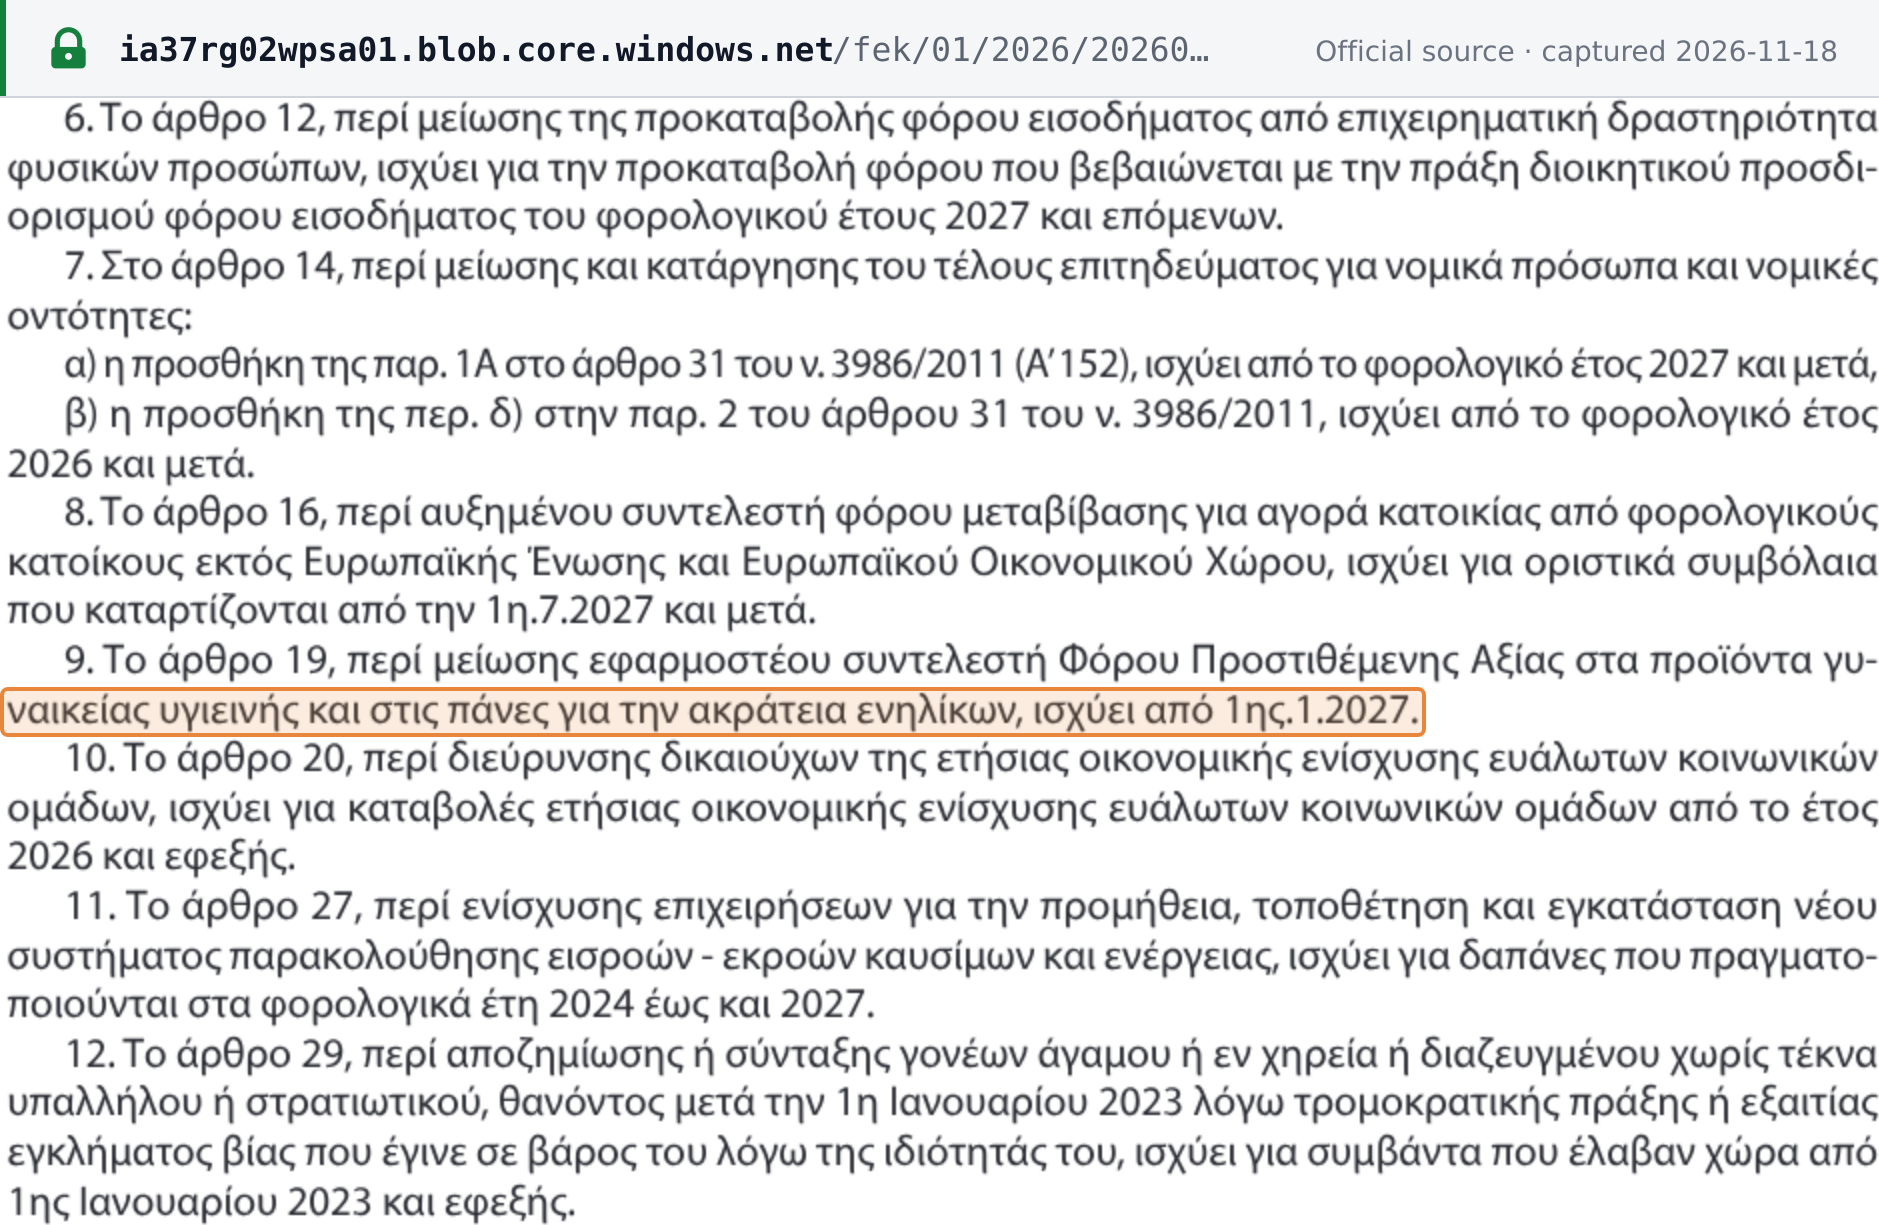
Under Article 53(9) of the same law, Article 19 applies from 1 January 2027.
The article does not state a percentage; it moves the goods into Annex III, the list of goods and services taxed at the reduced rate.
What it means
From 1 January 2027 these products leave the standard 24% rate and take the Annex III rate, which for goods with no specific 6% or 4% provision in the Annex is 13% (9% on the islands covered by the 30% island reduction). Retail and POS systems need the new rate on the affected SKUs from the first sale of 2027, and the classification follows CN 9619, so product master data keyed to customs codes is the easiest place to make the change. Baby nappies were already on the list; nothing changes for them.
Proof
σερβιέτες και ταμπόν υγείας, πάνες και παρόμοια είδη υγιεινής, από οποιοδήποτε υλικό, πάνες για την ακράτειαsanitary towels and tampons, nappies and similar hygiene articles, of any material, nappies for incontinence
 Source snapshot of the official page. Open full size ↗
πάνες για την ακράτεια ενηλίκων, ισχύει από 1ης.1.2027.[Article 19, on the reduction of the applicable VAT rate on feminine-hygiene products and] adult incontinence nappies, applies from 1.1.2027.
 Source snapshot of the official page. Open full size ↗