Hungary extends the domestic reverse charge to gas sold between dealers from 1 January 2025
This page records one dated change. For the rules in Hungary as they stand today, see the Hungary guide →
- Jurisdiction
- Hungary
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 28 November 2024
- Effective
- 1 January 2025
- Authority
- Magyar Közlöny (Official Gazette of Hungary)
- Verified
- Fetched from official source · high confidence
Hungarian VAT-registered gas traders (taxable dealers) buying and selling gas through the natural-gas system.
No action — monitoring only.
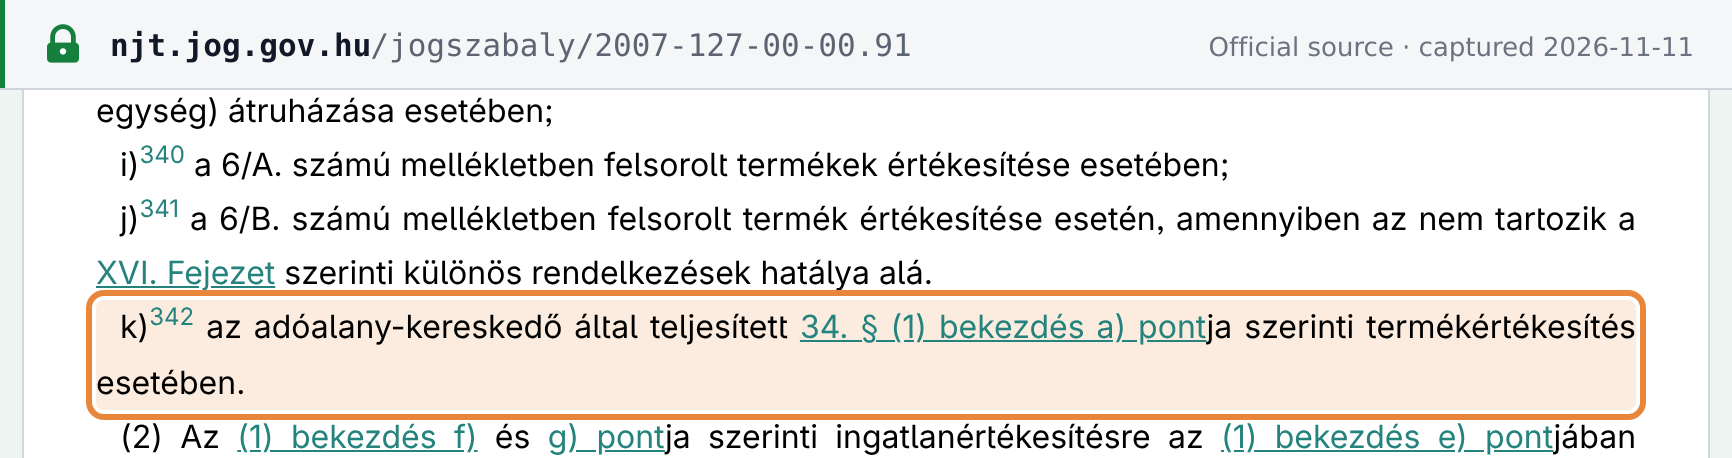
Act LV of 2024 (adopted 26 November 2024, promulgated in Magyar Közlöny on 28 November 2024) extended the domestic reverse charge (Áfa tv. s.142(1)(k)) from 1 January 2025 to gas supplied through the natural-gas system by a taxable dealer to another taxable dealer. Both supplier and purchaser must make the declarations set out in Annex 6/C (s.142(9)). Transitional rules (s.369) keep the old treatment where tax became chargeable before 1 January 2025, including advance payments. Act LIV of 2025 later restated point (k) to require the buyer's prior written declaration that it is a dealer.
What changed in detail
Act LV of 2024 amending certain tax laws, adopted on 26 November 2024 and promulgated in Magyar Közlöny on 28 November 2024, inserted a new point (k) into section 142(1) of the Hungarian VAT Act (Act CXXVII of 2007) by its section 41(1), with effect from 1 January 2025.
Section 142(1) lists the domestic supplies on which the buyer, not the seller, pays the VAT. Point (k) adds supplies made by a taxable dealer of goods under section 34(1)(a): gas supplied through a natural-gas system in the EU territory or any network connected to it, when the buyer is itself a taxable dealer. The seller invoices without VAT and the buying dealer self-assesses.
Under section 142(9), both supplier and purchaser of goods falling under points (i) to (k) must make the declarations set out in Annex 6/C. A transitional rule (section 369) keeps the previous treatment where the tax became chargeable before 1 January 2025, including on advance payments. The proof shown is the time-state version of the VAT Act in force from 2 January to 28 February 2025 on the National Legislation Database (njt.jog.gov.hu), which carries point (k) as originally enacted.
What it means
The rule is in force but no longer in its original wording. Act LIV of 2025 restated point (k) (its section 29) so that the buyer must also declare, in advance and in writing, that it qualifies as a taxable dealer; the current consolidated Act carries that text. Sellers of network gas should therefore hold the buyer’s written dealer declaration before invoicing without VAT. The measure is an anti-fraud tool for wholesale energy trading, where missing-trader schemes thrive on VAT charged between dealers; it does not reach supplies to end consumers.
Proof
az adóalany-kereskedő által teljesített 34. § (1) bekezdés a) pontja szerinti termékértékesítés esetében.in the case of a supply of goods under section 34(1)(a) made by a taxable dealer.
 Source snapshot of the official page. Open full size ↗