Hungary cuts VAT on beef and bovine offal from 27% to 5% from 1 January 2026
This page records one dated change. For the rules in Hungary as they stand today, see the Hungary guide →
- Jurisdiction
- Hungary
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 19 November 2025
- Effective
- 1 January 2026
- Instrument
- HU-ACT-LXXXIII-2025
- Authority
- Magyar Közlöny (Official Gazette of Hungary)
- Verified
- Fetched from official source · high confidence
Meat processors, wholesalers, retailers and caterers selling fresh, chilled or frozen beef, bovine offal or slaughter by-products in Hungary.
No action — monitoring only.
Act LXXXIII of 2025 on reducing administration and harmonisation in tax laws (adopted 18 November 2025, promulgated in Magyar Közlöny on 19 November 2025) added row 60 to Annex 3 Part I of the VAT Act. From 1 January 2026, meat, edible offal and slaughter by-products of domesticated bovine animals, fresh, chilled or frozen, are taxed at 5% instead of 27%. Half and quarter bovine carcasses were already at 5% (rows 31-38).
What changed in detail
Act LXXXIII of 2025 on amending certain tax laws to reduce administration and for legal harmonisation, adopted on 18 November 2025 and promulgated in Magyar Közlöny on 19 November 2025, added a new row 60 to Part I of Annex 3 of the Hungarian VAT Act (Act CXXVII of 2007), the list of goods taxed at the 5% reduced rate.
Row 60 covers meat, slaughter by-products and offal of domesticated bovine animals fit for human consumption, fresh, chilled or frozen. The consolidated Act on the National Legislation Database (njt.jog.gov.hu) lists it against customs tariff codes 0201 20 90, 0201 30 00, 0202 20 90, 0202 30 50, 0202 30 90, 0206 10, 0206 21 00, 0206 22 00 and 0206 29 (in each case “from”, that is, only the part of the code matching the description). From 1 January 2026 these goods are taxed at 5% instead of the 27% standard rate.
Half and quarter bovine carcasses were already at 5% under rows 31 to 38 of the same Annex. The new row extends the reduced rate to beef cuts and offal.
What it means
The rate is in force as of November 2026 and has applied to supplies since 1 January 2026; the transitional question — which rate applies to a supply straddling the date — is now spent. The scope follows the tariff codes, so only fresh, chilled or frozen meat and offal benefit; prepared or preserved beef products fall outside row 60. Point-of-sale and invoicing systems should map beef lines by tariff code rather than by product name. Suppliers that kept a 27% default for beef cuts after January 2026 overcharged VAT and should correct those invoices.
Proof
Háziasított szarvasmarha élelmezési célra alkalmas húsa, vágási mellékterméke és belsősége frissen, hűtve vagy fagyasztvaMeat, slaughter by-products and offal of domesticated bovine animals fit for human consumption, fresh, chilled or frozen
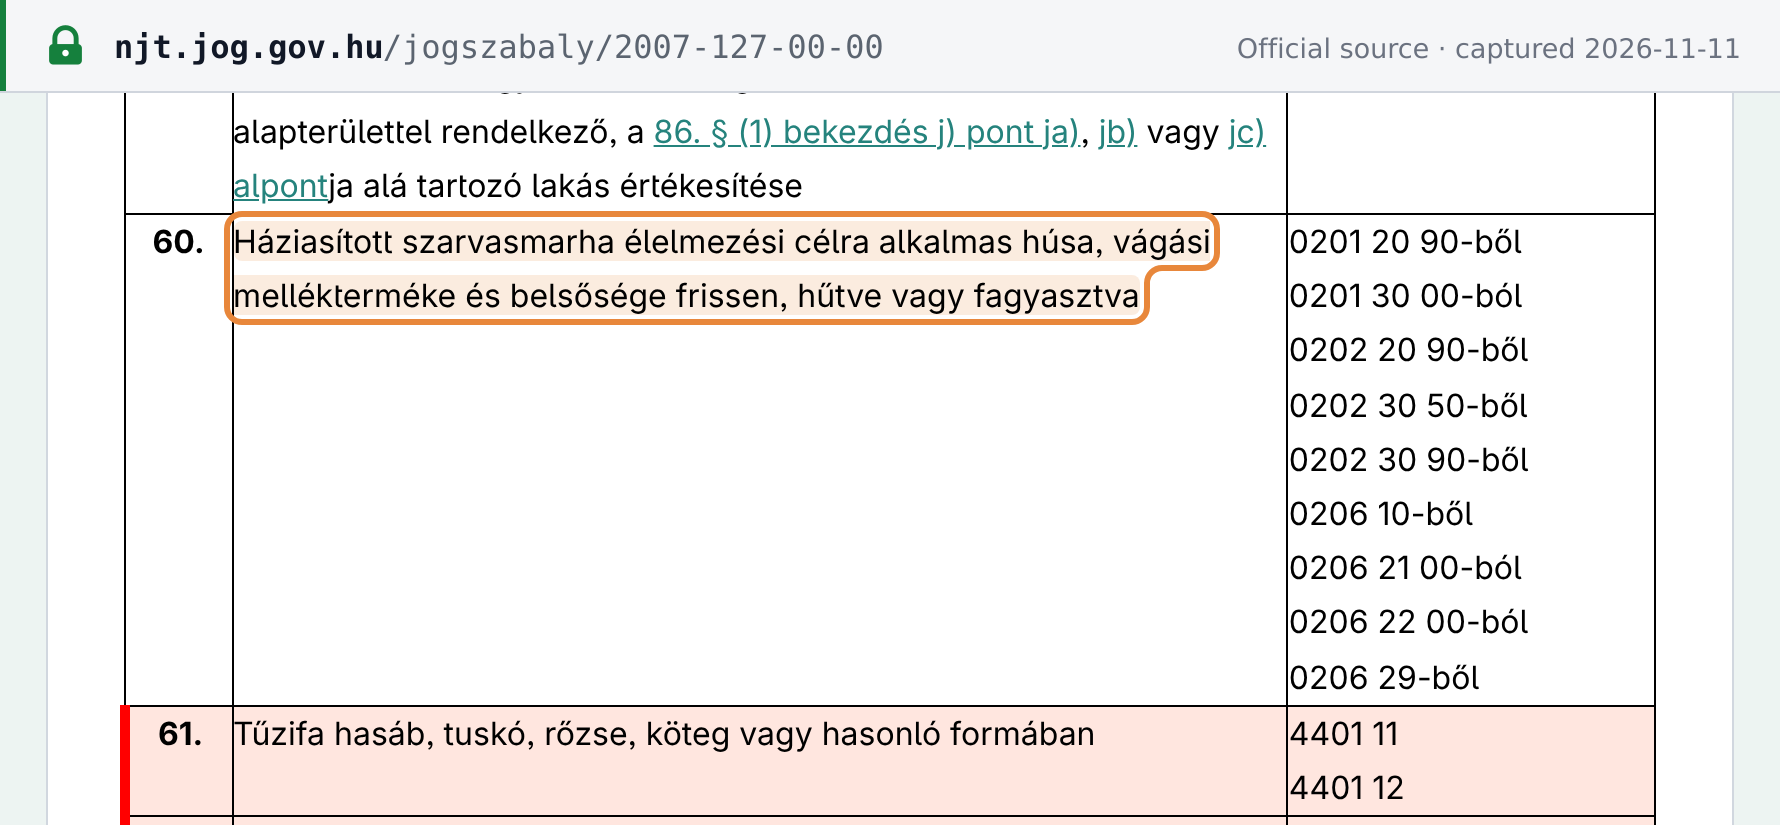 Source snapshot of the official page. Open full size ↗