Indonesia restates its special VAT bases and fixed VAT amounts for the 12% rate in PMK 11/2025
This page records one dated change. For the rules in Indonesia as they stand today, see the Indonesia guide →
- Jurisdiction
- Indonesia
- Tax
- PPN
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 4 February 2025
- Effective
- 4 February 2025
- Instrument
- ID-MINISTERIAL-REGULATION-11-2025
- Authority
- Directorate General of Taxes (DJP), Indonesia
- Verified
- Fetched from official source · high confidence
VAT-registered businesses whose supplies use a deemed base (nilai lain) or a fixed VAT amount (besaran tertentu), for example own use and gifts, films, phone credit and vouchers, subsidised fertiliser, tobacco, used vehicles, gold jewellery, farm produce and certain LPG (crypto assets only until 31 July 2025).
No action — clarification of DPP nilai lain formula applies retroactively from 1 January 2025.
PMK 11/2025 (signed and promulgated 4 February 2025, BN 2025/78) brought the separate rules on 'other value' tax bases (DPP nilai lain) and fixed-rate VAT amounts (besaran tertentu) into one regulation, restated for the 12% rate as 12% x 11/12 x base (or a set formula x 12% x 11/12). It covers own use and free gifts, films, phone credit and vouchers, subsidised fertiliser, tobacco products, used vehicles, gold jewellery, agricultural produce, certain LPG and crypto-asset trading and mining, among others: the items that PMK 131/2024 left to their own rules. Deliveries from 1 January 2025 follow PMK 11/2025; earlier deliveries follow the old regulations.
What changed in detail
Minister of Finance Regulation (PMK) No. 11 of 2025 governs “other value” tax bases (DPP nilai lain) and fixed VAT amounts (besaran tertentu). It was set, promulgated and brought into force on 4 February 2025 (Berita Negara 2025 No. 78). The Directorate General of Taxes (DJP) explained it in press release SP-4/2025 on 18 February 2025.
PMK 131/2024 applied the 12% rate from 1 January 2025 but excluded supplies already covered by their own nilai-lain or besaran-tertentu regulations. Those rules had been spread over several separate PMKs. PMK 11/2025 brings them into one regulation and restates them for the 12% rate, in two forms:
- Deemed base: 12% × 11/12 × the relevant base.
- Fixed amount: a set percentage × 11/12 × 12% × the price.
The items covered include:
- own use and free gifts, and films;
- phone credit, starter packs and vouchers;
- LPG, tobacco products (9.9% of the retail price) and subsidised fertiliser;
- used motor vehicles and agricultural produce;
- repossessed collateral and gold jewellery;
- insurance agents, construction on one’s own account (membangun sendiri), and crypto-asset trading and mining.
According to SP-4/2025, deliveries before 1 January 2025 follow the earlier regulations. Deliveries from 1 January 2025 follow PMK 11/2025.
PMK 53/2025, signed on 25 July 2025 and in force from 1 August 2025, amended PMK 11/2025 and deleted the crypto-asset provisions (Pasal 343 and Pasal 354 of PMK 81/2024 as inserted by PMK 11/2025). The crypto-asset trading and mining rules above therefore applied only from 1 January to 31 July 2025. PMK 53/2025 kept the insurance-agent and self-build formulas unchanged.
What it means
This regulation is the companion to PMK 131/2024 (id-ppn-12pct-pmk131-2024). It does not supersede it. Together they kept the effective VAT burden on these special-regime items in line with the 11% that ordinary supplies bear, despite the 12% headline rate. Although it was promulgated in February, it governs these items from 1 January 2025, the same day the 12% rate started. It remains the reference for these regimes as amended by PMK 53/2025, which means crypto assets are no longer covered: since 1 August 2025 they fall outside these VAT rules and are treated as financial assets under the PMK 50, 53 and 54 of 2025 package.
Proof
PMK-11/2025 tersebut ditetapkan dan mulai berlaku pada tanggal 4 Februari 2025.PMK-11/2025 was enacted and came into force on 4 February 2025.
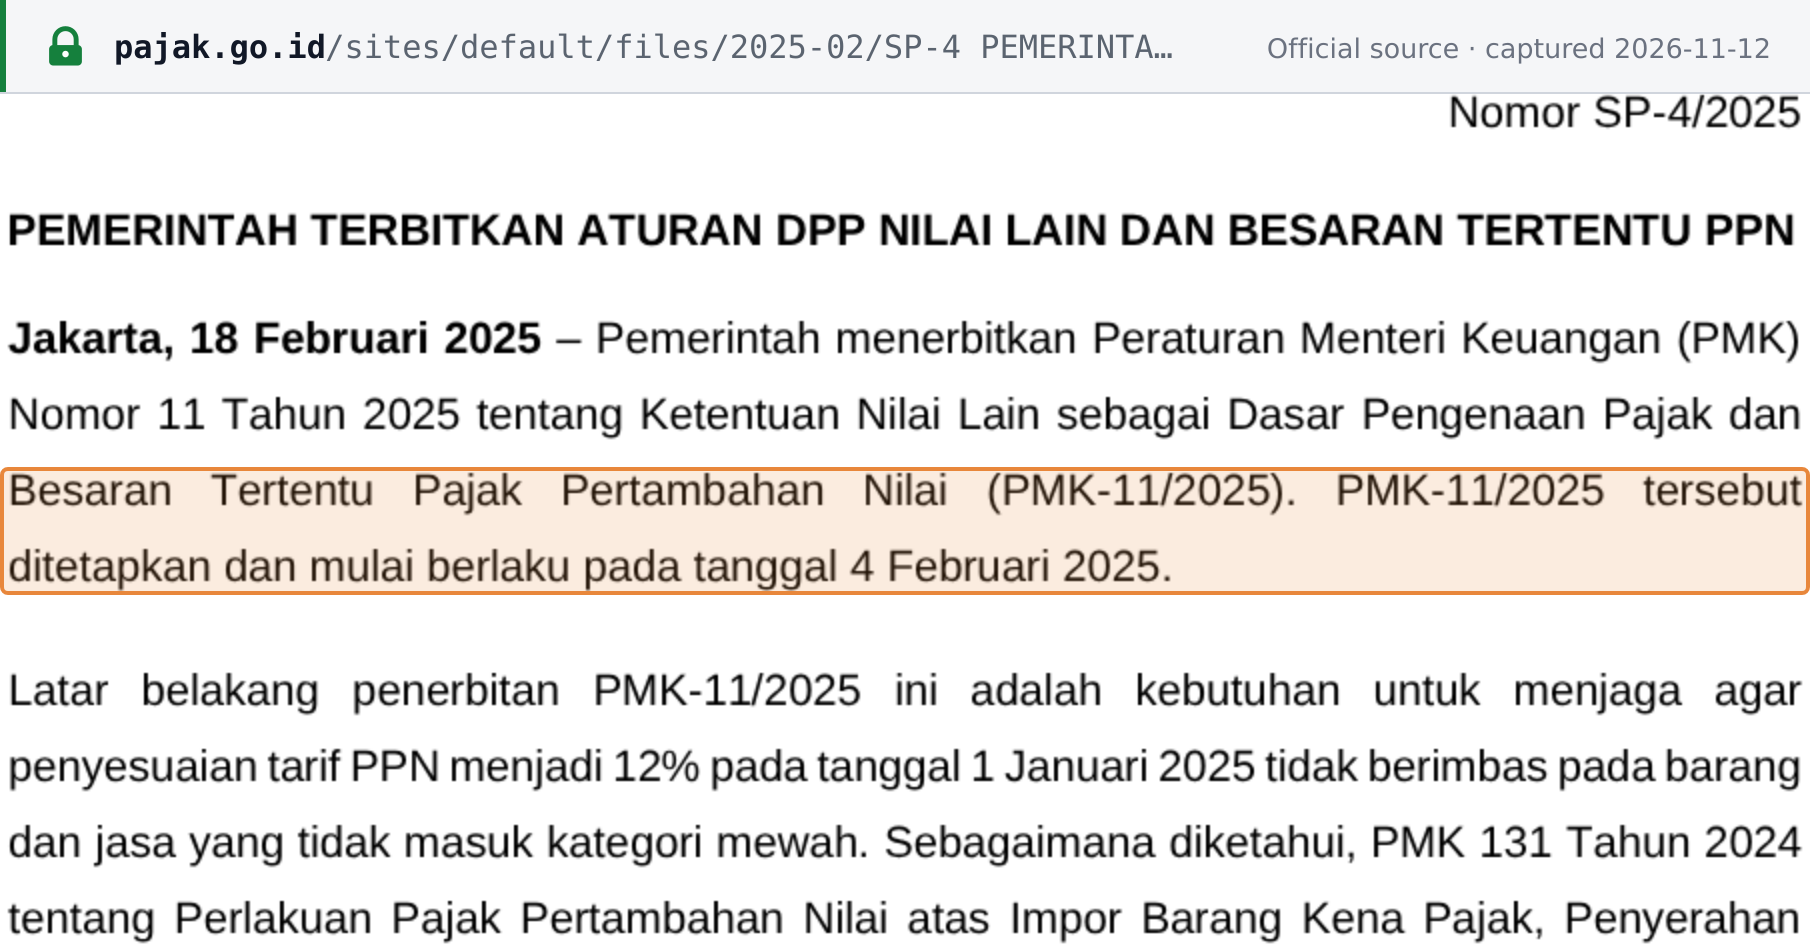 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Siaran Pers Direktorat Jenderal Pajak Nomor SP-4/2025, 18 Februari 2025 · www.pajak.go.id