Ireland raises the flat-rate farmer addition from 4.8% to 5.1% for 2025
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Rate change
- Status
- In force
- Impact
- FYI
- Announced
- 12 November 2024
- Effective
- 1 January 2025
- Authority
- Irish Statute Book (electronic Irish Statute Book, Office of the Attorney General)
- Verified
- Fetched from official source · high confidence
Unregistered flat-rate farmers in Ireland, and the VAT-registered businesses that buy agricultural produce or services from them.
No action required — this flat-rate addition (5.1%) was superseded by Finance Act 2025 s.73 reducing it to 4.5% from 1 January 2026 (shipped as ie-flat-rate-farmer-addition-4-5pc-2026).
Section 83 of Ireland's Finance Act 2024 (Act No. 43/2024), signed 12 November 2024, changed the flat-rate addition charged by unregistered flat-rate farmers from 4.8% to 5.1%, with effect from 1 January 2025.
What changed in detail
Section 83 of the Finance Act 2024 (No. 43 of 2024), signed on 12 November 2024, amends section 86(1) of the Value-Added Tax Consolidation Act 2010, with effect from 1 January 2025. It replaces “4.8 per cent” with “5.1 per cent”.
Section 86(1) sets the flat-rate addition. A farmer who is not registered for VAT adds this percentage to the price when supplying agricultural produce or services to a VAT-registered customer, to compensate for input VAT the farmer cannot reclaim. The customer can deduct the addition as if it were VAT.
The 4.8% being replaced had applied for 2024 under section 62 of the Finance (No. 2) Act 2023.
What it means
This record is spent and has been superseded. Finance Act 2025, section 73, cut the addition to 4.5% from 1 January 2026, and that rate is in force now (Ireland cuts the flat-rate addition to 4.5%). The Finance (No. 2) Bill 2026 proposes 4.8% from 1 January 2027 (the 2027 proposal).
So 5.1% applied only to supplies made in calendar year 2025. An invoice from a flat-rate farmer dated in 2025 should show 5.1%. If one dated in 2026 still shows 5.1%, the addition was overcharged, and so was the amount the buyer deducted.
Proof
83. Section 86(1) of the Principal Act is amended, with effect from 1 January 2025, by the substitution of “5.1 per cent” for “4.8 per cent”.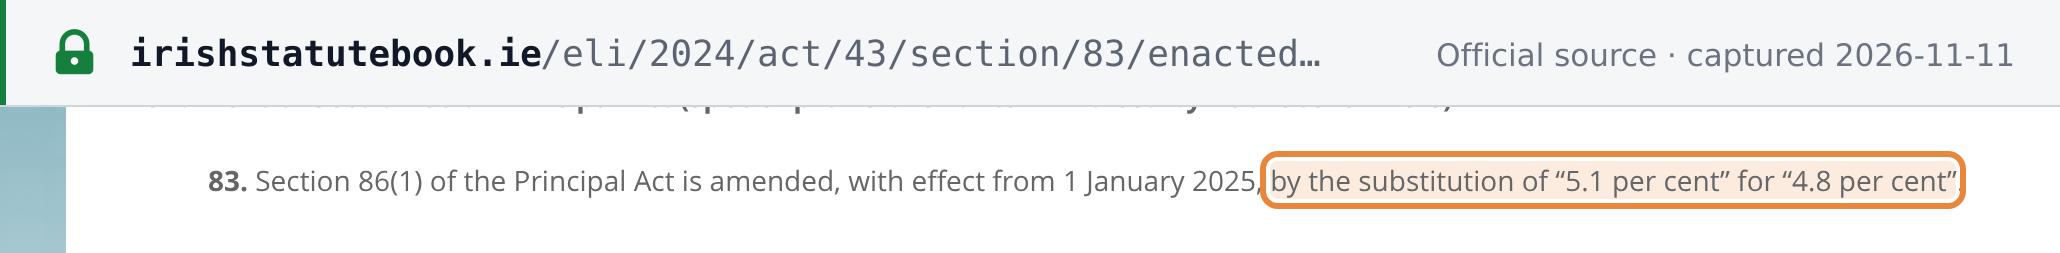 Source snapshot of the official page. Open full size ↗
Sources
What this replaces
- Ireland cuts the flat-rate farmer addition from 5% to 4.8% for 2024 effective 1 January 2024