Ireland raises its VAT registration thresholds to €80,000 for goods and €40,000 for services
This page records one dated change. For the rules in Ireland as they stand today, see the Ireland guide →
- Jurisdiction
- Ireland
- Tax
- VAT
- Change type
- Threshold
- Status
- In force
- Impact
- FYI
- Announced
- 18 December 2023
- Effective
- 1 January 2024
- Authority
- Irish Statute Book (electronic Irish Statute Book, Office of the Attorney General)
- Verified
- Fetched from official source · high confidence
Irish-established businesses with turnover near the registration thresholds, which apply to goods and services separately.
No action required — this threshold (€80,000 / €40,000) was superseded by the Finance Act 2024 increase to €85,000 / €42,500 from 1 January 2025.
Section 58 of Ireland's Finance (No. 2) Act 2023 (Act No. 39/2023), signed 18 December 2023, raised the VAT registration threshold for goods from €75,000 to €80,000 and for services from €37,500 to €40,000, with effect from 1 January 2024.
What changed in detail
Section 58 of the Finance (No. 2) Act 2023 (No. 39 of 2023), signed on 18 December 2023, amends two definitions in section 2(1) of the Value-Added Tax Consolidation Act 2010, with effect from 1 January 2024:
- the goods threshold rises from €75,000 to €80,000;
- the services threshold rises from €37,500 to €40,000.
These are the turnover limits above which a business established in Ireland must register for VAT. The goods threshold applies where at least 90% of turnover comes from supplying goods. The services threshold applies to everyone else. A business below its threshold can still register voluntarily.
What it means
This record is spent and has been superseded. Finance Act 2024, section 78, raised the thresholds again from 1 January 2025, to €85,000 for goods and €42,500 for services (Ireland raises its VAT thresholds to €85,000 / €42,500). Those figures are still in force.
The €80,000 and €40,000 figures matter only when testing whether a business should have registered during calendar year 2024. Registration is judged against the threshold in force in the period the turnover was made.
Proof
58. Section 2 of the Principal Act is amended, in subsection (1), with effect from 1 January 2024— (a) in the definition of “goods threshold”, by the substitution of “€80,000” for “€75,000”, and (b) in the definition of “services threshold”, by the substitution of “€40,000” for “€37,500”.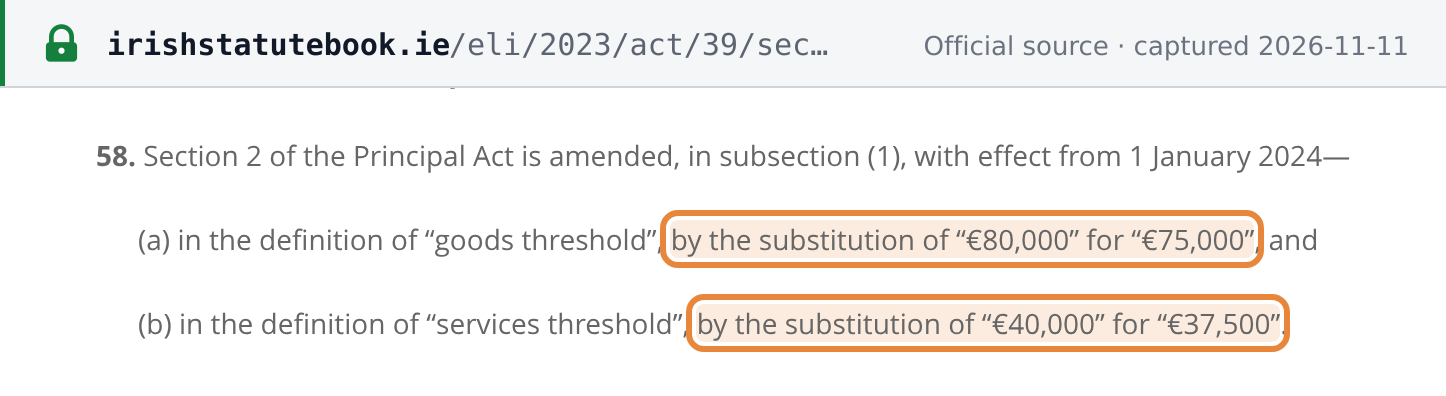 Source snapshot of the official page. Open full size ↗