Italy requires payment service providers to record and report cross-border payment data for CESOP from 2024
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 3 November 2023
- Effective
- 1 January 2024
- Instrument
- IT-DECRETO-LEGISLATIVO-153-2023
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Payment service providers for which Italy is the home Member State, and providers serving other Member States for services where Italy is the host Member State, that handle more than 25 cross-border payments to one payee in a quarter.
No action — monitoring only.
Legislative Decree 18 October 2023, n. 153 (GU n. 257, 3 November 2023) implemented EU Directive 2020/284 by inserting Title II-bis (arts. 40-bis to 40-sexies) into the Italian VAT Decree (DPR 633/1972). Payment service providers with Italy as home Member State must quarterly record and report cross-border payment data to the Agenzia delle Entrate for transmission to the CESOP central system; obligations apply from 1 January 2024.
What changed in detail
Legislative Decree 18 October 2023, n. 153, published in the Gazzetta Ufficiale n. 257 of 3 November 2023, transposes Council Directive (EU) 2020/284 into Italian law. Article 1 inserts a new Title II-bis, articles 40-bis to 40-sexies, into the VAT Decree, DPR 633/1972.
Article 40-bis defines the terms used, including payment service provider, payment service, payer, payee, home and host Member State, IBAN and BIC. Article 40-ter requires payment service providers to keep records of payees and of the cross-border payments they handle each quarter. A payment is cross-border when the payer is located in an EU Member State and the payee in another Member State, a third territory or a third country. The duty applies only where, in a calendar quarter, a provider handles more than twenty-five cross-border payments to the same payee, counted per Member State and per identifier. The records must be kept for three calendar years from the end of the year of the payment.
Article 40-quater requires providers for which Italy is the home Member State, and providers that offer payment services in other Member States, limited to the services for which Italy is the host Member State, to make that information available to the Agenzia delle Entrate, which passes it to the EU’s central electronic system of payment information (CESOP). The obligations apply to payment services provided from 1 January 2024.
What it means
The 1 January 2024 start date has passed and the regime has applied since then. It falls on payment service providers, not on merchants. Merchants who take more than 25 cross-border payments a quarter from EU payers should expect that data to reach tax authorities, which can then compare it with what the merchant has declared.
The rule is still in force in substance, but its legal home moves. Articles 40-bis to 40-sexies of DPR 633/1972 are among the provisions abrogated from 1 January 2027 by the VAT Testo unico, D.Lgs. 10/2026 (record), which re-points references to its own articles.
Proof
più di venticinque pagamenti transfrontalieri allo stesso beneficiariomore than twenty-five cross-border payments to the same payee
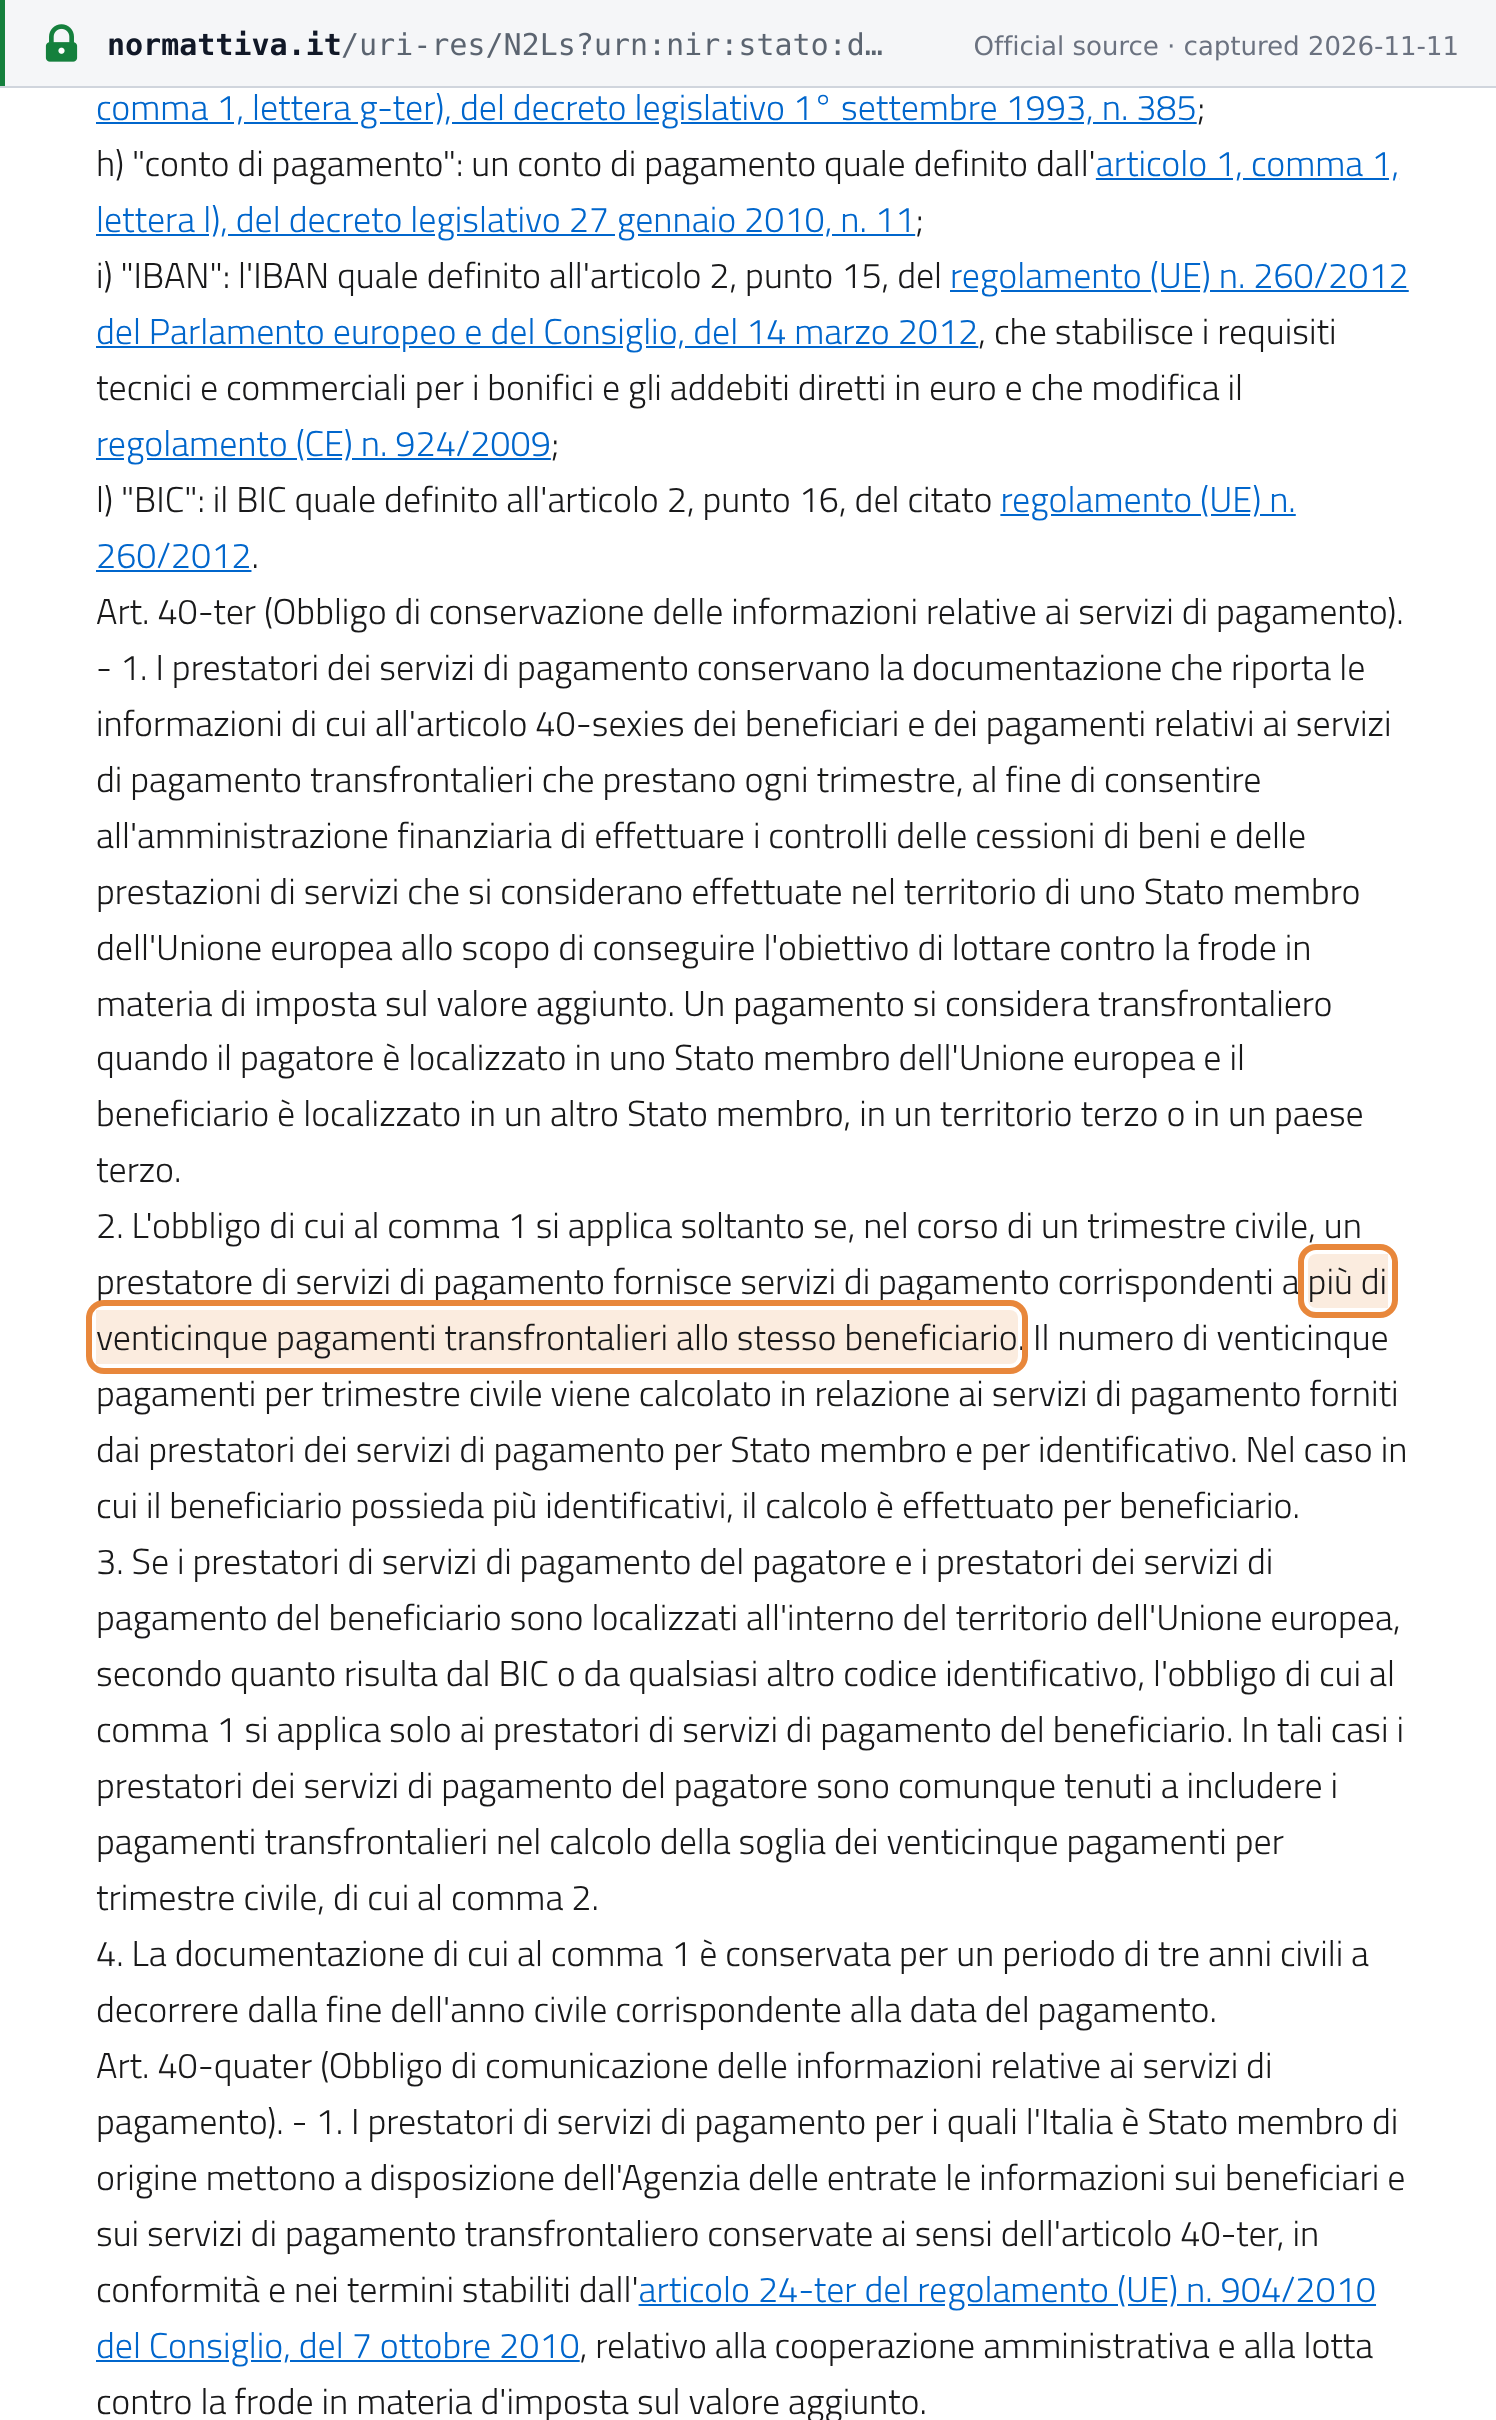 Source snapshot of the official page. Open full size ↗