Italy widens the logistics reverse charge and extends the client-pays VAT option to subcontractors
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 17 June 2025
- Effective
- 18 June 2025
- Instrument
- IT-DECRETO-LEGGE-84-2025
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Contractors and subcontractors supplying services to goods-transport, goods-handling and logistics businesses in Italy, and those client businesses.
No action — monitoring only.
Decree-Law 17 June 2025, n. 84 (GU n. 138, 17 June 2025), Art. 9, in force 18 June 2025 and converted with amendments by Law 30 July 2025, n. 108 (GU n. 177, 1 August 2025), amended the reverse-charge provision of DPR 633/1972 art. 17, sixth paragraph, lett. a-quinquies) (as replaced by L. 207/2024). It deleted the condition of predominant use of labour at the client's premises with the client's capital goods, so the provision covers services rendered under contracts/subcontracts to goods-transport, goods-handling and logistics businesses. The conversion law also deleted the exclusion for employment agencies under D.Lgs. 276/2003 art. 4, from 2 August 2025. Effectiveness of the reverse charge remains conditional on an EU Council derogation under Directive 2006/112/EC art. 395. The optional regime of L. 207/2024 comma 59, under which the client pays the VAT on the supplier's behalf, was extended to relations between the main contractor and subcontractors, with subcontractors remaining jointly liable.
What changed in detail
Decree-Law 17 June 2025, n. 84, published in the Gazzetta Ufficiale n. 138 of 17 June 2025 and in force from 18 June 2025, Article 9, amends the logistics reverse-charge rule that L. 207/2024 had written into letter a-quinquies) of the sixth paragraph of article 17 of DPR 633/1972. The decree was converted with amendments by Law 30 July 2025, n. 108 (Gazzetta Ufficiale n. 177 of 1 August 2025).
Comma 1 deletes the condition that the services be characterised by predominant use of labour at the client’s premises with the client’s capital goods. The provision now covers services rendered under contracts, subcontracts and similar arrangements to businesses carrying out goods transport, goods handling and logistics. The conversion law also deleted, from 2 August 2025, the exclusion for employment agencies under article 4 of D.Lgs. 276/2003.
Comma 2 amends commi 58 and 59 of article 1 of L. 207/2024. The reverse charge still takes effect only after the Council of the EU authorises a derogation under Article 395 of Directive 2006/112/EC. The interim option, under which the client pays the VAT in the supplier’s name and on its behalf, may now also be exercised between the main contractor and any subcontractors. In that case the subcontractors remain jointly liable for the tax due.
What it means
The change widens the earlier rule (record) rather than replacing it. Any service contract with a logistics business falls in scope, whether or not it is labour-intensive, and the client-pays mechanism can now run down a subcontracting chain. That chain is where unpaid VAT tended to arise.
The rule is still conditional. As of November 2026, Normattiva’s consolidated article 17 still makes letter a-quinquies) subject to the Article 395 authorisation, so the interim option remains the working mechanism. The DPR 633/1972 provision and L. 207/2024 commi 57 to 63 are replaced from 1 January 2027 by the VAT Testo unico, D.Lgs. 10/2026 (record).
Proof
La medesima opzione può essere esercitata nei rapporti tra l'appaltatore e gli eventuali subappaltatori.The same option may be exercised in relations between the main contractor and any subcontractors.
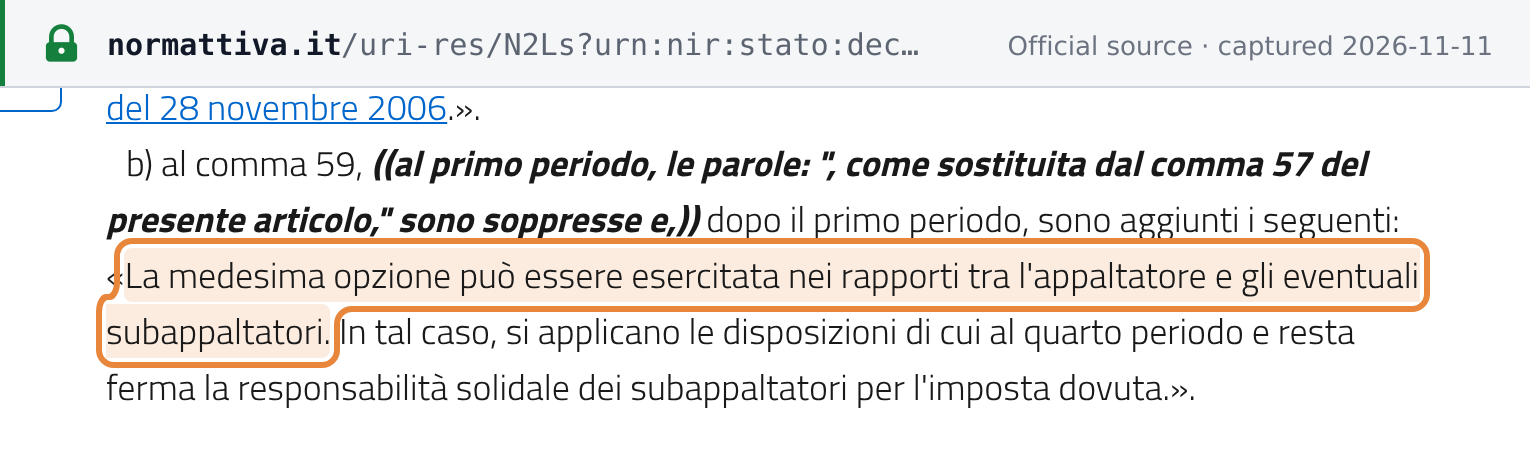 Source snapshot of the official page. Open full size ↗