Italy limits the cost-based VAT base for barter to contracts concluded or renewed from 2026
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 27 March 2026
- Effective
- 28 March 2026
- Instrument
- IT-DECREE-LAW-38-2026
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Italian VAT payers carrying out barter (permuta) or payment-in-kind transactions under contracts running into 2026.
No action — spent. The DL limited the cost-based barter base to contracts concluded or renewed from 1 January 2026; since the conversion law (L. 88/2026, from 23 May 2026) the taxable base is the contract value with a cost floor.
Decreto-legge 27 marzo 2026, n. 38 (GU n. 72 of 27 March 2026, in force 28 March 2026), Art. 1, rewrote Art. 1(139) of Legge 199/2025 so that the cost-based VAT taxable base for barter transactions introduced by comma 138 applies only to transactions carried out under contracts concluded or renewed from 1 January 2026. It saved earlier conduct and conduct conforming to comma 138 up to its entry into force, with no refunds. The conversion law, Legge 22 maggio 2026, n. 88 (GU n. 117 of 22 May 2026), later repealed commi 138–139 and replaced the rule with a contract-value base.
What changed in detail
Decree-Law 27 March 2026, n. 38 (Gazzetta Ufficiale n. 72 of 27 March 2026, in force 28 March 2026), Article 1, headed “Modifiche alla decorrenza del nuovo regime IVA delle operazioni permutative”, changes when the 2026 Budget Law’s new barter rule starts.
Law 199/2025, Article 1, comma 138, had set the VAT taxable base of barter and payment-in-kind supplies at the total costs referable to each supply, in place of normal value (record). Its comma 139 applied that rule to transactions carried out from 1 January 2026.
Comma 1 of Article 1 replaces comma 139. The cost-based base now applies only to transactions carried out under contracts concluded or renewed from 1 January 2026. Transactions under older contracts stay on the previous base.
Comma 2 saves conduct adopted before 1 January 2026, and conduct that followed comma 138 between 1 January 2026 and the decree’s entry into force. In neither case is VAT refunded or the tax already settled adjusted.
What it means
This step is spent. The conversion law, Law 22 May 2026, n. 88 (Gazzetta Ufficiale n. 117 of 22 May 2026), rewrote Article 1 of the decree. It repealed commi 138 and 139 and set the barter base at the value stated in the contract, with the total costs as a floor. The DL text applied only from 28 March to the conversion law’s entry into force, and its saving clause protects what taxpayers did in that window.
For current treatment, read the Budget Law record, which follows the rule through to the conversion law, and the VAT Testo unico, which carries the contract-value wording from 1 January 2027 (record).
Proof
All'articolo 1 della legge 30 dicembre 2025, n. 199, il comma 139 è sostituto dal seguente: «139. Le disposizioni di cui al comma 138 si applicano alle operazioni effettuate in esecuzione di contratti stipulati o rinnovati a decorrere dal 1° gennaio 2026.»In Article 1 of Law 30 December 2025, n. 199, paragraph 139 is replaced by the following: "139. The provisions of paragraph 138 apply to transactions carried out under contracts concluded or renewed from 1 January 2026."
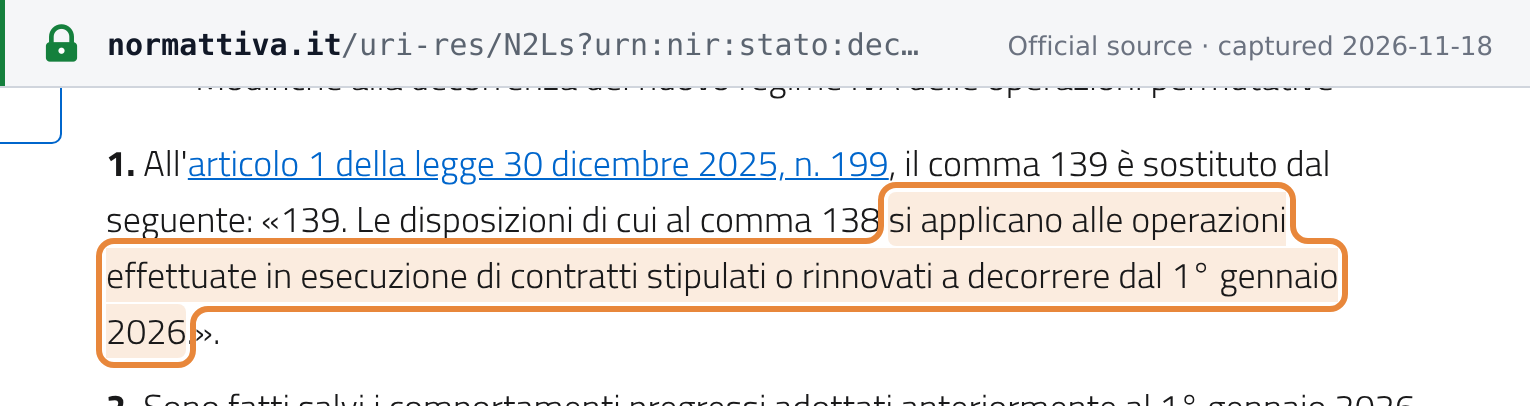 Source snapshot of the official page. Open full size ↗