Italy makes the SdI e-invoicing ban for Sistema Tessera Sanitaria invoices permanent
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- E-invoicing
- Status
- In force
- Impact
- FYI
- Announced
- 12 June 2025
- Effective
- 13 June 2025
- Instrument
- IT-LEGISLATIVE-DECREE-81-2025
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
Doctors, pharmacies, clinics and other healthcare providers that must send invoice data to the Sistema Tessera Sanitaria for the pre-filled income-tax return.
No action — healthcare providers that report to the Sistema Tessera Sanitaria keep issuing non-SdI invoices for those services; the ban no longer needs annual renewal.
Decreto legislativo 12 giugno 2025, n. 81 (GU n. 134 of 12 June 2025, in force 13 June 2025), Art. 2, removed the list of tax years (2019–2025) from Art. 10-bis(1) of D.L. 119/2018, making permanent the rule that persons who must send data to the Sistema Tessera Sanitaria may not issue SdI electronic invoices for invoices whose data go to that system.
What changed in detail
Legislative Decree 12 June 2025, n. 81 (Gazzetta Ufficiale n. 134 of 12 June 2025, in force 13 June 2025), Article 2, amends Article 10-bis(1) of Decree-Law 119/2018.
Article 10-bis bars persons who must send data to the Sistema Tessera Sanitaria, the health-expense data system that feeds the pre-filled income-tax return, from issuing electronic invoices through the Sistema di Interscambio (SdI) for invoices whose data go to that system. Until this change the ban applied only for listed tax periods, most recently 2019 to 2025, and had to be renewed.
Article 2 replaces the opening words “Per i periodi d’imposta 2019, 2020, 2021, 2022, 2023, 2024 e 2025, i soggetti” with “I soggetti”. The ban now applies with no end date.
What it means
The rule is still in force. Healthcare providers keep issuing paper or non-SdI electronic invoices to patients for services whose data go to the Sistema Tessera Sanitaria, and keep reporting those data to the Sistema TS. That is the main carve-out from Italy’s general B2C e-invoicing obligation, and it no longer depends on a yearly extension. Invoices that are not reported to the Sistema TS, such as most B2B invoices from the same providers, still go through the SdI.
From 1 January 2027 the VAT Testo unico, D.Lgs. 10/2026, abrogates Article 10-bis and restates the permanent ban in its Article 78(1) (record).
Proof
All'articolo 10-bis, comma 1, primo periodo, del decreto-legge 23 ottobre 2018, n. 119, convertito, con modificazioni, dalla legge 17 dicembre 2018, n. 136, le parole: «Per i periodi d'imposta 2019, 2020, 2021, 2022, 2023, 2024 e 2025, i soggetti» sono sostituite dalle seguenti: «I soggetti».In Article 10-bis, paragraph 1, first sentence, of Decree-Law 23 October 2018, n. 119, converted with amendments by Law 17 December 2018, n. 136, the words "For the tax periods 2019, 2020, 2021, 2022, 2023, 2024 and 2025, the persons" are replaced by the following: "The persons".
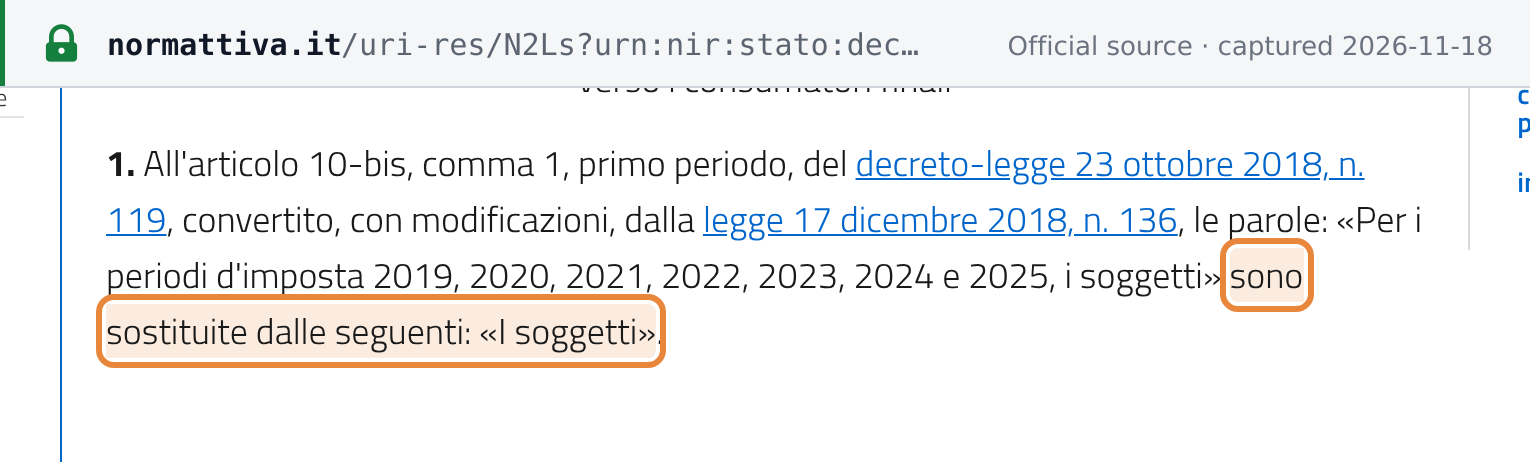 Source snapshot of the official page. Open full size ↗