Italy cuts VAT administrative penalties for violations committed from 1 September 2024
This page records one dated change. For the rules in Italy as they stand today, see the Italy guide →
- Jurisdiction
- Italy
- Tax
- VAT
- Change type
- Compliance
- Status
- In force
- Impact
- FYI
- Announced
- 28 June 2024
- Effective
- 1 September 2024
- Instrument
- IT-LEGISLATIVE-DECREE-87-2024
- Authority
- Gazzetta Ufficiale della Repubblica Italiana
- Verified
- Fetched from official source · high confidence
All Italian VAT payers, for VAT violations committed from 1 September 2024.
No action — applies to VAT violations committed from 1 September 2024. Use the reduced percentages (120% omitted return, 70% unfaithful return, 70% documentation/registration and unlawful-deduction violations, 25% late payment) when estimating exposure or voluntary-disclosure (ravvedimento) costs.
Decreto legislativo 14 giugno 2024, n. 87 (GU n. 150 of 28 June 2024), Art. 2, revised the VAT administrative penalties in D.Lgs. 471/1997 for violations committed from 1 September 2024 (Art. 5): omitted VAT return (Art. 5(1)) from 120–240% to 120% of the tax, minimum EUR 250; unfaithful return (Art. 5(4)) from 90–180% to 70%, minimum EUR 150; failure to document or record taxable transactions (Art. 6(1)) from 90–180% to 70%; unlawful input-VAT deduction (Art. 6(6)) from 90% to 70%; late payment (Art. 13(1)) from 30% to 25%.
What changed in detail
Legislative Decree 14 June 2024, n. 87 (Gazzetta Ufficiale n. 150 of 28 June 2024) revises the tax penalty system. Article 2 amends D.Lgs. 471/1997, the administrative penalties for direct-tax and VAT violations. Under Article 5, the new penalties apply to violations committed from 1 September 2024.
For VAT:
- Omitted VAT return (Article 5(1)): from 120–240% of the tax due to 120%, with a minimum of EUR 250.
- Unfaithful VAT return (Article 5(4)): from 90–180% of the difference to 70%, with a minimum of EUR 150.
- Failure to document or record taxable transactions (Article 6(1)): from 90–180% to 70% of the tax.
- Unlawful deduction of input VAT (Article 6(6)): from 90% to 70%.
- Late or omitted payment (Article 13(1)): from 30% to 25% of the amount not paid.
The proof above is letter l), the late-payment change, in the Gazzetta’s text.
What it means
These percentages are the ones in force today, and they drive the cost of any voluntary correction (ravvedimento operoso), because ravvedimento reduces the base penalty by a fraction. A late VAT payment now starts from 25% rather than 30%. Violations committed before 1 September 2024 stay under the old percentages.
D.Lgs. 471/1997 is itself on its way out. Normattiva shows it abrogated from 1 January 2027 by the Testo unico delle sanzioni tributarie, D.Lgs. 5 November 2024, n. 173, whose start was moved to that date by DL 31 December 2025, n. 200. From then, cite the penalty by its Testo unico article, alongside the VAT Testo unico that applies from the same day (record).
Proof
l) all’articolo 13: 1) al comma 1, le parole: «pari al trenta» sono sostituite dalle seguenti: «pari al venticinque»l) in Article 13: 1) in paragraph 1, the words "equal to thirty" are replaced by the following: "equal to twenty-five"
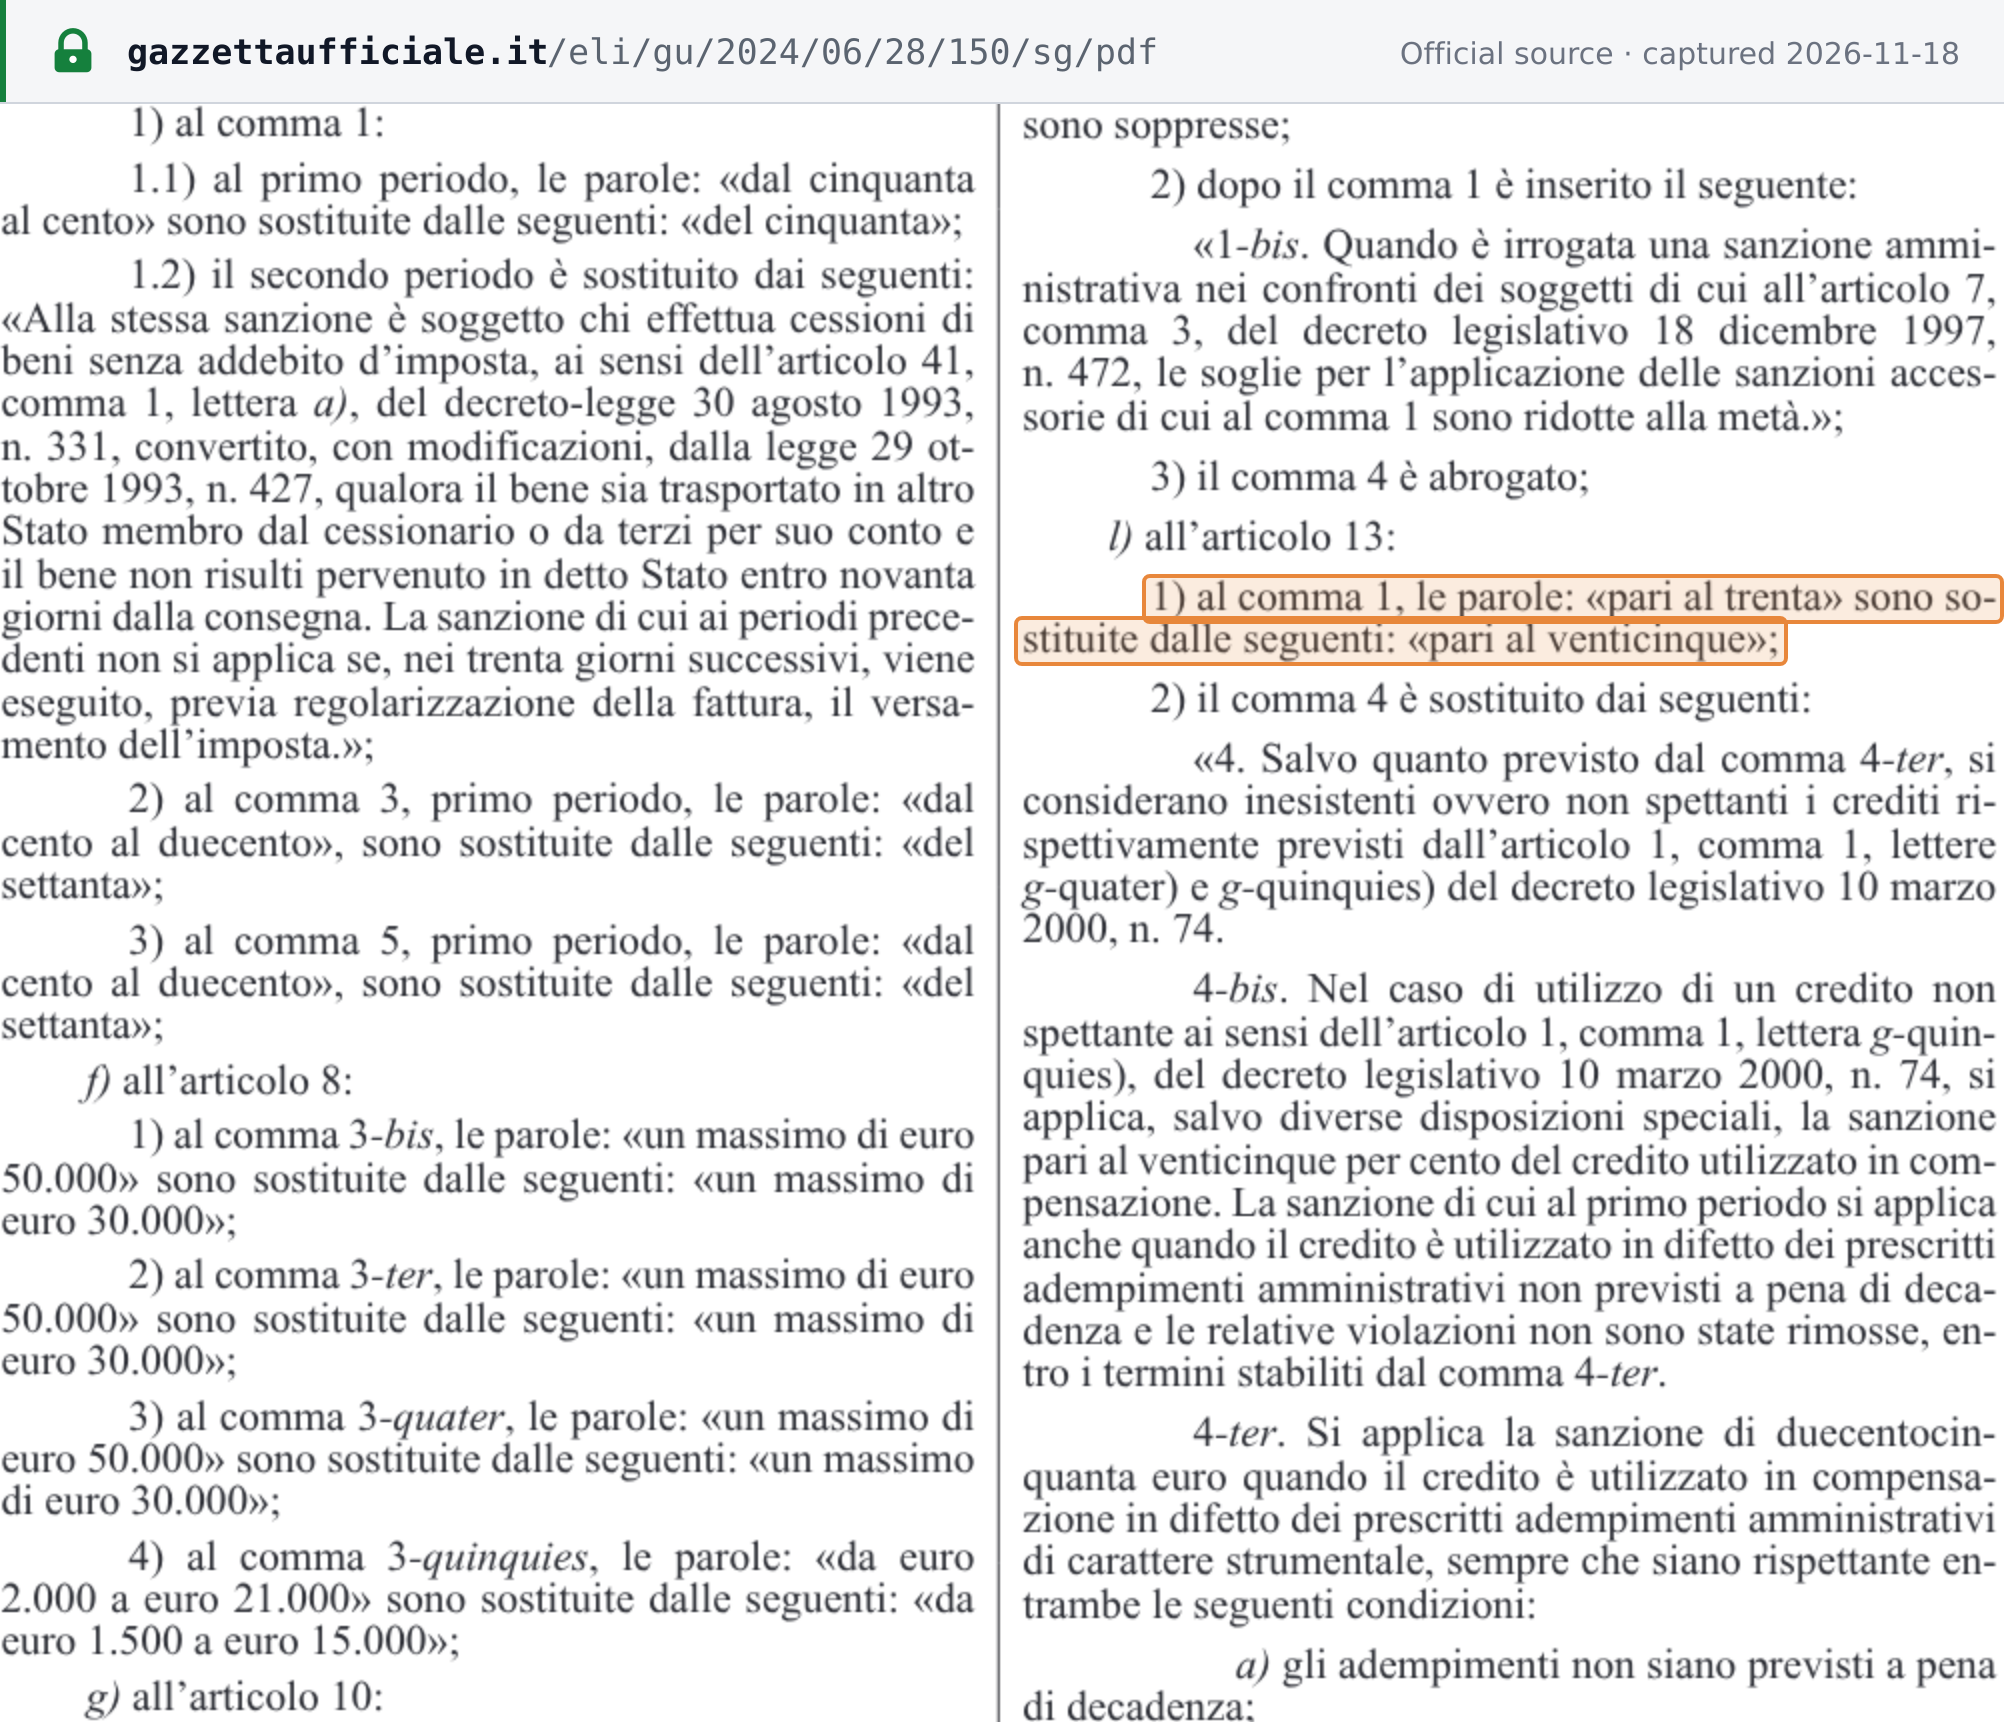 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · Gazzetta Ufficiale n. 150 del 28 giugno 2024, Serie generale: Decreto legislativo 14 giugno 2024, n. 87 · www.gazzettaufficiale.it