Japan will make crypto-asset lending non-taxable and count crypto transfers at 5% in the taxable-sales ratio
This page records one dated change. For the rules in Japan as they stand today, see the Japan guide →
- Jurisdiction
- Japan
- Tax
- JCT
- Change type
- Update
- Status
- Enacted
- Impact
- Plan ahead
- Announced
- 31 March 2026
- Instrument
- JP-CABINET-ORDER--8-96
- Authority
- 内閣 (Cabinet of Japan)
- Verified
- Fetched from official source · medium confidence
Businesses in Japan that lend crypto-assets or electronic payment instruments, and businesses that transfer crypto-assets and compute a taxable-sales ratio.
Plan ahead — expected 1 January 2028, subject to the companion law 令和8年法律第64号 commencing in 2027. Crypto lenders should prepare for exempt treatment of lending fees. Businesses that transfer crypto should recompute the taxable-sales ratio with 5% of transfer consideration in the denominator. Watch for the Cabinet Order fixing the companion law's commencement.
令和8年政令第96号 (CT Enforcement Order amendment, promulgated 31 March 2026) amended CT Enforcement Order Articles 9, 10(3)(xi) and 48. From the effective date, lending of crypto-assets and electronic payment instruments becomes non-taxable, and crypto-asset transfers count in the taxable-sales ratio at 5% of the consideration, as securities already do. Transfers had been left out of the ratio. The effective date is 1 January of the year after the companion FIEA/PSA amendment (令和8年法律第64号, promulgated 23 July 2026) commences. That law must commence by Cabinet Order by 22 July 2027, giving 1 January 2028 on current expectations.
What changed in detail
令和8年政令第96号, a Cabinet Order amending the Consumption Tax Enforcement Order, promulgated on 31 March 2026, amends Enforcement Order Arts. 9, 10(3)(xi) and 48.
- Lending. Art. 10(3)(xi) lists the lending of securities and registered government bonds as non-taxable. The amended text adds crypto-assets (暗号資産) and electronic payment instruments (電子決済手段), so fees for lending them become non-taxable.
- Taxable-sales ratio. Under Art. 48(5), transfers of securities count in the denominator of the taxable-sales ratio at 5% of the consideration. The amendment applies the same 5% rule to transfers of crypto-assets, which had been left out of the ratio altogether.
Under Supplementary Art. 1, item 3 of the Order, these amendments take effect on 1 January of the year after 令和8年法律第64号 commences. That law amends the Financial Instruments and Exchange Act and the Payment Services Act; it was promulgated on 23 July 2026 and commences on a date to be set by Cabinet Order. Supplementary Art. 3 keeps the old rules for transactions before the start date, with transitional rules for adjusted fixed assets and returns of consideration.
What it means
As of 15 November 2026 the change is enacted but not yet in force, and its start date is not fixed. It takes effect on 1 January of the year after 令和8年法律第64号 commences, and no Cabinet Order setting that commencement has been published yet. The law must commence by 22 July 2027. If it commences in 2027, the change applies from 1 January 2028, which is the date e-Gov currently shows. If it commenced before the end of 2026, the date would be 1 January 2027.
Crypto lending platforms should plan to treat lending fees as exempt and expect a lower taxable-sales ratio. Businesses that trade crypto should recompute the ratio with 5% of transfer proceeds included. That raises the denominator, which reduces the input credit for businesses that cannot credit all of their input tax.
Proof
十一 法別表第二第二号に規定する有価証券(ゴルフ場利用株式等を除くものとし、その権利の帰属が社債、株式等の振替に関する法律の規定による振替口座簿の記載又は記録により定まるものとされるものを含む。)、登録国債若しくは暗号資産又は電子決済手段の貸付け(xi) Lending of securities as defined in item 2 of Appended Table 2 of the Act (excluding golf-course membership shares etc., and including those whose ownership is determined by entries or records in transfer account books under the Act on Book-Entry Transfer of Company Bonds, Shares, etc.), registered government bonds, or crypto-assets or electronic payment instruments.
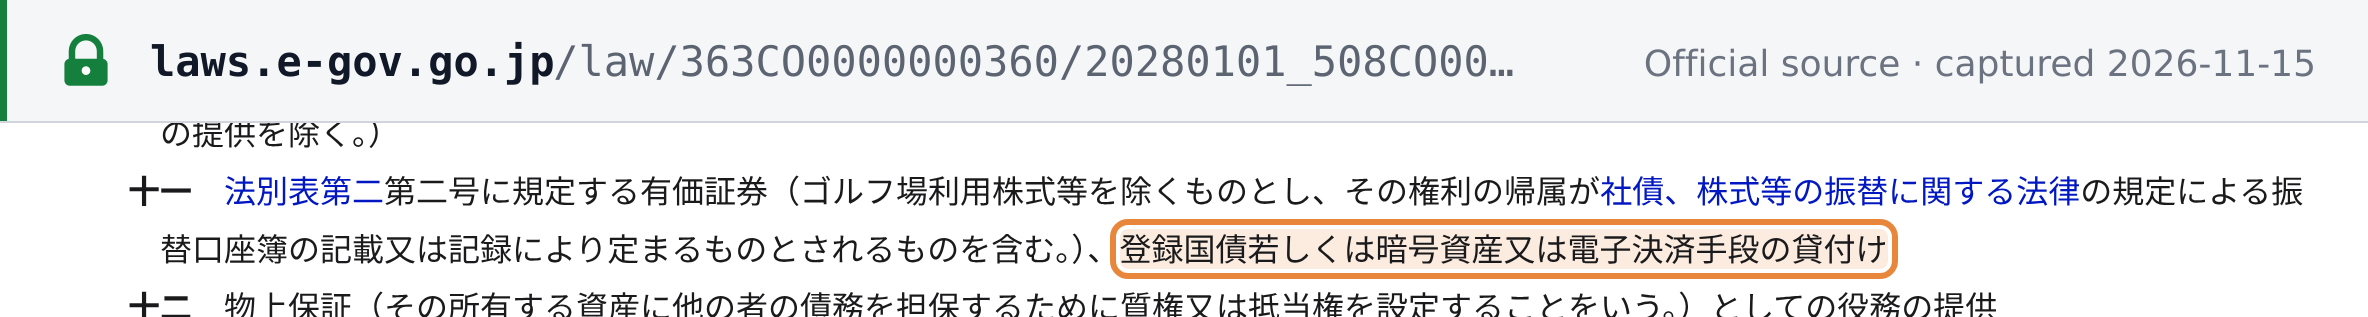 Source snapshot of the official page. Open full size ↗
Archived from the official distribution · 消費税法施行令(昭和六十三年政令第三百六十号), e-Gov law revision 363CO0000000360_20280101_508CO0000000096 (as amended by 令和八年政令第九十六号; e-Gov enforcement note: 第五号に掲げる規定の施行の日の属する年の翌年の一月一日), Art. 10(3)(xi) · laws.e-gov.go.jp